While contemplating starting a non-profit business, the main misconception people have is that running a non-profit is easy as there is no pressure from investors and no dealing with taxes. However, they are wrong as running a non-profit business can be as grueling as any other business and can also be hard to manage without proper awareness and knowledge.
Any non-profit business owner will tell you that there is a lot involved in starting a non-profit business, unlike for-profit businesses. Luckily, the internet is full of information and knowledge regarding starting and running a non-profit business with ease. Below are a few useful and authentic tips that will help a non-profit business owner make better decisions.
Learn the Importance of Market Research
To successfully run your non-profit business, it is essential to keep an eye on the ups and downs of the market you are tackling or working in. Unlike for-profit businesses, a non-profit business owner often has difficulty finding contributor’s support if another organization, whether non-profit, for-profit, or even government-operated, is engaging in the same work. Knowing your surroundings is a key factor that can make a significant difference between the success and failure of your non-profit business.
Have A Clear Mission Statement
The mission statement is why your non-profit organization or business exists because, with no clear mission, your non-profit can easily get lost in the crowd of non-profit organizations and end up achieving nothing. Having a clear mission will also help in getting more funds for services and other programs.
Good Record Keeping Practices
Whether it is a for-profit or non-profit business, keeping records plays an important role in any business success. A non-profit organization must maintain its non-profit status and keep its tax-exempt status by filing the IRS’s required paperwork. It is also important to keep accounting and financial records safe and up-to-date.
Founding and Keeping Funding Sources
It is almost impossible for a non-profit business or organization to stay up and running without any funding backing it up. Finding and keeping a legit funding source for a non-profit business is extremely important for its survival and growth. The best way to generate donors is to have a determined management team managing the donor database while maintaining corporate sponsors through other contacts and means. To retain donors, you must keep them up-to-date on your progress and let them know they are appreciated by inviting them to a thank-you lunch on occasion.
Maintain Good Public Relations
Even though you are running a non-profit business, having good public relations is as important as any for-profit business. Never miss an opportunity to promote your non-profit business, whether you are with friends and family, at a corporate event, or in other situations where people are gathered. Besides networking, another great way to build public relations is to create a press release as it can put your name in the mainstream and inform people about your non-profit and even encourage them to donate.
Avoid Doing Everything Yourself
Non-profit business owners often get founder’s syndrome, which makes them overly engaged in the day-to-day operations of the non-profit. Most non-profit businesses have capable staff, and as the owner, you have to let some of the responsibilities go and give them to the appropriate staff member.
Having a Board of Directors
An organization’s board of directors is a community of leaders and is one of the most important aspects of a non-profit business. The main purpose of having a board of directors is to provide legal support and proper supervision of the non-profit. Having a proper management system can lead to better teamwork among employees and encourage them to work harder, ultimately benefiting your non-profit business.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Low Credit Score Causes and Fixes: Avoid These Costly Mistakes
Low credit score causes and fixes boil down to identifying the behaviors dragging your number down—late payments, high credit utilization, derogatory marks, and credit report errors—then applying proven credit repair strategies like paying on time, lowering balances below 30%, and disputing inaccuracies through the credit bureau dispute process. Master those fundamentals, and you can move from “bad credit history” to a healthier profile in as little as 6–18 months.
After 20+ years as Founder and CEO of Complete Controller, I’ve had a front-row seat to thousands of credit comeback stories—business owners denied loans, families turned away from rentals, founders boxed out of better terms. The pattern is always the same: the people who recover fastest don’t chase hacks. They follow a system. In this guide, I’ll walk you through the same step-by-step framework I share with our clients—what causes low scores, the fastest legitimate fixes, the mistakes to avoid, and a 90-day plan to start rebuilding now.
What are the low credit score causes and fixes you need to know?
The main low credit score causes are late payments, high credit utilization, collections or charge-offs, too many hard inquiries, and credit report errors—and the fixes are on-time payments, lower balances, disputing inaccuracies, and smart use of credit-building tools.
Payment history drives 35% of your FICO score, making late payments the #1 cause of low scores.
Credit utilization ratio accounts for 30%—balances over 30% of your limit signal risk to lenders.
Credit report errors affect 1 in 5 consumers and can be disputed for free through the credit bureaus.
Tools like a secured credit card, credit builder loan, and autopay for bills create the consistent on-time payment history needed to rebuild faster.
Understanding the Real Causes Behind a Low Credit Score
A low score is never random—it reflects specific behaviors and events in your credit file. Before fixing anything, you need to know exactly what’s hurting you.
FICO score factors and the main low credit score causes
According to FICO, payment history makes up 35% of your score and amounts owed (including credit utilization) makes up another 30%—which is exactly why late payments and high balances are the two biggest drivers of a low score.
Payment history (35%) — Late payments, charge-offs, and collections do the most damage.
Amounts owed / credit utilization (30%) — Maxed-out cards signal risk, even when you pay on time.
Length of credit history (15%) — Closing old accounts can shorten your average account age.
New credit (10%) — Multiple hard inquiries in a short window lower your score temporarily.
Credit mix (10%) — A blend of installment and revolving accounts helps slightly.
The founder’s takeaway: pull all three credit reports first, list the specific behaviors and eventshurting you, then build your fix list. Diagnosis drives strategy.
The Most Common Low Credit Score Causes (And How They Show Up)
Late payment impact and chronically missed bills
Even one payment more than 30 days late can drop your score significantly, and delinquencies stay on your report for up to 7 years. The Consumer Financial Protection Bureau found that medical debt is the most common collection item on credit reports, appearing on roughly 1 in 5 reports—a powerful reminder that a single health event can spiral into collections fast.
Common patterns I see with clients:
Bill pileup after job loss or a medical event
Subscriptions auto-renewing on expired cards
Small forgotten store cards quietly going to collections
Fixes that work:
Set up autopay for bills—at least the minimums—on every credit obligation.
Call creditors the moment you slip; many will work out a plan or adjust reporting.
Send a goodwill adjustment letter when a one-time hardship caused an isolated miss.
High credit utilization: silently dragging scores down
Your credit utilization ratio is revolving balance divided by total credit limits. The CFPB and major issuers recommend staying below 30%, with scores responding best under 10%.
Practical fixes for credit utilization:
Pay down balances aggressively, starting with the highest-interest card.
Make multiple payments per month so the statement balance reported to bureaus stays low.
Request a credit limit increase—without increasing spending—for an instant utilization drop.
Spread purchases across cards so no single account gets maxed.
Serious derogatories: charge-offs, collections, and bankruptcy
These are heavy hitters that can block apartments, raise insurance, and crush business credit. The fix is patient but proven: bring past-due accounts current, negotiate pay-for-delete in writing on collections when possible, and let new positive data slowly outweigh old negatives.
Credit Report Errors: The Hidden Cause Most People Overlook
A landmark FTC study found that 1 in 5 consumers had an error on at least one credit report, and for 1 in 20, the error was serious enough to cost them money on credit. This is often the fastest win in credit repair.
How to dispute credit report inaccuracies the right way
Get your reports for free at AnnualCreditReport.com from Equifax, Experian, and TransUnion.
Mark every potential error—unknown accounts, wrong balances, duplicate listings, misreported lates.
File disputes with both the bureau and the furnisher (the company that reported the info), with documentation.
Track responses—investigations typically take 30 days, and corrected items must be removed or updated.
Removing a single erroneous late payment or collection can yield a meaningful score jump in weeks, not months. For more on building strong financial habits alongside credit repair, our team covers practical tactics in how to manage your credit responsibly.
Low Credit Score Fixes: A Practical Roadmap to Rebuild Faster
Build flawless on-time payment history
Payment history is 35% of your score, so this is non-negotiable. Automate minimum payments on every account, then set calendar reminders 5–7 days before due dates as backup.
Crush your credit utilization ratio
Target overall utilization under 30%, then push toward 10%. Make mid-cycle payments so reported balances stay low, and consider a consolidation loan only if you won’t re-max the cards afterward.
Use rebuild tools wisely
Credit builder loan: Credit unions place loan funds in a locked account while you make small monthly payments, building installment history with low risk.
Secured credit card: A $200–$500 deposit becomes your limit. Put one small recurring charge on it, pay in full monthly, and keep utilization under 30%.
Be selective with new credit
Avoid stacking applications—multiple hard inquiries compound the damage. Keep old fee-free accounts open to preserve your credit history length. For deeper systems-thinking on managing money flow, our guide on efficient business finance management translates directly to personal finance too.
Better credit starts with better financial habits. Complete Controller can help you build both.
Real-World Case Study: From Sub-600 to Mortgage-Ready
A Sound Credit Union case study highlighted a member whose score dropped below 600 after high utilization and several late payments during a job loss. Over 12 months, they set up autopay, paid balances below 30% utilization, requested limit increases, and avoided new credit while monitoring reports. By month 12, their score recovered enough to qualify for favorable loan terms—and their financial stress dropped dramatically.
The lesson: you don’t need a “credit repair” company. You need a structured plan and 12–24 months of consistency.
How to Improve Your Score Without Falling for Scams
The FTC is clear: no company can legally remove accurate negative information from your credit report. Any firm promising to “erase” legitimate late payments or bankruptcies is misleading you. Protect yourself by:
Running the credit bureau dispute process yourself—it’s free.
Choosing a nonprofit credit counseling agency over for-profit “repair” shops.
Walking away from advance-fee demands or anyone telling you to create a new credit identity.
List every cause: late payments, utilization, derogatories, errors.
Activate autopay on every debt.
Days 8–30: Execute high-impact fixes
Pay down any card above 50% utilization fast.
File disputes for every error with documentation.
Open a secured credit card if needed.
Days 31–90: Build momentum
Maintain scheduled paydowns; skip new applications.
Add a credit builder loan if your file is thin.
Re-pull reports at 60–90 days to confirm corrections posted.
Final Thoughts: Fixing Your Credit Is a System, Not a Hack
When clients ask me how to fix a low credit score, I tell them the truth: it’s fixable, but it’s not a one-week sprint. The most reliable low credit score fixes are simple—on-time payments, low utilization, accurate reports, and smart use of tools like a secured credit card or credit builder loan. The discipline is what separates the people who rebuild from the people who keep cycling through the same mistakes.
After two decades helping thousands of business owners and families through Complete Controller, I can promise you this: the financial confidence that comes with rebuilt credit is worth every disciplined month. If you’d like help building the bookkeeping and financial systems that support stronger credit—personally or in your business—visit Complete Controller to see how our team can support you.
Frequently Asked Questions About Low Credit Score Causes and Fixes
1Q. What are the main causes of a low credit score?
A: The biggest causes are late or missed payments, high credit utilization above 30%, collections and charge-offs, multiple recent hard inquiries, and bankruptcies. Credit report errors—which affect 1 in 5 consumers—can also unfairly drag your score down.
2Q. How fast can I improve a low credit score?
A: Utilization-driven improvements can show in 1–2 billing cycles once balances drop. Disputing and removing errors can yield gains in 30–45 days. Serious derogatories take 12–24 months of consistent, positive behavior to meaningfully offset.
3Q. How long does negative information stay on my credit report?
A: Most late payments, collections, and charge-offs stay on your report for 7 years. Chapter 7 bankruptcies remain for 10 years. Hard inquiries fall off after 2 years.
4Q. Should I close old credit cards to fix my score?
A: Generally no. Closing old accounts shortens your average credit history length and can reduce your total available credit, which spikes your utilization ratio. Keep fee-free old cards open and active with a small recurring charge.
5Q. Are credit repair companies worth the money?
A: Usually not. The FTC confirms no company can legally remove accurate negative information. Every dispute and rebuild tactic they use is available to you for free—either directly or through a nonprofit credit counseling agency.
Sources
FICO. “What’s in my FICO® Scores?” https://www.myfico.com/credit-education/whats-in-your-credit-score
FICO. “What is a FICO Score?” https://www.myfico.com/credit-education/what-is-a-fico-score
Sound Credit Union. (2023). “How to Rebuild Credit Score Fast After a Financial Setback.” https://www.soundcu.com
Consumer Financial Protection Bureau. (February 2022). “Medical Debt Burden in the United States.” https://www.consumerfinance.gov/data-research/research-reports/medical-debt-burden-in-the-united-states/
Consumer Financial Protection Bureau. “What is a Credit Utilization Rate?” https://www.consumerfinance.gov/ask-cfpb/what-is-credit-utilization-en-314/
Federal Trade Commission. (December 2012). “Report to Congress Under Section 319 of the Fair and Accurate Credit Transactions Act of 2003.” https://www.ftc.gov/reports/section-319-fair-accurate-credit-transactions-act-2003-fifth-interim-federal-trade-commission-report-congress-accessed-december-2012
Federal Trade Commission. “Disputing Errors on Credit Reports.” https://www.consumer.ftc.gov/articles/disputing-errors-credit-reports
Complete Controller. “How to Manage Your Credit Responsibly.” https://www.completecontroller.com/how-to-manage-your-credit-responsibly/
Complete Controller. “Efficient Business Finance Management.” https://www.completecontroller.com/efficient-business-finance-management/
Complete Controller. “5 Money Management Tips to Help Avoid a Deficit.” https://www.completecontroller.com/5-money-management-tips-to-help-avoid-a-deficit/
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Jennifer BrazerFounder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.
If you are a new small business owner or a small business owner looking to expand your business, you’ll need financing. Whether you choose to go with investors or seek loans from a financial institution is important that you have all the documents needed to increase your chances for financing. Besides a business plan, the most important documents you will need to help you get investors, keep investors, or obtain loans are financial statements.
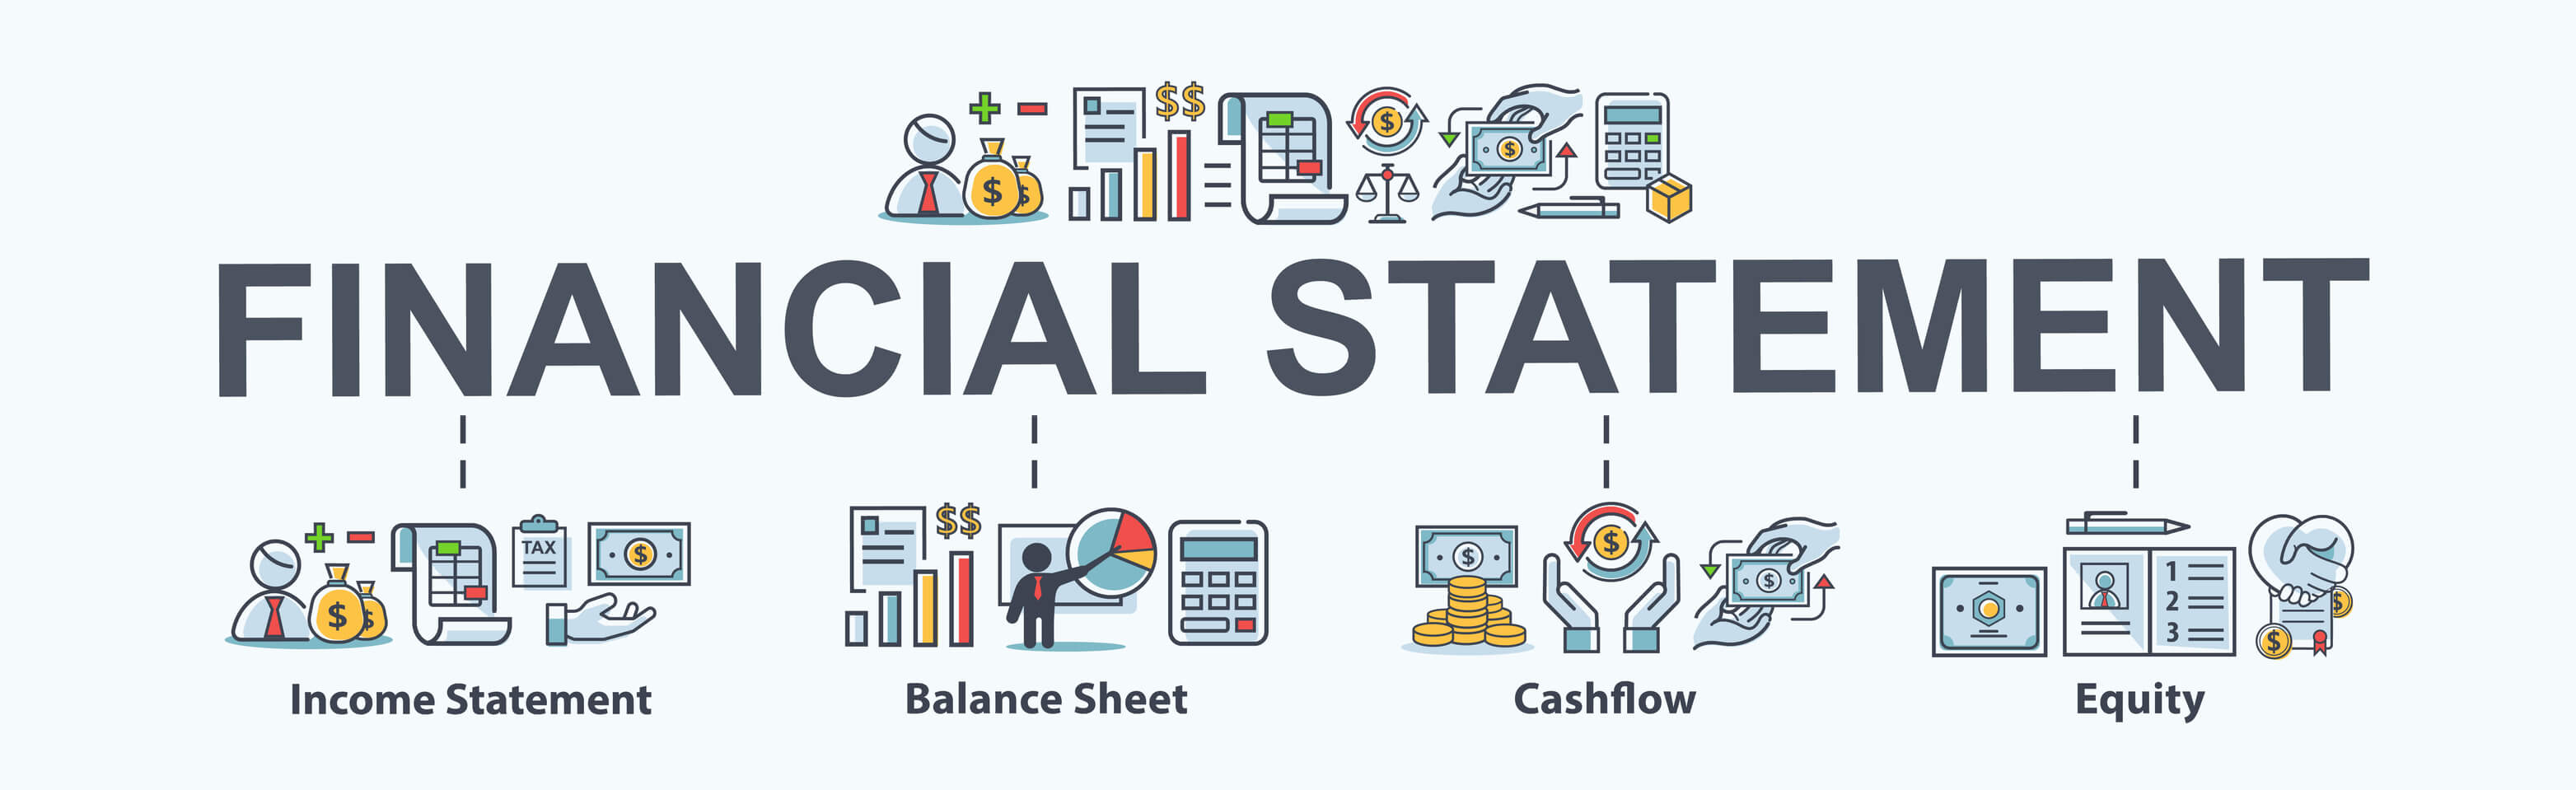
There are four main statements that you will need. These four statements are the income statement, the balance sheet, the owner’s equity statement, and the cash flow statement. Every business owner must understand all four of these statements and the information they provide.
The Income Statement
The income statement helps investors and lenders the idea of your business’s performance over a specific timeframe. The income statement is also known as a profit and loss statement (P & L) or revenue and expense statement. It shows investors and lenders your business’s nonoperating and operating expenses and revenue, no matter what it is called.
A person will share the business’s income statement to help potential investors and lenders understand how your business performs and whether the investment would be a good one.
The Balance Sheet
The balance sheet is also known as a statement of net worth or a statement of financial position. The balance sheet is based upon the equation assets = equity + liability. This statement will show investors and lenders your business assets, liabilities, and equity. It also provides them with the overall position of your business over a specific timeframe. Generally, the balance sheet is used to help your accountant calculate financial ratios.
The balance sheet is perhaps the most commonly shared financial statement because it gives a great overview of its financial position. It also quickly gives investors and lenders an idea of whether financing your business is a safe and minimal risk.
The Cash Flow Statement
The cash flow statement is also known as a statement of cash flow or a statement of financial position changes. The cash flow statement is used by investors or lenders, and the business owner and accountants to see whether the business generates enough cash to meet obligations and operating expenses. In other words, it gives everyone an understanding as to how the business is managing its cash flow.
The cash flow statement is crucial for understanding the business’s ability to pay bills, accounts payable, and meet payroll and inventory demands. This statement should not be confused with the owner’s equity statement. This is the money used from profits to finance the business’s daily operations and is not an investment.
The Statement of Owner’s Equity
The statement of owner’s equity is also known as the statement of changes in equity or a statement of shareholder’s equity. This statement specifically shows profits and earnings that are being retained by the business and not distributed to shareholders. These earnings are generally used to reinvest in the company, pay off debts, or finance business growth.
This statement is generally used to give an idea of the financial stability and health of a business. It shows if a business can meet financial and operating needs. All done without requiring new contributions of capital from the owners or shareholders.
Conclusion
These very important financial statements will be used in multiple ways. They will be used when seeking investors or trying to obtain business loans. They are also used after a business is established to give shareholders, possible investors, and lenders an assessment of the business’s financial aspects. It is essential that these four financial statements be accurate and up kept. These four financial statements can be the difference between your company receiving funds and financing and going out of business.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
The excitement of getting a new job and then starting it is unexplainable, but you must first get through the interview before you even get the job. Simultaneously, many will advise you on how to answer questions and present yourself. Another aspect of interview preparations should be learning the types of interviewers and how to recognize them. This knowledge could mean the difference between nailing the interview or failing it.
Every interviewer develops a distinctstyle. An average person changes his job seven times in his whole life that means more than seven interviews. Before going for an interview, it is wise to know about the interviewers and plan how one should face them. Here are seven types of interviewers you might encounter during the interview process and how to prepare for them.
The Geek
Interviews can be scary, especially when your interviewer is ready to tear you apart with their extreme knowledge of the world. These interviewers know a lot about the job description of the position you have applied for. Brace yourself for such an interviewer. You can expect questions about the subject matter, technical details, standard operating procedures, etc. There will not be any personal questions or informal details with this type of interviewer. You should be preparing for this type of interviewer by having a lot of job knowledge specifically related to the position and the company you are applying to.
The Shotgun
This type of interviewer will start asking you questions after questions as soon as you enter the room. Expect a shotgun that will not stop firing at you. You will not have enough time to start a conversation, and you will find yourself preparing for the next question. It would be best to prepare answers for every possible question you can find online or from any other source. Such interviewers ask questions that can be HR based or revolve around your professional knowledge.
The Classic
This kind of interviewer will follow the classic and traditional style of interviewing. The classic interviewer will ask about your skills and your future plans, and your past work experiences. This kind of interview takes thirty to forty-five minutes to finish. You can research many questions online about this traditional kind of interview. Some of the questions are most likely to be repeated so you can consult the person who has been interviewed before. Most classic interviewers love to ask scenario-based questions, so be prepared with a few examples from your past work experiences.
The Calm
These kinds of interviews are what all job-seekers hope for when stepping into an interview room. Such interviewers will make you feel at home, and all you need to do is accept this friendly gesture and go with the flow. The calm interviewer will not make you feel nervous. These kinds of interviewers are tricky as well. They will find out about your strengths and weaknesses without judging your knowledge. Try to start a conversation and establish a bond, yet do not forget to cast a professional impression on this interviewer. The best way to handle a calm interviewer is to remain professional and not get too comfortable.
The Judgmental
Judgmental interviewers believe in the phrase “the first impression is the last impression.” It is difficult to decipher what these interviewers are thinking, as they are extremely difficult to read. They are likely to maintain a grumpy expression on their face or have no expression at all. You will be uncertain about your answers, and you will never know whether your answers were right or wrong. These interviewers are most difficult to deal with, so the best tip here is to be confident about yourself and the answers you give because you will not get an appreciative smile.
The Professional
Professional interviewers are the most balanced and will often have set criteria of outlines for the interview. They are not too rigid, not too friendly, yet they know how to maintain a professional appearance from start to finish. You can expect a few smiles and maybe even a few indications of how well the interview may be going. The tip here is to adjust with their mood and answer the questions carefully and appropriately.
The Distracted
This type of interviewer will make you feel as if they are the busiest person on the face of the earth. You will find them going through their phone and mail repeatedly while answering their questions, and it can be highly distracting. Do not get annoyed with this behavior. Do not get trapped and lose your concentration while answering them. Take the questions seriously and answer them after thinking twice. Do not try to get his attention. Do not get distracted and do not try to avoid the questions.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
No matter the business’s size, your business culture will drive the type of employees you hire for open positions. While skills and talent are of great importance, you need to hire employees that fit with the company and promote a positive work environment. Every employee you have in your company contributes to the workspace’s morale and energy, and ultimately they represent you and the business to both current and potential customers or clients. Here are nine key steps you need to implement to help in hiring the perfect employee.
Define the Job
Before you post the job online, you must do a job analysis and have a thorough list of job requirements. It would be best to break these into sections such as job description, required skills, education requirements, and environment.
When formulating the job posting, you should use concise wording and bullet points and have a job summary, attitude, and environmental expectations. Chances are you will have many people apply that are not qualified but have defined job requirements, detailed job descriptions, and including the environment and attitude will help pull out applications and resumes of those who match a lot of your keywords.
Plan Your Recruiting Strategy
Generally, a team in the human resources department is dedicated to posting jobs, conducting interviews, and hiring employees in a larger company. However, in a small business, this is generally done by the owner or a trusted employee. Because a smaller business is more intimate, it may be important for all employees to have some input to the hiring and recruiting process.
Create a Checklist
Creating a checklist may seem like a simple process, and in most cases, it is. However, having a checklist of what you need and expect in an employee will help you streamline the hiring process. Creating a checklist can also help keep all current employees involved in the hiring process on the same page as far as expectations and recruits that have potential.
Recruit the Right Candidates When Hiring an Employee
If possible, create the largest talent pool to choose from when hiring a new employee. Use available online tools such as hiring sites and social media to widen your talent pool as much as possible. The more potential candidates you have, the better chance you have of hiring the perfect employee.
Review Applications, Resumes, and Cover Letters Carefully
Have an effective system in place to review cover letters, resumes, and job applications. This process starts with a well-written job description and bullet points and your checklist. Screen all potential candidates against your list of skills, characteristics, job experience, and other important hiring points. Having this part of the process precise and streamlined will ensure that you can narrow the field of good candidates down to great ones.
Prescreen Candidates
While many candidates will look great on paper and have a compelling cover letter, they still may not be the right fit for the position or your company. Before taking the step to set up a face-to-face interview, you should do a phone interview to get an idea if they are still in the running before you go further in the process.
If you feel a candidate isn’t the right fit through the phone interview, you can eliminate them from the process at this point and not waste anyone’s valuable time.
Ask the Right Questions
The hiring team or business owner should develop standard interview questions that will be identical in each interview. This way of designing the interview questions will help you make a side-by-side comparison.
When formulating the questions, make sure every question you ask has value. There should be no throw-away questions to fill time. Organizing the questions will also ensure the interview stays focused and on track.
Do Background Checks and Check References
After you conduct interviews and have further narrowed down the best candidates, you must do thorough background checks. Once candidates have passed these checks, you must check with their references.
In most cases, all of the candidates who have made it this far in the process will also pass these checks. However, there could be candidates in the running that are eliminated because something negative comes up in these checks.
Extend a Job Offer
Once you have completely narrowed the field to the top candidates, you may need to conduct second interviews before making a final decision. When you have decided and have chosen the best candidate, it is time to draw up a job offer.
The job offer should include salary and benefits and the expected start date. Once you have sent the offer, either the candidate will accept the offer, decline it, or make a counteroffer. And the hiring process will come to an end once everyone agrees.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
When you come to the financial point in your adult life where you have decided it’s time to look into investing some of your hard-earned money, there are many types of investments you could consider. There is the stock market, mutual funds, 401(k) or other retirement savings accounts, and countless other investments you could (and should) look into to diversify your investment portfolio.
However, real estate investing is often an area people don’t think they can invest in for many reasons. It could be credit issues, lack of start-up investment capital, or fear of the risks involved in investing. Whatever the reasons you have hesitated to invest in real estate, here are five good reasons you should consider real estate investments.
Property Appreciation
Property appreciation isn’t that you appreciate that you own the property. This use of the word means the increase in the value of a property. Many purchases of property depreciate as soon as you purchase them, such as a car. A car depreciates in value the second you drive it off the lot because it immediately has factors attached to it that decrease the value, such as mileage and previous ownership.
Real estate is not like that. Real estate property values increase (or decrease) according to the real estate market. While it is true that there have been severe downturns in the real estate market over the years, for the most part, if you can ride these downturns out with the property you own while possibly obtaining more properties for spare change on the dollar, you can make out well during those few and far between times.
If you are investing in a property you intend to flip and sell, then a slower or bottom market would not be ideal since you might get the property for a steal but may not be able to resell it. However, buying a property to use for passive rental income, buying low, and investing enough to fix any issues, then renting it out will be ideal. You can then wait for the market to heat back up and resell it (once the lease is up) for a nice profit. Or you may choose to keep it as a rental property collecting that sweet passive income.
Cash Flow Income
Speaking of passive income and rental properties. Cash flow income is, as mentioned before, using your purchased property or even buying already established rental properties for the sole purpose of renting out space(s) for continuous passive income.
The cash flow income can be more resilient if the real estate market takes a hit or crashes. These passive income properties can even sustain you through overall economic downturns or personal financial difficulties.
Real Estate Related Income
You may be thinking we have been talking about real estate related income this whole time, and we have, but this particular use of the phrase is referring to income generated from a real estate job-related source.
Real estate-related jobs could be a real estate agent or real estate broker, both of which gain their income from real estate sales commissions. Another real estate related job is property management. This job entails running a property such as a building with offices, an apartment complex, or a hotel for an owner who wants to remain hands-off and have someone else manage their investments.
While this may not seem like an investment in real estate, if you do not own the properties yourself, these real estate related jobs are an investment in your career and future financial stability.
Ancillary Real Estate Investment Income
When most people hear real estate investing, they likely conjure up the idea of owning real estate property and either reselling for a profit or using it as a rental property as a passive income. Ancillary real estate investing is ownership of investments that generate income, such as vending machines, paid laundry facilities, ATMs, and other smaller businesses operated within larger real estate investments.
Because these types of machines are in places that make them convenient, they can create a decent income due to the customers’ semi-captive nature. These types of real estate investments could be a great starting point for someone without a lot of capital to invest or without a lot of experience in real estate investing.
Your First Property Investments
If you have the capital for a down payment and the credit score to do it, you may want to consider purchasing your first real estate property through a mortgage loan. You can then use this property a few ways to get returns on your investment. You can make sure the mortgage loan includes money for upgrades and fix it and flip it for a profit, which will pay off the mortgage and give you a profit. Or you can use it as a rental property setting the rent to cover the monthly mortgage and yearly dues and property taxes along with padding for profit.
If you don’t have a lot of starting capital to invest in a property on your own, there are crowdfunded investment groups. Each person in the group will invest a minimum amount, and the group will invest in a property and split the profits made through rentals or resale.
You can also look into the option of ancillary real estate options as they are often fairly inexpensive to invest in and can gain you immediate profits from day one of placement.
Conclusion
Keep in mind that different liabilities depend on what type of real estate investing you get into and weigh these liability risks against the rewards. Overall, real estate investing is a great investment path to take and is, for the most part, far less risky than the stock market. Look into the options mentioned and see if any of them is right for you.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
There are several kinds of accounting software available to small businesses. Whether it is overall accounting and bookkeeping software, inventory software, payroll software, or other business-related software that helps with the financial aspects of operations, most small businesses employ the use of one or more of these. Now there is software specifically related to electronic invoicing.
Some accounting software includes an electronic invoicing in the overall business accounting software package, but many do not. This would be the reason you may want to consider getting electronicinvoicing software. Here are eight reasons you should be electronically invoicing now!
Save time
Because of the automation, electronic invoicing saves a large amount of time previously spent manually invoicing. Many of the steps are eliminated once the process is automated because they are unnecessary in the electronic invoicing process.
Reducing Costs
When using the manual, paper invoicing, there are several costs involved. Printer ink, paper, envelopes, and postage are all costs involved in manual and paper invoicing. Besides the initial cost of the software, there is no cost involved in electronically invoicing your customers. It also saves money if you have to follow-up with reminders and late notices. Some companies give the customer the option to go paperless, but you will save money by electronically invoicing.
Reducing Errors
Because manual invoicing requires so many steps done manually, it increases the chances of errors in the process. There are many opportunities for errors, whether typos or incorrect data in the invoice or incorrectly addressing the envelope. Electronic invoicing still requires input. However, it will generally prompt error checks, and the rest of the process is automated and via email, so the chance of errors is minimized.
Customer Service
Because of the reduction in time, cost, and errors, there is a direct benefit to your customer. Also, because they will receive their invoices immediately, they can add the cost to their budget. Electronic invoicing is also more professional and can increase the overall positive impression of your business. The ease, accuracy, and speed will also increase customer confidence in your business’s abilities creating long-term customers.
Get Paid Quickly
Because the customer is invoiced immediately instead of the time it takes to mail an invoice, it is far more likely the invoice will be paid quickly. Most customers who fail to pay forget about the payment. With electronic invoicing, they will receive the initial invoice, but remindersare more easily sent because of the simplification of the process.
Reducing Paper Use
With awareness of the environment and recycling being the focus of many, reducing paper use will benefitthe environment. The reduction of paper for the invoice and the envelope will positively impact and give your customers who are concerned with the environment another reason to choose your company.
Accurate Record-Keeping
Because the process is generated and recorded through the software, this will ensure accurate records. This accuracy is especially important for taxes and operations. It also allows an overview of outstanding invoices that may require more intense measures to recover. Overall you will have easy to understand records that will help keep accounting and bookkeeping accurate and efficient.
More Control
Manual invoicing also means manual record-keeping and other processes. Having the electronic invoicing process from beginning to recording in the software gives you more control over your invoices and the invoicing process. Most of the invoicing issues are that the manual process can allow the invoices to get away from you. This control and accuracy, ease of access to what has been received, and what is out will give you strong invoicing control.
Conclusion
There are no downsides to electronic invoicing, and no reason it should not be utilized in your business immediately. Electronic invoicing saves time, money, and errors and will give you and your accountantaccuracy and more control.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
5 Creative Investment Ideas for a Stronger Portfolio
Creative investment ideas for a stronger portfolio blend traditional assets with smarter, less-traveled opportunities—diversified alternatives, impact and ESG themes, arts and entertainment ventures, digital and IP-based income streams, and tax-smart philanthropic structures. Used together, these five ideas help you add resilience, fresh income streams, and long-term growth potential without abandoning the discipline that keeps real wealth intact.
Here’s something that gets me fired up: Bank of America’s 2024 Study of Wealthy Americans found that the average high-net-worth allocation to alternatives jumped to 13%, up from 10% in 2022—and 54% plan to increase it again. That’s not a fad; that’s a quiet revolution in how serious investors build portfolios. Over the past 20+ years running Complete Controller, I’ve had a front-row seat to thousands of business owners and investors figuring out what actually works versus what just sounds clever at cocktail parties. In this article, I’ll share five creative ideas I’ve watched succeed in the real world, plus a 90-day roadmap to put them into action with confidence.
What are the 5 best creative investment ideas for a stronger portfolio and how do you use them?
Diversified alternatives, impact/ESG themes, arts and entertainment ventures, digital and IP assets, and tax-smart philanthropy are the five creative investment ideas that build a stronger portfolio.
Alternatives like real assets, private credit, and commodities reduce correlation to public markets and hedge inflation.
Impact and ESG investing aligns your dollars with macro trends like the energy transition and longevity.
Arts, entertainment, and creator economy plays offer growth tied to a $250B–$480B market expansion.
Digital and IP assets—courses, royalties, content libraries—create scalable passive income when treated like real businesses.
Donor-advised funds and philanthropic structures function as a strategic “fourth pillar” that boosts after-tax wealth and legacy impact.
Understanding Creative Investment Ideas Without Losing Your Financial Footing
Let me be clear about what “creative” means here. Creative does not mean speculative roulette. It means thoughtful diversification into opportunities outside the basic stock-bond-cash trio, guided by data, time horizon, and good bookkeeping. The investors I’ve seen build lasting wealth treat creativity as a discipline, not a dare.
What are creative investment ideas in 2026?
Creative investment ideas in 2026 are strategies that expand beyond traditional holdings to capture macro themes—AI infrastructure, energy transition, the creator economy—while respecting correlation, liquidity, and risk-adjusted return. Think of it as a core-satellite model: your stable core stays boring and diversified, while your creative satellite (often 10–25% of the portfolio) chases smarter upside.
Building a creative investment strategy around your real life
A solid creative investment strategy starts with three honest questions: What are my goals? What’s my time horizon? What can I actually afford to lose? Once you know that, decide what percentage of your portfolio belongs in the creative sleeve and tag every position in your bookkeeping so you can review it quarterly. I had a client who turned a scattered pile of “fun money” bets into a tracked, disciplined satellite portfolio. Same dollars, dramatically better outcomes—because she could finally see what was working.
Creative Investment Idea #1 – Diversified Alternatives That Support Your Core
Alternatives have moved from “exotic” to “essential.” According to Bank of America’s 2024 Study of Wealthy Americans, wealthy investors now allocate 13% on average to alternatives, with more than half planning to increase that further. If the most sophisticated investors are leaning in, that’s a credibility anchor worth paying attention to.
Creative assets investment strategies in real assets and commodities
Real assets—infrastructure, real estate, renewable energy projects—and commodities like gold or broad commodity funds can buffer inflation and smooth volatility. The trick is position sizing. A 5–15% sleeve, sized to your risk tolerance, usually does the job without making your portfolio lopsided.
Best creative investment opportunities in 2026
The biggest themes I’m watching with clients:
AI infrastructure and power generation for data centers
Creative Investment Idea #2 – Impact, ESG, and Societal-Shifts Investing
Impact investing has matured. It’s no longer a values-only choice—it’s a way to ride durable macro trends like clean energy, longevity health, and climate adaptation while keeping diversification intact.
Innovation funding through impact and ESG themes
You can fund innovation through green bonds, themed ETFs, and community development funds. The key is screening for genuine ESG versus greenwashing—look at fund holdings, methodology, and reporting. The CFA Institute’s ESG framework is a strong reference point for what good looks like.
How to build a creative investment portfolio with impact at the center
Here’s a simple sequence I walk clients through:
Define the causes you care about (climate, housing, education)
Map the vehicles available—ETFs, social-impact bonds, community funds
Set an allocation rule (e.g., “10% of my creative sleeve targets impact themes”)
Track returns and impact metrics in your bookkeeping system
One family client paired ESG funds with a donor-advised fund and got something rare: alignment between their values, their tax bill, and their long-term wealth plan.
Creative Investment Idea #3 – Arts, Entertainment, and the Creator Economy
Arts and entertainment investment as an asset class
You can invest in this space through:
Direct equity in creative startups and production companies
Royalties from music, film, or licensing deals
Pooled funds that spread risk across many creative projects
The risks are real—illiquidity, high failure rates, the need for serious due diligence. Diversify across many bets, not one.
Venture capital for creative industries and creator economy businesses
The creator economy includes paid newsletters, niche learning apps, and AI-enhanced content tools. I’ve watched investors back creator-platform startups that scaled with subscription and transaction revenue, delivering strong multi-year growth. The investors who won shared one habit: they demanded clean, transparent books from the startups they funded—which is exactly where our business bookkeeping essentials come in.
The best investment strategy starts with clear financial visibility. See how Complete Controller helps you organize your finances with confidence.
Creative Investment Idea #4 – Digital Assets, IP, and Scalable Passive Income
This isn’t about crypto speculation. It’s about treating digital and intellectual property like the real businesses they are. A famous example: David Bowie’s “Bowie Bonds,” inducted into the Rock & Roll Hall of Fame in 2015, turned music royalties into a tradeable, income-producing asset—a blueprint that still inspires today’s IP investors.
Creative investment ideas for beginners in digital and online assets
Beginner-friendly entry points include revenue-share deals in online course businesses, small equity in membership sites, or buying a profitable newsletter to improve and grow. Start small, track every dollar, and learn the mechanics. See our guide on earning with online courses for a deeper look.
Investing in startups in the creative sector and online ventures
When evaluating a creative-sector startup, look at:
Recurring revenue percentage
Creator or platform dependency risk
Quality of financial reporting
I had a client running a profitable digital course business who only attracted serious investors after we standardized her bookkeeping. The business hadn’t changed—the visibility had.
Creative Investment Idea #5 – Philanthropy and Tax-Smart Structures
Strategic giving is one of the most underrated wealth tools I know. Donor-advised funds (DAFs) unlock immediate tax deductions, let you donate appreciated securities to avoid capital gains, and give you decades to direct grants. The IRS guide to donor-advised funds is a great starting point.
Bunching donations in high-income years, donating appreciated assets, and coordinating with your tax advisor can turn philanthropy into a serious creative lever that quietly improves your after-tax net worth.
Turning Ideas into Action – Your 90-Day Roadmap
Most idea lists stop at “what.” Here’s the “how”:
Days 1–30 – Assessment: Inventory holdings, decide your creative allocation (10–20%), and pick 2–3 themes that fit your goals.
Days 31–60 – Due Diligence: Research funds, fees, liquidity, and governance. Set up bookkeeping categories. For help organizing, see our piece on how to streamline your investment portfolio.
Days 61–90 – Execution: Invest in small, diversified positions. Set quarterly reviews. Adjust by metrics, not headlines.
Conclusion – How I Approach Creative Investing With My Clients
After two decades helping business owners keep their books honest and their portfolios growing, I’ve learned that creative investment ideas work best when paired with old-fashioned discipline. The five ideas here—alternatives, impact themes, arts and entertainment, digital and IP assets, and philanthropic structures—can each strengthen your portfolio when sized correctly, tracked clearly, and aligned with your goals.
Pick a percentage, pick two or three ideas that fit your real life, and build a system that lets you see everything in one place. When you’re ready for a partner to help structure and track it all, visit Complete Controller and let our team support your next move with confidence.
Frequently Asked Questions About Creative Investment Ideas
What are some unique investment ideas?
Unique investment ideas include alternative assets like infrastructure and commodities, ESG-themed funds, creative industry startups, digital content and royalty streams, and donor-advised funds that improve tax efficiency while supporting causes you care about.
What is the most creative investment?
The most creative investment depends on your goals, but many investors find creator-economy ventures, arts and entertainment, and digital IP (courses, memberships, royalties) the most innovative—especially when they combine scalable income with long-term asset value.
What are some unconventional investment options?
Unconventional options include private credit, renewable energy projects, niche real assets, revenue-sharing deals in online businesses, music or film royalties, and donor-advised funds that integrate tax planning with impact.
How can beginners start with creative investments?
Beginners should start with small allocations to thematic ETFs (AI, energy transition, ESG), simple income streams like online courses, and low-complexity impact funds, while keeping the majority of their portfolio in diversified core investments.
Are creative investment ideas high risk?
Creative investments often carry higher or different risks—illiquidity, business failure, regulatory shifts—but those risks can be managed through position sizing, diversification, professional due diligence, and disciplined bookkeeping and reporting.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Jennifer BrazerFounder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.
Every financially responsible adult should have multiple savings accounts, the most important of which should be an emergency fund. This fund is used to cover emergencies that are unforeseen and not built into your budget. It should cover catastrophes such as a costly car or home repair not covered by warranties or an unexpected healthcare expense.
The emergency fund savings is not to be confused with saving for your future or a family vacation, down payment on a new car or home, or a wedding. It is an account protected to cover you and prevent those unforeseen disasters from causing you financial hardship or devastation. Here are three important things to consider when saving for an emergency fund.
Use a Financial Advisor
While hiring a professional financial advisor is expensive, it is a financially smart thing to do, especially if you are not good with your finances. Many smart and savvy adults who are good at their jobs and have talents in other areas are not good with money. Commonly, most working adults carry a little to a far greater amount of debt brought about by the mishandling of their money.
The cost of hiring a financial advisor will easily be defrayed by the amount of savings having a professional help you straighten out your finances will gain you. These financial experts know how to help you identify where you can make changes and create savings accounts for your future and for emergencies.
Most people hesitate to use a financial advisor because of the cost, but because they are embarrassed by their financial situation and laying it open in front of a virtual stranger can be challenging. If you can put these concerns aside and understand these professionals have seen it all and know how to get you on the right financial path, you will not regret your decision. Not only will they help you get a much-needed emergency fund in place quickly, but they can help you with every aspect of your finances, leading you to financial freedom.
The Amount of Your Emergency Fund
Most people ask when contemplating an emergency fund is how much should the fund contain? If you are a novice at saving, the answer is that you should start small and save an amount of $1,000 as quickly as possible. These savings will easily cover small issues such as a car or home repairs or other similar issues.
Once you have the $1,000 emergency nest egg, it is time to build that savings to cover bigger issues such as job loss or medical issues that could cause longer-term income loss. Most experts will recommend this amount be equal to at least six months of your income. Doing this will ensure you are covered if there are hindrances to employment for a prolonged period.
Once you have six months of your income saved, it is suggested that you continue to build towards a year. Keep in mind these savings is never to be touched for anything other than an emergency or financial hardships. You should still have other savings to include those for specific large purchases or vacations and those specifically towards your retirement funds. But before you contribute to any of those other savings accounts, you should use all your savings efforts to build your emergency fund.
Where to Keep Your Emergency Fund
There are several places you could keep your emergency fund, but some definite rules you want to follow to make sure your emergency funds are kept in the right place(s).
Before deciding where to keep the funds that work best for you, there is one rule to follow, no matter where you choose to keep this fund. Ensure it is accessiblewithout penalties or days of red tape to obtain. After all, it has emergency right in the name, implying you will need it right away. However, don’t make it so accessible that you will be tempted to use it for non-emergency purchases. Restrain yourself from “borrowing” from this fund for non-emergency desires of your heart.
One of the safest places to keep your emergency funds while also fitting the previously describe rule of thumb is in an online bank. Banks that are completely housed and operated online make electronic transactions easy while also being an account not attached to your traditional bank account, making accessing it more tempting.
Another great account that will not be attached to your traditional bank account is a money market account. This type of account is not only a standalone account, but it can gain your interest while your money is sitting in reserve, waiting for an emergency. Savings accounts that gain interest are never bad, especially when you are trying to build this emergency account to equal a year’s income.
Conclusion
Keeping these three important aspects of an emergency fund in mind when considering building this savings account will ensure you have coverage in your times of financial need. Having this fund will not only provide you with peace of mind when an emergency arises, but it will provide you with it knowing it’s there if you should ever need it.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Time management is probably one of the things every employee who works from home would agree they have issues with when it comes to accomplishing daily workloads. Even in an office environment, time management is a difficulty for many employees. While in some cases, the issue is that people bite off more than they can chew and commit to more than can be done in the time allotted. In many cases, the issue is poor time management. Here are seven things you can do to improve time management and meet your goals and the goals of your superiors.
Plan Ahead
Planning is the best way to lay out what you need to do and what you need to accomplish the task or tasks at hand. If you have everything you need in place and do some planning and preparations, it will save time when you get into the work. You can use a calendar, planner, or make lists somewhere you will often see to help you keep on schedule and task. If you’re smart, you can even build in padding to accommodate the inevitable wrenches that get thrown in. If you plan for unforeseen issues, you will still accomplish what you need to for the day.
Group Related Tasks
Grouping together related tasks will make your workflow make sense. For example, if you need to read over documents and print other documents, you should group these tasks because you will already be in your documents folder. The grouping of related tasks should take place in the planning of your day. If you have new tasks assigned during the day, unless you are told it has to be done right away, you can add the task to another task or group where it makes sense.
Prioritize
Prioritizing should be in the planning stage also. However, once you start working or begin your day, the priorities may shift. So though you can pre-plan your priorities, you have to be flexible to change the plan if something needs your attention sooner. You need to make your priorities clear to your co-workers and superior, so they know not even to approach you if what they need from you is not as important as you already prioritized behind what you have planned.
Unless you have something pressing, you should always prioritize the tasks you dislike or that are difficult or the most time consuming first. Getting those out of the way will lessen the chances that you will procrastinate them or have to work past the end of the day to finish them.
Make a Mental Narrative
This might sound a little crazy since it is about to be suggested that you talk to yourself, but if you layout your day and priorities out loud in the form of a story, you can make adjustments when something is not working. This type of mental preparation is like brainstorming with yourself and works well. It is similar to the difference between reading something in your head and reading it out loud. You will notice that you comprehend information quicker when you read it out loud.
Keep the Drive Going
Even if you lose your juice in the middle of a task, unless it is one that will take several hours or days, keep pushing yourself through because when you stop, it is often hard to restart. This can be especially true for tasks you don’ like or that are far more challenging. That being said, if you need a break and not having one is hindering your progress mentally or physically, take a break, but make it quick.
Use a Timer
If one of your issues is accomplishingtaskspromptly, use a timer. If you know how long it takes or should take to finish a task, set your timer for that time. The ticking clock will push you to keep going, and also, if you are consistently blowing past the buzzer to finish tasks, you may need to reassess the tasks or time it takes. Using a timer is meant to be a tool to help you stay on task, so don’t let it add stress. It is just a guideline.
Single-Tasking
While you may think that time management gurus will suggest multi-task, nothing could be further from the truth. Most experts believe that multi-tasking, in reality, is not a possibility in many cases. It is possible to multi-task things like brushing your teeth and blowdrying your hair, but you can’t take a shower and blowdry your hair. You also can’t do something like read the newspaper and talk on the phone, one of those two tasks or both will suffer. Now time management experts suggest you give everything you have and focus on a single task until it is completed. It has been discovered the quality and speed of the work were far superior to that of the employee that was multi-tasking.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.






 About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.