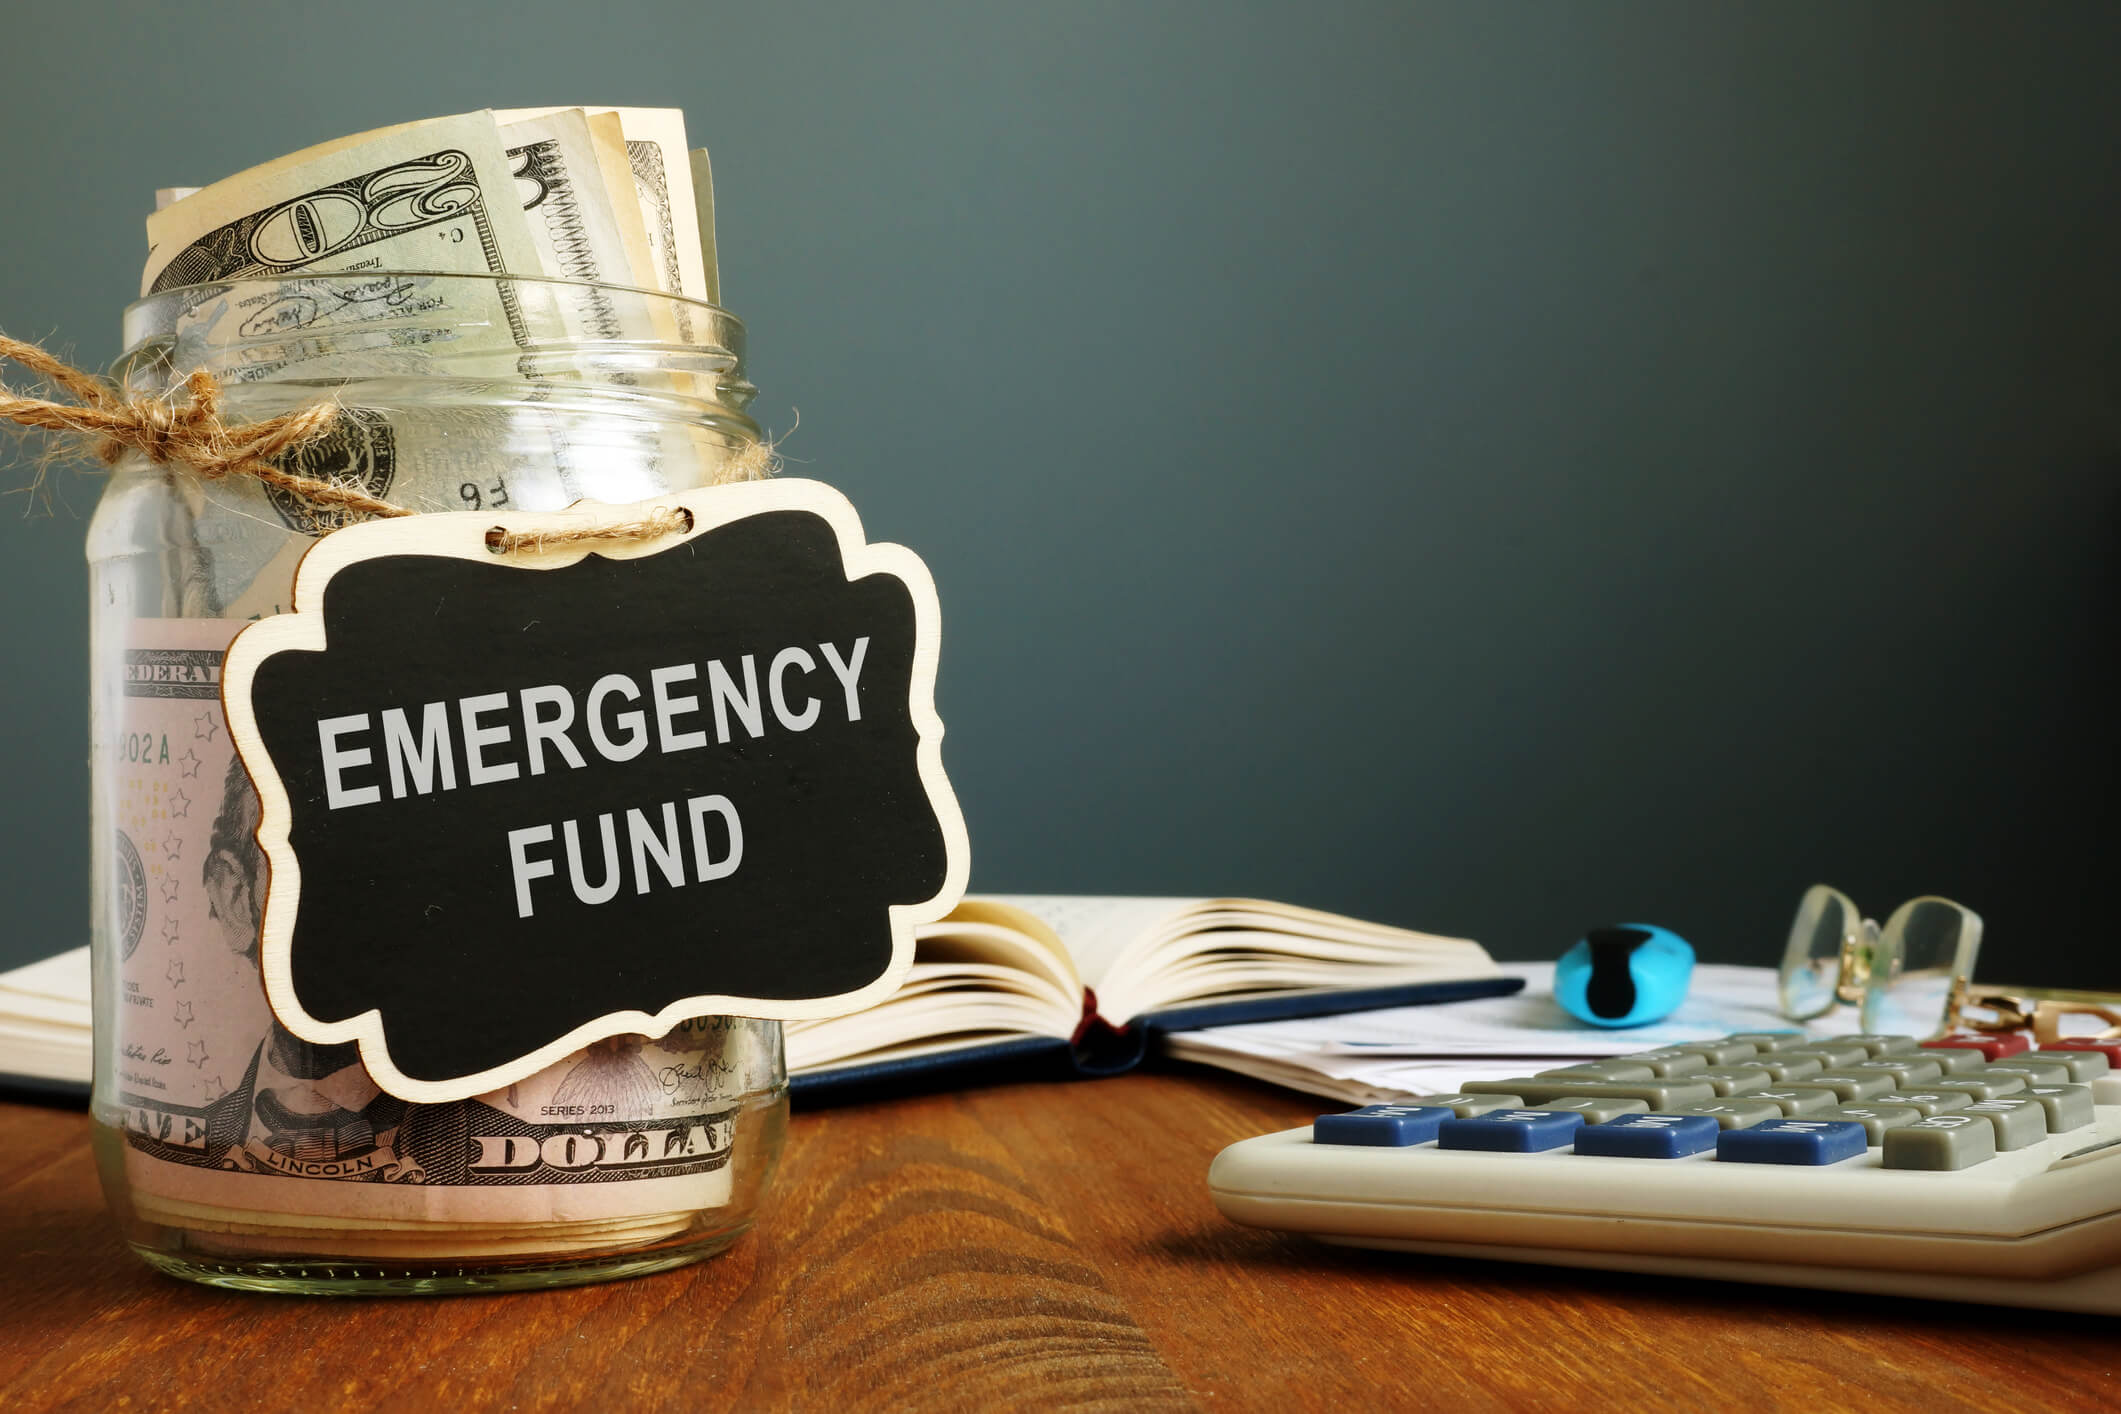
As a starting point, it should be an amount that you feel comfortable and secure with. From there, there is a minimum recommendation for the emergency fund that goes from 3 to six months of your fixed expenses. In case of doubt, it will always be better to stay in the high range of the calculation.
To calculate your contingency cushion and generate a good emergency fund, the first thing will be to write down your essential fixedexpenses. This may be a good time to reflect on how and on what you are spending the money and implement the envelope method to save that we explain in the following video.
Once you have calculated the fixed costs you have and expect to keep, you only have to multiply them by six. This way you will know how much you need an emergency fund that helps you to have a finance approves of bombs,
How long will it take to collect your reserve fund?
It is normal, to generate the savings you want take some time. If you need to know how much to set a temporary goal for, the calculation is easy. You only have to divide the money in the fund between the amounts you save each month.
As an example, let’s make numbers. Let’s imagine that you have an income of $1,000 per month and fixed non-renounceable expenses of $800. In this case, the amount of the emergency fund will be $4,800.
Let’s say you start saving 5% of your income or $50 a month. It will take 96 months to get the capital together. If you raise the rate to 10%, it will only take 48 months.
Where do I put the emergency money?
It’s easy for your first response at this point to be under the mattress. Avoid this temptation if you want to save automatically. It is better to have the emergency fund in an account or other financial products that, in addition, will help you avoid the temptation to use it unless it is necessary.
When placing that money do not lose sight of the three blocks of financial planning to those we linked before. In addition, the place where you leave that money must meet two specific conditions:
Or as it is known in financial terms, liquidity. In other words, to be able to access money easily and almost immediately.
Do not play with your emergency fund. Bet on risk-free products where you know you will not lose money.
One of the most common errors at this point is making the emergency fund profitable. In other words, seek to obtain a benefit for that money. Remember what your main goal for that emergency mattress is: that it is always available in a safe place because you may need it at any time.
In this sense, a remunerated account or a renewable short-term deposit will automatically be the best options.
And the profitability? To look for profitability and grow your money you already have the rest of your savings, as we will see below.
What to do when you have already created the emergency fund?
Keep pre-saving! The contingency fund for contingencies is only the first step towards financial freedom, the minimum safety net you need. Now that you have started saving, it will be easier to continue than to stop. If you lack motivation, what do you think about achieving a golden retirement or taking a sabbatical as objectives?
When to use the emergency fund?
When you really need it, when it really is an emergency and an undertaking. As an example, if the car breaks down you can go to it, as well as if the washing machine is broken. However, you should not do it if you know that you are going to change the car in a year or that you will shortly have to renew the appliances. That kind of expense, you can budget and you should do it.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing services to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks file, critical financial documents and back office tools in an efficient and secure environment. Complete Controller’s team of US based accounting professionals are certified QuickBooks™️ ProAdvisor’s providing bookkeeping, record storage, performance reporting and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay services. With flat rate service plans, Complete Controller is the most cost effective expert accounting solution for business, family office, trusts, and households of any size or complexity.
There is often a question raised between country and city, which one offers a cheaper yet better lifestyle. Here are some facts that will make it clear to comprehend.
Working opportunities:
Being in the city, it is much easier to find a work of one’s own choice. There are a lot of opportunities for even the tiniest skills one has. Yet, if there are more offers, there is more competition too. A lot of people are striving to fill the only job vacancy in a famous company in the city. However, there are lesser jobs in countries, but even if one gets the offers, the competition is less and it is much easier to grab the one and only job offered in a month or two.
Transport Abilities:
In countries, one has to walk through a mile with no chance of public transport around. However, in cities, anyone can get a bus after 15 minutes of losing one. In countries, the extra charges for a car have to be borne. Buying a car is not a hard thing to do, yet maintaining a car is not easy. Giving extra taxes for the car and paying for the fuel is much expensive than getting to the bus stop in five minutes from the apartment. Hence, cities are better for providing the transportation facilities.
Houses:
For renting a single story house with two rooms in a city, it is provoking for someone to pay $400. With that, it is much easier to rent a two story house in a village with better facilities for $300. Where one has the space for the pet, an extra yard for planting the orchards and much more. So, country beats the city when it comes to housing.
Incautious shopping:
In the city, even passing by the mall for window shopping and having money in hands, no one would really pass by a beautiful affordable dress for her or a decent watch in a relatively less price for him. Yet, forcefully, one will have to buy that for satisfying their wants, no matter if they will have to suffer the last week of the month with no money. However, in countries, no markets nearby, no incautious shopping! In countries, people have to go far off places to buy the ration for the house even in a month. So, there will be no passing by the mall, no attractive things to worry about, and hence, savings.
Festivals:
In cities, even extra sales for the city population means extra expenditure. Even in sales, expenses are much more. While in countries, festivals are held on a regular basis. These festivals are about different items on different occasions. Yet, they have a little less good quality, still, they are a better option for saving a $100 in just a single festival rather than paying an extra $100 for sales.
Must expense for Having a House in the City:
Having a house in a city is expensive, but maintaining the house requires much more expenditures. One has to pay for the trash collection, rapid transit or animal control. One has to pay the extra water bills, electricity’s extra usage will cause them to pay extra bills and there are much more to go. In countries, there are no such expenses. One has to do most of the work on their own. There are no special orders for keeping animals or cattle. One can have a cow for milk, for cheese and also one can earn by such means.
Schools:
In cities, getting an education is much more expensive. Paying extra charges for useless activities is not really comforting. Kids are provided with good education, but the same education can be provided to the kids in countries with lesser expenditures. One has to pay for transport as the schools are far off in cities. Yet, in countries, the schools are present nearby and have just as much extracurricular activities as required.
Of the above-mentioned factors, it is clear that city life has advantages related to the career, but when it comes to expenses, country life is more reasonable.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing services to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks file, critical financial documents and back office tools in an efficient and secure environment. Complete Controller’s team of US based accounting professionals are certified QuickBooks™️ ProAdvisor’s providing bookkeeping, record storage, performance reporting and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay services. With flat rate service plans, Complete Controller is the most cost effective expert accounting solution for business, family office, trusts, and households of any size or complexity.
Why spend 12 or 14 hours at work when we can perform the same tasks in 7 or 8 hours? The unnecessary distractions reduce our ability to concentrate, make us less productive and force us to spend more time at the computer.
Do not check emails so often
It is not the first time that we say that email is the first and most important source of distractions that you have to deal with during your working day, but we have no choice but to insist on it.
At this point, it is worth mentioning a recent study developed by the University of Glasgow in which it is clear that many of the less productive workers tend to control their email up to 40 times per hour when it is reasonable to do it only three times up to date.
Forget about the phone
Sometimes, when we really need to maintain concentration at the highest level, we can opt directly to forget about the phone.
It is not about turning it off completely, but for example, we can restrict incoming calls except for certain numbers, activate the vibration mode, or directly leave it in another room, and then check the calls we received after a few hours.
Defend your workspace
For many, this can simply translate into closing the door of their office. However, when we work in open spaces (we do not have our own office) this defense must be done from the mental plane. A good solution is to use, for example, two different browsers.
The first one will only be used to perform tasks that are directly related to our work. We will open the second when we want to take a break, and spend a few minutes of disconnection. If our operating system allows it, we can also configure different “workspaces” for each of the areas we need.
Order your workspace
A messy table, not knowing where the objects we need are, a large number of unorganized papers are signs of a space that works against us. The goal of an orderly workspace is not that everything “looks nicer” but that we are more productive, and have more capacity to carry out tasks to fruition.
If every time we have to look for a document, we lose five minutes, can you imagine how much useless time we have let through the day?
Uses helmets
Some people need to isolate themselves from the world to be more focused. A good way is to use helmets, putting soft music that does not distract us. The idea is to use classical, jazz, or ambient music.
Music with lyrics is convenient, as we will easily lose concentration, spending more time thinking about the lyrics and the memories that remind us of our work. Some people choose to wear helmets without any music so that others have to think twice before interrupting them.
Everything you need has to be at hand
Before starting a task, make sure everything you need is at hand. Do you have all the necessary information/documentation? What programs are you going to use? Are you going to have to contact someone? In short, before starting your working day, it is no good that you do a little planning of everything you need.
Change your work schedule
If working on your own, or your job allows you to have a flexible work schedule, adapt it to your needs. The good idea is to start working early, to be able to leave early. If you start working at 7 a.m. for example, you will have two hours in which you will practically be “alone before the world” without interruptions of any kind. In this way, you can, for example, leave at 5:00 p.m. and better reconcile your work and family life.
If you work in your home, identify which is the schedule that best suits your work performance. Some people prefer to work at night, while others, as we have indicated before, need to get up very early to be able to perform at their best.
Resolve any questions before starting
Before starting to work on any project, you must have a very clear idea of what you have to do. It is not enough to have a vague idea of what is going to be required. Therefore, all the doubts, questions and questions that you need to clarify are better resolved before starting work.
It is true that during the course of your task new doubts may arise, but a specific doubt is not the same as being immersed in a sea of questions, which we will end up unsolved by shame to ask again.
Disconnect from the Internet
After email, the Internet is the biggest source of distractions that you can find in your work environment. Browse, visit social networks, check your Twitter account, read the latest news or review your feeds is stealing time from what really matters: finish your work and have more free time.
If you are before a project or a task that you can solve without using the Internet, do not think twice: pull the thread and disconnect from the Network. Doing so you will be ending a great source of distractions.
Take a break before losing Concentration
It is unavoidable. After a while working, our mind starts to escape, to think about things much more pleasant and gradually, we lose concentration, until there is a point where we really do not know what we are working on.
When we identify these moments, the best solution is not to insist on continuing to work. It is much more productive to stop working and take five minutes to disconnect. We can take a walk, have a tea or simply perform an exercise and breathing. In this way, in a few minutes, we will be ready to start again.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing services to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks file, critical financial documents and back office tools in an efficient and secure environment. Complete Controller’s team of US based accounting professionals are certified QuickBooks™️ ProAdvisor’s providing bookkeeping, record storage, performance reporting and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay services. With flat rate service plans, Complete Controller is the most cost effective expert accounting solution for business, family office, trusts, and households of any size or complexity.
If you want to become an owner, it is time to get aware of things around you. But be careful, when negotiating with your banker, do not focus on this single nominal rate, because the true cost of your credit will depend on the total effective rate. The latter includes all the costs of setting up your loan, use a magnifying glass to figure out things. Because they can allow you to realize substantial savings.
Lower the administrative costs
When you go to your bank advisor, he will do different simulations depending on your profile. If you are a simple customer (employee, having all your accounts domiciled at his agency, no health risk aggravated), your file will be very easy to assemble. In this case, negotiate with him a discount on the expenses of the file. If you go through a broker, the fees will have to be paid, but you will have nothing to settle at the bank. Again, negotiate a rebate if your record has required very few appointments.
Negotiate the cost of insurance
When you buy a home loan, you must at the same time take DIIT insurance (Death, Invalidity, Incapacity of Work). It allows the banker to ensure that the monthly payments will always be paid even if you are a victim of a serious disaster. You can take out a contract that is cheaper than your banks, but only if the insurance policy on assignment gives you identical guarantees.
Play on the ancillary services
You cannot bend your banker and still want to get better. Play on the ancillary services. Your advisor will be pleased to make you subscribe, in parallel to your home loan, home multi-risk insurance for your new home. In the same way, show your banker that you are ready to place your sponge in his establishment by looking at basic savings products. If your bank offers a bundle of interesting services with the bank card, inform your banker that you are interested. As you get benefits from a commercial gesture on your home loan!
Check the prepayment penalties
If you have to sell your home to another area or to buy bigger or smaller, you will need to prepay the bank. Legally, the latter amount to 3% of the remaining capital, capped at six months of interest, responsible for relations with banks. It is possible to cancel or reduce the amount if you resell your home for the purchase of another. Remember to change this point in your loan agreement before signing it; this may be useful in the future. Be aware, however, that a banker will charge you almost systematically if you renegotiate your mortgage in a competitor.
Think about the transferability of the loan
Check that your credit is transferable. This will save you money in the future by taking advantage of current rates of less than 3% on future purchases. If you buy a larger home in a few years, after reselling the first one to which your credit is attached, this mechanism will allow you to transfer the remainder of your credit for the purchase of the new property. So, you have to borrow the missing complement, at a rate probably higher than 3%. Attention, this operation remains however at the good will of the bank. But check that it is possible upstream, before signing the loan offer.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing services to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks file, critical financial documents and back office tools in an efficient and secure environment. Complete Controller’s team of US based accounting professionals are certified QuickBooks™️ ProAdvisor’s providing bookkeeping, record storage, performance reporting and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay services. With flat rate service plans, Complete Controller is the most cost effective expert accounting solution for business, family office, trusts, and households of any size or complexity.
Restaurants, unlike other business models, have to adapt to the competition of concepts in a fluid and exhaustive way. Opening a restaurant or expanding a concept requires thinking something out of the ordinary, having extensive experience in the business and or getting a redistribution or capital increase. Restaurant owners can get money for the initial investment, for working capital or to expand capital from three primary sources: loans for small businesses or ventures, banks or credit unions, and investment groups.
What kind of restaurant financing is out there?
For a person who wants to start a new business, there are many different types of business loans obtainable for people who wants to finance a restaurant. In addition, when it comes down to it, the kind of restaurant financing a person gets actually will depend on the type of business lenders they are working or choose to work with. Keeping that in mind, here are the four basic types of restaurant financing options that a person can use for their business:
Loans for small businesses
The Small Business Office has programs for businesses that seek capital through approved “micro-lenders”. This US office, for example, provides financial support through micro-credits ranging from $2,500 to a maximum of $35,000, and an average of $13,000. These micro-credits generally have competitive interest rates and provide restaurants and other businesses with not only financial assistance, but also planning and marketing strategies, along with other resources for business management and training. The requirements to obtain one of these loans include a business profile (business history, operations plans, and managers), curricula of current owners and managers.
Private loans
Private loans can be obtained through banks or credit unions. By federal law, banks can grant larger loans than credit unions, which are restricted in the amounts to be lent. To secure these loans you will need guarantees, which vary from 10 percent to 25 percent of the value of the loan.
Analyze the figures
Whether you are just starting your business or you are already generating some profit, quantify the performance of your business and set performance goals is a good idea. Make sure you identify how much cash your company needs during the next 12 months. Finally, make sure you have software systems to track the performance of your business.
Investment group
Restaurants are the perfect investment for investment groups. The level of service, cuisine and the subject (called concept) have to demonstrate the capacity of the business to generate profits and endure over time. Some investment groups only provide financing if certain directives are followed in the administration of the business, and may even require that a member of the group work or be a manager in the restaurant, to ensure the proper use of funds and growth of the business.
Make plans for the future
For a person who wants to start a new business, there are many different types of business loans obtainable for people who wants to finance a restaurant. Make sure you prepare properly before asking for a loan from your bank. This will make it cheaper for you. CHEAPER! The future of your company may depend on your ability to access cheaper sources of capital. Therefore, you must be well prepared and informed: the last thing you want is for your competitors to be before you!
Working Capital Loans
An operational capital loan is one of the most feasible options for a restaurant owner who want to shelter their owed business expenditures. Such loans are not expected to buy long-term possessions, but it is just a short-term option to cover temporary needs.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing services to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks file, critical financial documents and back office tools in an efficient and secure environment. Complete Controller’s team of US based accounting professionals are certified QuickBooks™️ ProAdvisor’s providing bookkeeping, record storage, performance reporting and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay services. With flat rate service plans, Complete Controller is the most cost effective expert accounting solution for business, family office, trusts, and households of any size or complexity.
If making the money last until the end of the month is already a big battle, imagine getting it so you can achieve some dreams! Want to buy a new car, get out of the rental or make that vacation trip without worrying about expenses? Well, know that it is possible, provided you have organization and discipline with your household budget.
Incidentally, it is worth telling you what budget is the money available to pay the bills. But that does not mean it has to be all the money you get, you see? You can allocate a portion of this income to other investments, being prepared for any emergency.
Identify the expenses
You know by heart how much you make over the course of the month, right? But how much do you spend? Do you know exactly how you use your income? Identifying what your expenses are should be the first measure to put the household budget up to date.
Start with the most obvious ones, such as energy, water, rent, and provision of the car. Then move on to the less notable ones, like the coffee from the bakery you get every morning, or the biweekly magazine you buy or take out with your friends on weekends. Whatever your routine, it is important to identify each expense.
Categorize your expenses
After finishing the expense list, group them into larger categories so you can see where your money is going. You can have categories called, for example, from:
Household expenses;
Food – for meals made outside the home;
Fuel;
Superfluous expenses.
Find out what are the fixed expenses, the ones you have every month, and the variable expenses, like the credit card bill, for example. In general, the variables are the ones that most consume your budget, because they are concentrated in the unnecessary expenses. But that does not mean you can not save on fixed expenses too, okay? We’ll talk about this later.
Start to control
The financial lack of control happens precisely because the tendency is to think that it is possible to keep everything organized only in memory. However, do a quick exercise now: look at the past week and try to think about how you spent your money. Harder than you’d imagined, right? So the best thing to do is choose a method of control.
You can do a manual control, in a notebook, writing down all your daily expenses. The only problem, in this case, is that relying on memory and committing to write it down every day can be a bit risky. After all, you certainly have other things to do. So how to solve?
A fairly viable alternative is to use spreadsheets to shed revenues and expenses. With them, you can create formulas and get balances, sums, and other results that will help you more easily identify your expenses through consumption charts, for example.
There is also the possibility of using an application to control the domestic budget. Nowadays, several companies offer services (both free and paid) for this purpose, with apps that can be accessed by the computer or the smartphone. And the best is that you can update your control in real time, reducing the chances of forgetting some release!
Involve the whole family
Are you really willing to start controlling your spending? Great! Only with this, a very important step has already been overcome. However, if your family does not enter into the same vibration, your whole disposition may not prevail. In this phase of control, therefore, it is necessary to involve the whole house!
Hold periodic family gatherings and seek the engagement of everyone. It is important that they participate in choosing the form of control and identification of expenses. It is also good that everyone has access to control, to follow their progress whenever they want. The key is to treat the subject with enthusiasm, making them understand that it is a good practice and not an obligation, a tactic that will lead to the achievement of important dreams and the achievement of a better quality of life.
Design your cash flow
The cash flow is nothing more than the control of the monthly receipts and exits, serving as a thermometer to know how many times you use your bank account. Based on fixed and variable expenses, you can predict how much you will spend month to month, as well as how much money you have to pay the bills.
If you still cannot save, you’ll know at least when you’ll be able to start, because cash flow signals leftover budget. From there, you can think about the dreams to be made and the planning for it!
Have financial goals
Goals are the reflection of your desire to organize and control the domestic budget more efficiently. They will help you identify where you can reduce spending and thus generate a greater capital accumulation so that you can pursue your goals.
Set collective goals as well
Since we are talking about involving the whole house, the family must also participate in this stage. Some people, especially children and adolescents, tend to feel distant from the practice of planning. And this can make your decisions take the opposite course of other family goals.
To engage everyone, therefore, make the family see itself as a team. All together should thus help reduce the bills of the house! In this scenario, when one fails, the other can help to remember. In this way, everyone absorbs healthy financial habits, taking this learning through life.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing services to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks file, critical financial documents and back office tools in an efficient and secure environment. Complete Controller’s team of US based accounting professionals are certified QuickBooks™️ ProAdvisor’s providing bookkeeping, record storage, performance reporting and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay services. With flat rate service plans, Complete Controller is the most cost effective expert accounting solution for business, family office, trusts, and households of any size or complexity.
The most common credit card problems—high APR, late fees, billing errors, fraud, and credit score damage—can all be fixed and prevented by lowering your interest costs, paying on time, disputing errors quickly, tightening fraud controls, and managing your utilization strategically. Each of these issues has a clear playbook, and once you treat them as systems problems rather than personal failures, you can stop reacting to credit card stress and start running the show.
In over 20 years of building Complete Controller and working alongside business owners across nearly every industry imaginable, I’ve seen credit card chaos derail more growth plans than almost any other financial habit. The good news? The fixes are surprisingly repeatable. In this article, I’ll share the exact moves I recommend to clients to lower interest costs, fight back against fees and fraud, repair billing and reporting errors, and protect your credit score for the long haul—so your cards work for you instead of against you.
What Aare the most common credit card problems and how do you fix them?
High APR, late fees, billing errors, fraud, and credit score damage are the main common credit card problems, and each has a targeted fix and a prevention habit that goes with it.
High APR is managed by paying in full when possible, negotiating your rate, and using credit card balance transfers strategically.
Credit card late payments and over limit fees are avoided with autopay, reminders, and tighter utilization.
Billing errors and credit bureau reporting errors are corrected by monitoring statements and disputing in writing with your issuer and the bureaus.
Fraud and declined transactions are reduced through alerts, strong authentication, and immediate reporting.
Score damage is prevented by keeping utilization low and spacing out new applications.
Understanding Common Credit Card Problems Before They Spiral
Credit cards become a problem when short-term convenience quietly turns into long-term debt, hidden costs, or silent credit damage. Most people don’t recognize the warning signs—rising minimums, frequent declines, or a sudden score drop—until they’ve already lost their negotiating power.
Why small credit card payment issues matter more than you think
From a bookkeeping lens, the first symptom is usually a cash flow mismatch: due dates don’t line up with income, and the card morphs into an expensive short-term loan.
A single missed due date can trigger penalty APRs, late fees, and a 30-day late mark that stays on your report for years.
A pattern of reversed payments—like a credit card payment reversed by bank for insufficient funds—signals risk to lenders, pushing APRs up and limits down.
Issuers track behavior closely, so even minor stumbles can change your terms over time.
High APR and Costly Interest
High APR is one of the most financially damaging common credit card problems because it silently inflates every purchase you carry. According to the Federal Reserve, the average APR on credit card accounts assessed interest hit 22.80% in May 2025, a sharp jump from pre-2020 levels (Federal Reserve G.19 report).
Why your credit card interest rate is high
Issuers price your rate based on your credit score, utilization, and broader market conditions. Penalty APRs from late payments make existing balances even more expensive. Many people assume rates are fixed—they’re not.
Stop adding new charges to high-interest cards while you pay them down.
Pay more than the minimum—covering only the minimum can keep you in debt for years.
Target your highest APR first (the avalanche method) while keeping other cards current.
How to fix high credit card interest rate, step by step
Inventory all your APRs and balances.
Improve your profile by paying on time and dropping utilization below 30%.
Call your issuer with data—reference your payment history and competing offers.
Use credit card balance transfers wisely, with a payoff plan before the promo APR expires.
Late Fees, Over-Limit Charges, and Missed Payments
Late payments and over-limit charges are among the most visible common credit card problems, hitting you with fees immediately and damaging credit over time.
Credit card late payments and the minimum payment not working trap
When the minimum payment barely covers interest, your balance hardly moves—and sometimes even grows. That’s the trap.
Credit card late payments generate fees, trigger penalty APRs, and cause negative marks if you’re 30+ days past due.
Over limit fees can occur when balances exceed your credit line, and high utilization hurts your score even without a fee.
Good news: the CFPB’s 2024 final rule caps most late fees at $8 for many large issuers—down from typical fees around $30+—and ends automatic inflation increases (CFPB announcement).
What to do after a credit card late payment
If it’s your first slip, call and ask for the fee to be waived—issuers often accommodate occasional misses. Bring the account current fast to dodge a 30-day late mark, and request a penalty APR review after a stretch of on-time payments.
To prevent repeats, set autopay for at least the minimum on every card, then add manual payments when cash flow allows. Align due dates with paydays to cut down on credit card payment processing errors and NSF reversals.
Better bookkeeping leads to better financial decisions. Discover how Complete Controller helps you build stronger financial habits.
Billing Errors, Processing Glitches, and Credit Bureau Reporting Errors
Behind most unexplained balance jumps or score drops are billing or reporting issues—often overlooked common credit card problems.
Credit card payment processing errors and authorization problems
Processing errors include double charges, missing payments, or misapplied credits. Credit card authorization problems show up as declines despite available credit—often from fraud flags, outages, or mismatched info.
Review every statement line by line to catch anomalies early.
For errors, contact the issuer immediately and follow up in writing.
If declines repeat, ask your issuer about fraud flags, regional blocks, or merchant restrictions.
Fixing credit bureau reporting errors
Credit bureau reporting errors include accounts that aren’t yours, duplicate negatives, wrong limits, or late payments reported in error. These drop your score and lead to higher APRs or denials.
Pull reports from all three major bureaus and compare against your statements.
Dispute inaccuracies with both the creditor and bureaus in writing, with evidence attached.
Fraud, Declined Transactions, and Verification Headaches
Fraud and declines are emotionally stressful common credit card problems that can derail travel, online purchases, and recurring bills.
Credit card declined due to verification and online purchase issues
Fraud involves stolen cards, skimmed numbers, or account takeover. A credit card declined due to verification usually means the issuer can’t confirm your identity or spotted unusual activity. A credit card declined for online purchase often traces back to mismatched billing addresses or outdated card details.
Turn on transaction alerts via SMS or email.
Avoid using cards on insecure sites or public Wi-Fi—never share your CVV or OTP.
Report lost or stolen cards immediately. Under the Fair Credit Billing Act, your maximum liability for unauthorized credit card use is $50, and many issuers offer $0 liability as policy (FTC guidance).
Handling credit card declined transactions in real time
Try a small test charge, verify your billing details, and call your issuer from a trusted line. Notify your bank before travel, and keep a backup payment method for critical purchases. For business-level protection strategies, check out Complete Controller’s resource on fraud detection and prevention.
Credit Score Drops from Card Misuse
One of the most underestimated common credit card problems is the slow erosion of your credit score through everyday habits—high balances or too many new applications.
How late payments, utilization, and applications damage your score
One 30-day late payment can drop your score significantly.
High utilization signals risk and pulls your score down, even with perfect payment history.
Multiple applications in a short window stack hard inquiries and can read as financial distress.
Score protection habits:
Keep utilization below 30%—20% or less is ideal.
Space new applications several months apart.
Keep older accounts open when possible to preserve account age.
Bringing It All Together
When you put it all together, preventing common credit card problems comes down to three pillars: awareness (monitoring statements and credit reports), systems (autopay, reminders, spending plans), and proactive communication (negotiating terms and disputing errors promptly).
After reviewing thousands of client financials, I can tell you the biggest difference between people who stay stuck and those who break free isn’t income—it’s whether they treat credit card use as a managed system instead of a series of one-off emergencies. If you’re ready to build that system, my team at Complete Controller can help you put the controls and reporting in place. Visit Complete Controller to learn how we can support you.
Frequently Asked Questions About Common Credit Card Problems
What are the most common credit card problems?
The most common are high APR, carrying a balance, late payments, exceeding your credit limit, billing errors, fraud, and behaviors that damage your credit score.
How can I avoid credit card interest charges?
Pay your statement balance in full by the due date. If you can’t, pay more than the minimum and tackle higher APR balances first.
How can I stop my credit card from being declined?
Keep your info updated, notify your issuer about travel, maintain available credit, and respond to verification requests quickly.
How do I correct a mistake on my credit card bill?
Contact your issuer fast, provide documentation, and follow up in writing if needed. Review statements monthly to catch errors early.
How do I repair my credit after credit card problems?
Pay on time, lower utilization, avoid unnecessary new accounts, and dispute any credit bureau reporting errors that unfairly hurt your score.
Sources
Airtel. “6 Common Credit Card Problems & How to Fix Them.” Airtel Blog.
Bankrate. “What’s a Good APR for a Credit Card?” Bankrate.
Georgia Student Finance Commission. “Dangers of Credit Cards.” GAfutures.
Navy Federal Credit Union. “Why Is My Credit Card APR So High?” MakingCents.
Yahoo Finance. “10 Common Credit Card Complaints.”
Consolidated Credit. “8 Ways to Combat High APR Problems.”
AMG Loan Company. “The Best Ways to Lower Interest Rates on Credit Card Debt.”
ATFCU. “How to Reduce Credit Card Interest Rates.”
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Jennifer BrazerFounder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.
Are you lost in the midst of so many complaints from your customers and do not know what to do? Take a deep breath and read these tips we prepared to help you.
Reread the briefing
For those who do not know what we are talking about, a briefing is a kind of profile of your client. It is made with care and a lot of studies and is an element to help you produce an article for a specific company.
In case your text is rejected, one of the possible reasons for that is that it is not correctly aligned to the client’s profile. Read the available information and look at:
Company data
Know the organization you are working for! Find out what your goals are with the blog, how many years it has been on the market and what is the product or service you offer. Thus, you will not write anything that goes against the philosophy or the objectives of the company in question.
Person
This is a topic related to the profile of the customer’s customers. Here are the data: age, profession and why that institution can be attractive to them.
It is essential that you pay attention to these aspects to produce an interesting and productive text for these people. Without this information, you run the risk of writing an article that does not suit the taste of the company.
Language
Without any doubt, language is a very important factor! When you are writing a text for a company, it is as if you were speaking for it.
For that reason, it would not be at all prudent to represent a company using inappropriate language. To avoid that problem, read what writing tone you need to use. Whether it should be casual, objective or formal, for example.
Trust the pitch
Just as the briefing is a kind of writing about the company to which the service is being offered, the pitch is the skeleton of your text. Keep reading to discover the things you should pay attention to when you read the pitch:
Description
The description of a pitch contains everything that cannot be missing in the text. It goes from the keywords to the main focus of the article. Pay attention also to the way you should refer to the brand, so you do not end up making propaganda!
References
The references are there to be used. Generally, they are texts addressed to the same profile or with a similar content that can be used as a basis for your article.
That said, be careful not to copy other sites textually. Certainly, they are not paying you to do a copy / paste of another article on the Internet.
Be patient
This is not the time for you to be arrogant or disqualify your bad mood for a difficult day over someone. Success to get out of this complicated situation with your client depends mainly on your ability to listen, adapt and evolve.
Many people forget the most obvious and consistent procedure in these situations, which is to ask: “What happened?”. Open the dialogue, listen to what the client has to say and get the information you need to offer a productive solution.
If you want to convince someone that they should give you a second chance, show that you are really concerned about the situation, be calm and try to understand the reason for their dissatisfaction. Put yourself in the client’s shoes and do not forget these fundamental qualities:
Punctuality and efficiency
When it is possible to solve the problem immediately, do it. The longer you spend, the worse, because the customer’s dissatisfaction will continue to rise. Show that you are always ready to solve any problem and always meet deadlines!
Humility and wisdom
Learn from your mistakes to avoid future claims. The best way to work the problems is in a preventive way.
Do not forget that if a certain claim is being repeated very frequently, you probably have something to correct. Thus, the secret to getting out of this situation is to face the error as an opportunity to improve and take care that it does not happen again. Always have the humility to recognize your faults and the wisdom not to repeat them.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing services to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks file, critical financial documents and back office tools in an efficient and secure environment. Complete Controller’s team of US based accounting professionals are certified QuickBooks™️ ProAdvisor’s providing bookkeeping, record storage, performance reporting and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay services. With flat rate service plans, Complete Controller is the most cost effective expert accounting solution for business, family office, trusts, and households of any size or complexity.
Every time in the news they talk about the labor market situation, we put our hands in the head. There are many kinds of unemployed and, therefore, in our country it is difficult for unemployment to fall by 8% even in the most buoyant years. For you to understand, we explain what types of unemployment exist.
First of all, it is important that you have two concepts clear. On the one hand, an unemployed person is a person who is part of the active population, is of working age and cannot find a job, although he wants to work.
On the other hand, the unemployment rate measures the relationship between the number of unemployed and the total active population. In other words, it reflects how many people in 100 cannot work. For example, unemployment in the US was 16.55% during 2017. This means that almost 17 people out of 100 did not find a job.
Structural unemployment
This kind of unemployment corresponds to a sustained mismatch between labor supply and demand. It is a long-term unemployment that does not diminish or disappear through employment creation measures based on increasing demand. It is usually related to the rigidities of the labor market and the inability to solve them, as well as the technological advances that make a part of the active population obsolete.
Structural unemployment is between 15% and 18% in the US, according to data from the Foundation of Savings Banks. That is why it is very difficult for total unemployment to fall below this percentage without special measures, and there are two ways to solve the problem:
On the one hand, social welfare policies, such as the reduction of working time, professional recycling or income redistribution measures such as universal basic income or insertion income.
On the other hand, the policies that propose the flexibility of the labor market (that is easier to hire and fire workers) or the reduction of labor costs (lower salaries) so that more people can access the distribution of wealth, among other measures.
Cyclic unemployment
It is directly related to the economic cycle in which we are. This kind of unemployment increases during times of crisis due to the worsening economic conditions. On the contrary, it decreases when a bonanza stage occurs.
For example, between 2008 and 2013, during the worst years of the crisis, cyclical unemployment skyrocketed in the US. As the economic situation has improved, the rate of cyclical unemployment has been reduced.
Seasonal unemployment
In an economy that depends heavily on tourism, seasonal unemployment affects significantly. This form of unemployment exists because certain economic activities only need labor at certain times of the year. Thus, in summer the tourism sector needs many workers and, when September arrives, these temporary employees return to the ranks of unemployment.
One way to mitigate the effect of this unemployment is to diversify the productive structure of a country so as not to depend too much on seasonal activities.
Frictional unemployment
The frictional is one of the most particular types of unemployment that exist. It reflects the number of people who do not work voluntarily, either because they are rotating between jobs, studying or looking for a better job, among other reasons. It is also possible that there is a labor mismatch: a difference between the characteristics of jobs and workers.
For example, it occurs when a recent graduate in computer science rejects the first job he finds as a mason and hopes to get a job more in line with his preparation and expectations. Or when a doctor of philosophy decides not to work in a restaurant while finding a position in line with his professional training.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing services to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks file, critical financial documents and back office tools in an efficient and secure environment. Complete Controller’s team of US based accounting professionals are certified QuickBooks™️ ProAdvisor’s providing bookkeeping, record storage, performance reporting and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay services. With flat rate service plans, Complete Controller is the most cost effective expert accounting solution for business, family office, trusts, and households of any size or complexity.
It is a well-known fact that accounting is likely the most loved errand of some of the most imaginative entrepreneurs since it does not deliver any benefit and can be overpowering. Outsourcing this bit of their activity can be helpful, yet doing it without anyone else’s help has its advantages as well. How about we investigate the advantages and disadvantages of each.
Hiring a Bookkeeper
It is extremely difficult for a businessperson to hand over control of their business procedures; however, enlisting somebody to take care of business can be a genuine weight off a person’s shoulders. Outsourcing this month-to-month errand gives a person more opportunity to center around the parts of their business that they adore, which ordinarily converts into profiting.
Another advantage of outsourcing accounting is that it can easily be done under opportune premise. This gives a person a chance to settle on choices in view of the well being of their business as opposed to one side in their financial balance.
There are two or three drawbacks to outsourcing this undertaking. One is that it is an extra month-to-month cost that a person will have to get ready for. Most accountants charge between $75-300 multi-months, contingent upon what number of exchanges a person has and what number of records should be adjusted. This is presumably the greatest boundary for most organizations who are considering employing a clerk.
Another drawback to outsourcing this undertaking is that occasionally, by not being knee-somewhere down in the numbers each month, entrepreneurs turn out to be less involved with their business funds and put some distance between the budgetary sides of things. To maintain a strategic distance from this, make sure to survey benefit and misfortune proclamation and asset report every month.
Do It Yourself Bookkeeping
As a bookkeeper, I even battle with investing significant time from taking a shot at customer work to get my accounting breakthrough, yet that sentiment of check it off my rundown and knowing how much cash I have made is a gigantic helper for me. Other than checking something off your rundown, there are a few advantages to doing your own accounting.
Presumably, the clearest advantage is that a person will spare cash by not paying another person. A person may need to put resources into some accounting preparing in the event that you don’t have accounting knowledge, however, it will at present be far less demanding on the financial balance in the event that a person “DIY”.
Another advantage is that a person will be exceptionally mindful of where their cash is going and when it is coming in. I realize that occasionally I am stunned subsequent to completing my accounting and I perceive how high portions of my posts have gotten. That is the point at which I find a way to reign in my spending in future months.
Much the same as with enlisting an accountant, doing it without anyone else’s help can have a few cons. I think the greatest one is that it is totally up to them to stay aware of the accounting. It is such a simple thing to consistently put to the base of their daily agenda and the vast majority do not have somebody monitoring them to ensure it has finished. To battle this, discover a business companion who likewise needs a little responsibility. Have a date every month that a person intend to check in with each other so there is a little strain to complete it!
The other bummer to “DIY” accounting is that it detracts from their opportunity to be inventive and do the piece of their business that makes them cheerful. Except if they are a bookkeeper, they most likely did not begin their business since they cherish managing cash and monitoring it. A few people develop to love this piece of their business, yet some do not and after that end up postponing it until the point that duty time which as a rule is not exceptionally fun.
Regardless of whether a person chooses to outsource their accounting or keep on doing it themselves, the key is to get a predictableprocedure set up to ensure it completes. It sounds less demanding than it is, however, once that happens, a person can quit pushing and spotlight on different parts of their business.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing services to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks file, critical financial documents and back office tools in an efficient and secure environment. Complete Controller’s team of US based accounting professionals are certified QuickBooks™️ ProAdvisor’s providing bookkeeping, record storage, performance reporting and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay services. With flat rate service plans, Complete Controller is the most cost effective expert accounting solution for business, family office, trusts, and households of any size or complexity.