If you wish to negotiate straight with the creditor, ask the collection agency for the number of the original creditor’s department. Call the creditor and then ask if you can negotiate with the creditor on the debt directly.
Preferably, the creditor will instantly negotiate with you, and you will work something out. Regrettably, that is rare. It is more probable that the creditor will take only the debt back if you talk with the collection agency, create a reimbursement plan, and make some payments under the plan. If this occurs, then the creditor could ultimately give you a new line of credit, helping you reconstructyourcredit.
If You Make an Agreement with the Creditor
If the creditor agrees to negotiate, be sure the debt is owned. If the collection agency accepted the debt from the creditor, the agency owns the debt. If you talk it through and make payments to the creditor, the collector may not accept those payments.
You may negotiate a payoff of the debt in one go, or possibly negotiate a better payment strategy. These are the same choices and possibilities available if you talked it directly with the collector, though the creditor may be a little more flexible and willing to cooperate.
You may also want to inquire about having the negative credit info on the debt detached from your credit file, or shown as reimbursement in full if you make payments under the new contract.
Get It in Writing
Put any contract you grasp with the creditor in the script—preferably, in a letter from the creditor, even though a letter from your end to the creditor approving the pact and asking the creditor to fix any mistakes is relatively better than nothing. Part of the inscribed contract must be an acknowledgment from the creditor that it possesses the debt.
Send a duplicate of the letter to the collector.
If you require any help dealing with a debt collector or a creditor or prefer someone else handling your debt consultations, consider talking about this with a debt settlement lawyer.
It is a lot better to deal with the creditors more than the debt collectors. Any the past-due debt may be for – car loan, credit card payments, doctor bills – the creditor could still see you as a potential returning customer. A debt collector’s topmost and probably only interest is squeezing money out of your pocket.
A debt collector could settle for about 50% of the bill.
Debtors may pick to negotiate for better refund terms, to have the debt stated as paid in full on their credit reports, or to have calls end altogether. Here is how to talk with debt collectors:
Understand your rights.
Verify that it is your debt.
Mention bankruptcy.
Be watchful of the statute of boundaries.
Get the payment contract in writing.
Ponder the kind of debt you owe.
Speak calmly and rationally.
Negotiate how debt will be reported to credit agencies.
If the debt is a reasonable one that you forgot to pay, ending the calls can be as easy as writing a check. But in further occurrences, if the debt is sky-high, the caller sounds suspicious and doubtful, and you are not entirely sure if the debt is your accountability, you might want to take a step back and talk it over with the debt collector.
Conclusion
Ideally, you would not have any debts go to a debt collector, life happens, and at times it can’t be avoided. First, if you understand your rights, you can use these tips to your advantage and keep the debt from harming your credit score. The most important thing to remember is that you work at gaining control of your debt as soon as possible.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Marketing is a crucial component of running a successful business. It encompasses various strategies and techniques aimed at reaching the right audience—those customers and clients who will find value in your products and services. Identifying this audience requires more than mere intuition; it necessitates a systematic approach.
After dedicating long hours to developing an exceptional service or product, it’s vital to recognize that this is only half the battle. The next step is to effectively introduce your offering to potential customers, ensuring they understand its value. While general marketing efforts can potentially reach a wide audience, focusing on more targeted markets can drastically improve your marketing return on investment (ROI).
Understanding the nuances of when and to whom to market your service or product is essential for achieving a significantly higher ROI. This involves developing structured marketing strategies rather than relying on broad, unfocused campaigns. If you find yourself unsure about how to begin this process, consider the following detailed steps that can guide you in identifying your target market.
Sharpen Your Focus
One of the most powerful strategies you can employ to market your product effectively and professionally is to narrow your focus. This means prioritizing specific efforts that will yield the best results. To identify these priorities, consider the following guidelines:
Clarify the needs your product fulfills
Start by understanding the problems your product or service addresses. What needs does it fulfill for potential customers? By pinpointing these needs, you can better position your marketing messages to resonate with your target audience.
Employ a funnel approach
Utilize a funnel marketing strategy to systematically narrow down your audience. Begin with broader demographics, such as age or gender, and gradually drill down to create a more defined profile of your ideal customer. For instance, if your product is gender-specific, begin by filtering your audience by gender and then consider other factors like age and income. This approach will guide you toward a more concentrated target market that is more likely to engage with your offerings.
Emphasize key value propositions
Clearly communicate the unique value propositions of your product or service. What sets it apart from competitors? Why should potential customers choose your offering? Crafting compelling messaging around these propositions will help capture the attention of your desired audience.
Gather Comprehensive Data
Choosing the right market requires a commitment to basing your decisions on objective data rather than assumptions. Gathering relevant information can come from various sources and strategies:
Conduct surveys
One effective way to collect valuable data is through surveys. Design surveys that target potential customers to reveal their preferences and interests. You can distribute these surveys through various channels, such as email blasts, social media, or newsletters. Consider using survey tools or working with a marketing firm to reach a broader audience. Analyzing this demographic information will enable you to identify which groups respond positively to your service or product, providing insights into whom you should ultimately target in your marketing efforts.
Analyze existing data
If your business offers a product that is similar to those already available in the market, dedicate time to researching existing competitors. Look into their customer demographics, purchasing patterns, and peak buying times. You can find a wealth of information online about consumer behavior, including industry reports, market analysis, and sales figures. This macro-level understanding can help you identify trends, and you can further narrow your analysis to focus on specific consumer segments relevant to your offering.
Tap into your network for insights
Leverage the insights from your personal and professional network. Observe and engage with your family, friends, and colleagues regarding the products they use. Would they consider purchasing your service or product? Ask open-ended questions like, “What do you think about this product? Would you find it useful? Are there people in your circle who might benefit from it?” This can yield invaluable feedback and perspective that may shape your understanding of the market.
In addition to casual conversations, engage with your professional contacts, including corporate sponsors and mentors. Seek their honest assessment of your service or product and ask if they would be willing to try it out. Their experiences and insights might highlight untapped markets or innovative uses for your product that you hadn’t previously considered.
Make it a priority to integrate diverse perspectives into your marketing strategy. The goal is to effectively align the needs and preferences of your target demographic with the unique offerings of your product. By actively researching various information streams and continuously striving to identify your target customers, you will be better equipped to maximize your marketing ROI and drive business success.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Doing new business by growing your client base is essential for your business success though it can be extremely challenging. Growth is vital if you wish for the long-term survival of your business. It makes it extremely easy to obtain possessions or assets, entice new talent, and fund reserves. Similarly, it drives business profit and performance. Here are five market strategies to help you grow your business.
Know Your Customers
Try understanding the needs of your customers and develop services and products that meet those requirements. You can gain an insight into your customers by personalizing your services and inspiring them to deliver you with feedback.
If you become friends with your customers, it makes it easier for them to trust you. Once trust is gained, they won’t rush about other places to look for the same service or product but rather hit you up or use what you offer.
Make sure you do not go against their trust. Be considerate and help your customers with whatever the matter may be.
Use Social Media
Social media is a lot more powerful than we think. It’s a tool that can help promote your business to potential customers and gain valuable insights through ‘social listening.’ This way, you can easily find out what your customers have to say about you, learn a little insight into their behavior, categorize keywords and trends that attract your target market, plus improve your customer service. Through Social media, you can build yourself a business profile and fascinate new customers. Just think about the possibilities.
Most people find social media a waste of time and energy, and that’s because they have zero ideas about the whole other world that lives online. Sooner or later, everything will be available with just one touch of a finger, thus its best to keep up with the social media trends to fit in the market and be successful.
Nurture Existing Customers and Look for New Opportunities
Keep your strategies in place to nurture current customers, something like staying in touch with them through an e-newsletter or informing them about the promotional events that may be ahead of time.
All at once, look for chances to get more work and build yourself a customer base. But be sure you find the correct balance between nurturing customers as well as finding new ones.
Attend networking events
Devote time to build your connections and networks – It is not what you know but who you know.
Networking and interacting lets you build associations with other people and inspire them to refer more customers to you via word of mouth.
As mentioned earlier, the world is moving fast, and sooner or later, everything will be available with just one touch of a hand. That makes networking so crucial and essential for every business to succeed and grow.
Refine Your Approach
It would be best to check where the consumers are coming from to measure whether your advertising activities are successful. Do not be terrified to experiment or take risks. Improve your tactic if something is not working and focus most of your time on the events that attain the best results.
The ideas, opportunities, and approaches are limitless. Keep trying whatever hits your mind. Add effort, and never be afraid of falling. Instead, be scared of not getting up after you fall.
Business is a race, and everyone is busy running forward and crushing other firms and organizations. Your goal must be to stay ahead, never be on anyone’s blacklist, develop new strategies for your customers and your business, and see yourself make your way to the top.
So many reasons outgrow business leaders to consider a “continuous growth” mindset. A financially secure and growing firm repeatedly enjoys market supremacy which means, less threat from the opponents, which in sequence brings boosted power to negotiate large-scale consumptions such as new technologies and more beneficial tenancy or rent measures.
Plus, active growth helps stave off the potentially damaging properties of variations in the market and state economy. Also, a growing business’s high profile often attracts talented job-seekers that are out there.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Small businesses must have a strong presence online to be found by potential customers and retain loyal repeat customers. A small business owner or marketingteam must develop an effective online marketing strategy to accomplish this strong presence.
As with the formulation of other marketing and sales strategies, many small businesses and sole proprietors find it challenging to develop a suitable online marketing strategy. Having a website or the placement of some Google AdWords ads is far from sufficient. You should understand and use more detailed strategies. Here are some online marketing strategies that will benefit your small business.
List search terms
Based on your business industry and the area in which your business is located, create a list of terms that potential customers could enter when searching for suitable providers in search engines. Don’t forget variants of the terms. After you have formulated your search term list, use the corresponding (free) Google AdWords tool to analyze how often the terms you list are entered as search terms on Google.
Analyze the competition
Enter the most relevant terms you have discovered for your business and industry and see how many competitors have AdWords ads based on these terms and which organizations are on the first page. Suppose there are many large companies or associations and trade magazines. In that case, you should consider whether, despite optimizing your website, you have a realistic chance of being among the top search engines. If not, think about whether it would not make more sense to optimize your website for keyword combinations instead of individual terms or more specific terms.
Define and categorize search terms
Then decide on which search terms you want to optimize your website. But this shouldn’t be more than half a dozen terms. When it comes to search terms, differentiate between the top terms or combinations of keywords, in which your website has to come out on top, and those where you can also live with a mediocre result. With the rather less competitive search terms, think about the extent to which you can achieve good results with press releases in the hit lists of free PR portals or with specialist articles on corresponding online portals.
Optimize website
Optimize the source text of your website based on the search terms you have selected. Make sure, among other things, that the terms used to optimize the website appear on the page several times – if possible, marked as a heading.
Run AdWords ads
If your budget allows, run AdWords ads for the less competitive and, therefore, cheaper terms. Ensure that the terms are sufficientlyspecified (examples: sales management, sales management) so that the wastage is low. If you need to go fast, you may also want to run AdWords ads for the terms you optimized your website for after the first time you optimized your website because it takes some time for the optimized page to climb up in the Google ranking.
Force link building on the website
A central influencingfactor in your Google website’s ranking is the number of reference links to it. Therefore, you should conclude so-called link partnerships with friends, colleagues, or suppliers, which means that they refer to each other to their pages. Also, enter your contact details and web address in free online directories and regularly place press releases about your products and services in the above-mentioned PR portals.
Make links with online PR
Write regular articles on your core topics or key terms with your contact details and offer these suitable online portals. Publications there or links displayed are rated higher by Google than publications on free PR portals. With the links generated by contributions, your target customers can come to your website links.
Check the website regularly
Google rankings are constantly changing – partly because Google regularly changes its criteria. Your competitors are also active. Therefore, use a Google analysis program to monitor how your website is developing in relation to the search terms you have defined. From the results, you can deduce which terms you want to optimize your website for and which AdWords ads you should be able to support.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Downsizing has become a word no one wants to say or hear regarding business. Though not every company will experience downsizing, it becomes necessary for a company to survive in some cases. Companies may hit financial difficulties caused by poor business management, difficulties in the industry, natural disasters, or uncontrollable circumstances. An example would be the COVID-19 pandemic of 2020. The pandemic affected businesses of all sizes and, in some cases, decimated industries. To survive, many businesses had to downsize. COVID-19 is one example, but many factors can cause a company to consider or implement downsizing.
Common reasons for downsizing
A large-scale disaster like COVID-19 is a rarity when it comes to reasons for downsizing. Here are some common reasons for downsizing.
Mergers: Mergers combine two separate businesses into a single new legal entity. True mergers are uncommon because it’s rare for two equal companies to mutually benefit from combining resources and staff, including their CEOs. Often after companies merge, there are double positions. This doubling of employees means there will need to be downsizing to streamline the business and cut salaries.
Acquisitions: Acquisitions have one company purchasing all or part of another company with agreements by both companies. An acquisition could be that the acquiring company needs to strengthen the company or department or that the selling business is having financial difficulties or has no need for specific aspects of the company. In some cases, downsizing becomes necessary due to dual positions or streamlining.
Takeovers: Takeovers are when one company is financially vulnerable, and the acquiring company exploits the vulnerability by appealing to stakeholders through financial relief. A takeover downsizing is often inevitable because, in many cases, if a company is dying, the acquiring company will break it apart rather than attempt to revitalize it.
Regardless of downsizing, there are myths and facts about downsizing that are important for a business owner facing downsizing needs to understand. Here are some myths and facts about downsizing you and your company’s decision-makers need to know before deciding to downsize.
Myth: Larger, financially strong companies never downsize. Fact: Larger, financially strong companies downsize to boost company performance by reducing headcount.
Myth: Companies don’t hire while they are downsizing. Fact: Companies may lay off two of their non-productive employees and hire one competent employee in their place of them.
Myth: Downsizing is always about the economic crisis. Fact: Downsizing can sometimes be about overstaffing or eliminating a position.
Myth: Downsizing is permanent. Fact: Downsizing is often temporary; in some cases, the original employees will be rehired if they are valuable.
Myth: Downsizing is always profitable. Fact: Downsizing can sometimes be costly if done incorrectly.
Myth: Downsizing is the only solution to the financial problem. Fact: Downsizing should be considered the last option to solve a financial problem.
Myth: Only the downsized department suffers after downsizing. Fact: Other departments often pick up the slack for the downsized department.
Myth: The employees that are retained perform better to survive further downsizing. Fact: Generally, retained employees suffer from lower morale and become demotivated.
Myth: Downsizing is a quick and easy process for a company. Fact: A lot of work and planning goes into downsizing to keep the company running smoothly.
Conclusion
Companies should go through self-analysis before downsizing. There are several ways to prevent downsizing and overcome the financial or performance crisis. It is better to hire smartly rather than go through downsizing later since a company invests time and resources when it hires an employee. Many factors can cause downsizing, and if you are aware of the myths and facts, it will help you and your decision-makers to know whether downsizing is the answer to your company’s needs.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Each month, more than 2 billion messages are exchanged between Facebook Messenger users and businesses. According to a Facebook study conducted on a sample of 12,500 people, it turns out that consumers particularly appreciate this type of communication with businesses:
56% of respondents prefer to send a message to a company rather than call it for customer service
61% of respondents prefer to receive personalized messages from companies
More than 50% prefer to buy from a company to which they can send a message
However, it is far from easy to be reactive on Messenger and offer excellent customer service. Fortunately, there are a series of tools and features that you can activate to improve or automate the quality of your customer service and communications on Messenger.
As a business, treating your customers well and communicating with them regularly, whether in person, through mailings, or online, is in your best interest. It is estimated that 60% of the world’s population is online. Therefore, you must have a strong online presence to communicate successfully with your customers. Whether the approach is indirect, such as posts and other general outreach hoping to hit your target customer or through one-on-one communication, utilizing your online connections is vital. Here are five creative ways you can communicate with your customers online through direct messaging.
Answering FAQs with automatic direct messaging replies
You can use settings on your social media platforms to give automatic replies to frequently asked questions. It only takes a few moments, but the payoff is significant when an automated system can often answer asked questions. This leaves time to answer other questions and focus on other operations.
If you can’t find the setting to implement automatic replies, consult the social media platform’s help desk.
Communicate important news on Messenger thanks to ManyChat
If you’re email marketing, ManyChat allows you to build your contact list on Messenger and send them all the same message. The ManyChat tool enables you to create a Messenger bot, an assistant who creates messages for you per a scenario more or less defined in advance.
Be sure that using the ManyChat tool meets with the platform’s policies. You do risk being reported when using a messenger bot, leading to a temporary or permanent block from the platform.
Encourage conversations with click ads to direct messaging
Click ads to direct messaging is an advertising tool that some social media platforms make available to businesses to encourage them to communicate through direct messages with potential customers. The real appeal of click-to-direct messaging ads is the conversational aspect. This allows you to chat with a prospect interested in what you’re offering and answer any questions they might have.
Embed a direct messaging chat on your website
Having a Live Chat on your website is a fantastic tool for chatting directly with your visitors and customers. Many studies show that sites that use live chat have higher conversion rates and a higher percentage of their visitors who return after their first visit.
Send reminders through direct messaging
Some social media platforms offer ways to set appointments for your business through the platform or provide a link for your website to do so. There can be a way to set up an appointment reminder through direct messaging and email on these platforms. This direct messaging reminder is another way to connect with customers that gives a personal touch.
Conclusion
There are many ways to communicate with customers that are both traditional and up with the times. In today’s business world, having a strong online presence and utilizing the communication tools offered is a great way to communicate with your cherished customers.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
FinTech is a short term of financialtechnology. It is comprised of programs, systems, and technology used for financial matters and banking related transactions. Finance is a profession that needs thorough knowledge, and the issues are legal. Technology is in the era of evolution and is used for all aspects of business and finance. The term fintech is widely used for banking systems, loans, and apps for smartphones. The purpose is to provide user-friendly and hassle-free banking for clients.
The financial industry has its branches worldwide, and it is a business of multimillion dollars. The primary industry that uses fintech is the banking and finance industry. Since the advancement of mobile devices and all aspects of life are at the user’s fingertips, banking and financial apps are also in demand. Budgeting, paying utility bills online, doing funds transfers everything is easy and takes no more than a few seconds. Companies spend a significant amount on FinTech apps. More than 80% of the UK and US population prefer using one or the other fintech app for their everyday financial use. Making digital payments has become more accessible and quicker with fintech apps and technology.
Establishing a fintech company is not an easy task and requires a considerable amount of money. But there are things to be kept in mind when you start a fintech company.
Address a Need
There are millions of users, and they regularly face many problems when dealing with financial matters. The first thing is to decide what need you are addressing. If you are focusing on making an app about online billing, then cover all the aspects of online billing rather than putting every other financial option on the app and making it confusing.
Keep updating
Spending once on a feature and then not updating it is useless. Updating is important. There will be many aspects to work on once you launch your system online. Keep working for the betterment and keep making it more user-friendly.
Be Flexible
The original idea is always essential and is constant. Every other thing revolves around it. Be open to changes and modifications. The financial world twists and turns every day. Some options and ideas need to be skipped for your system and solution to work. Be very flexible to modernize your system according to modern-day needs. Not just for a fintech company, every other business needs the flexibility to modernize and compete in the market.
Be fair and transparent
What throws a wrench on your business during start-up is not considering all the legal aspects. Finance is a legal matter itself. When you are trying to put your feet on something as massive as the financial world, you must fulfill all the legal requirements and provide accurate and precise data. Don’t rush to start a fintech company without clearing all the legal stipulations.
Don’t opt for giant leaps
Starting is always exciting and accelerating but never expect big bonuses during the start-ups. At the time of starting up, the company invests more time and money. The revenue is never generated within days and weeks. Expect the ups and downs and take small steps toward your goal. It is the same as any other start-up business; keep buzzing until you are heard.
Use Social Media
It is wise to use social media to build brand awareness. Consider it as an option to invest in and use it as a marketing tool. It requires minimum investment and reaches the maximum number of people
It is the perfect time to start a fintech company as it is one of the most advancing industries. Nobody ever thought about plastic money 30 years ago, but it is a necessity now. Likewise, the thing that you are conceptualizing right now might become essential for people years later.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
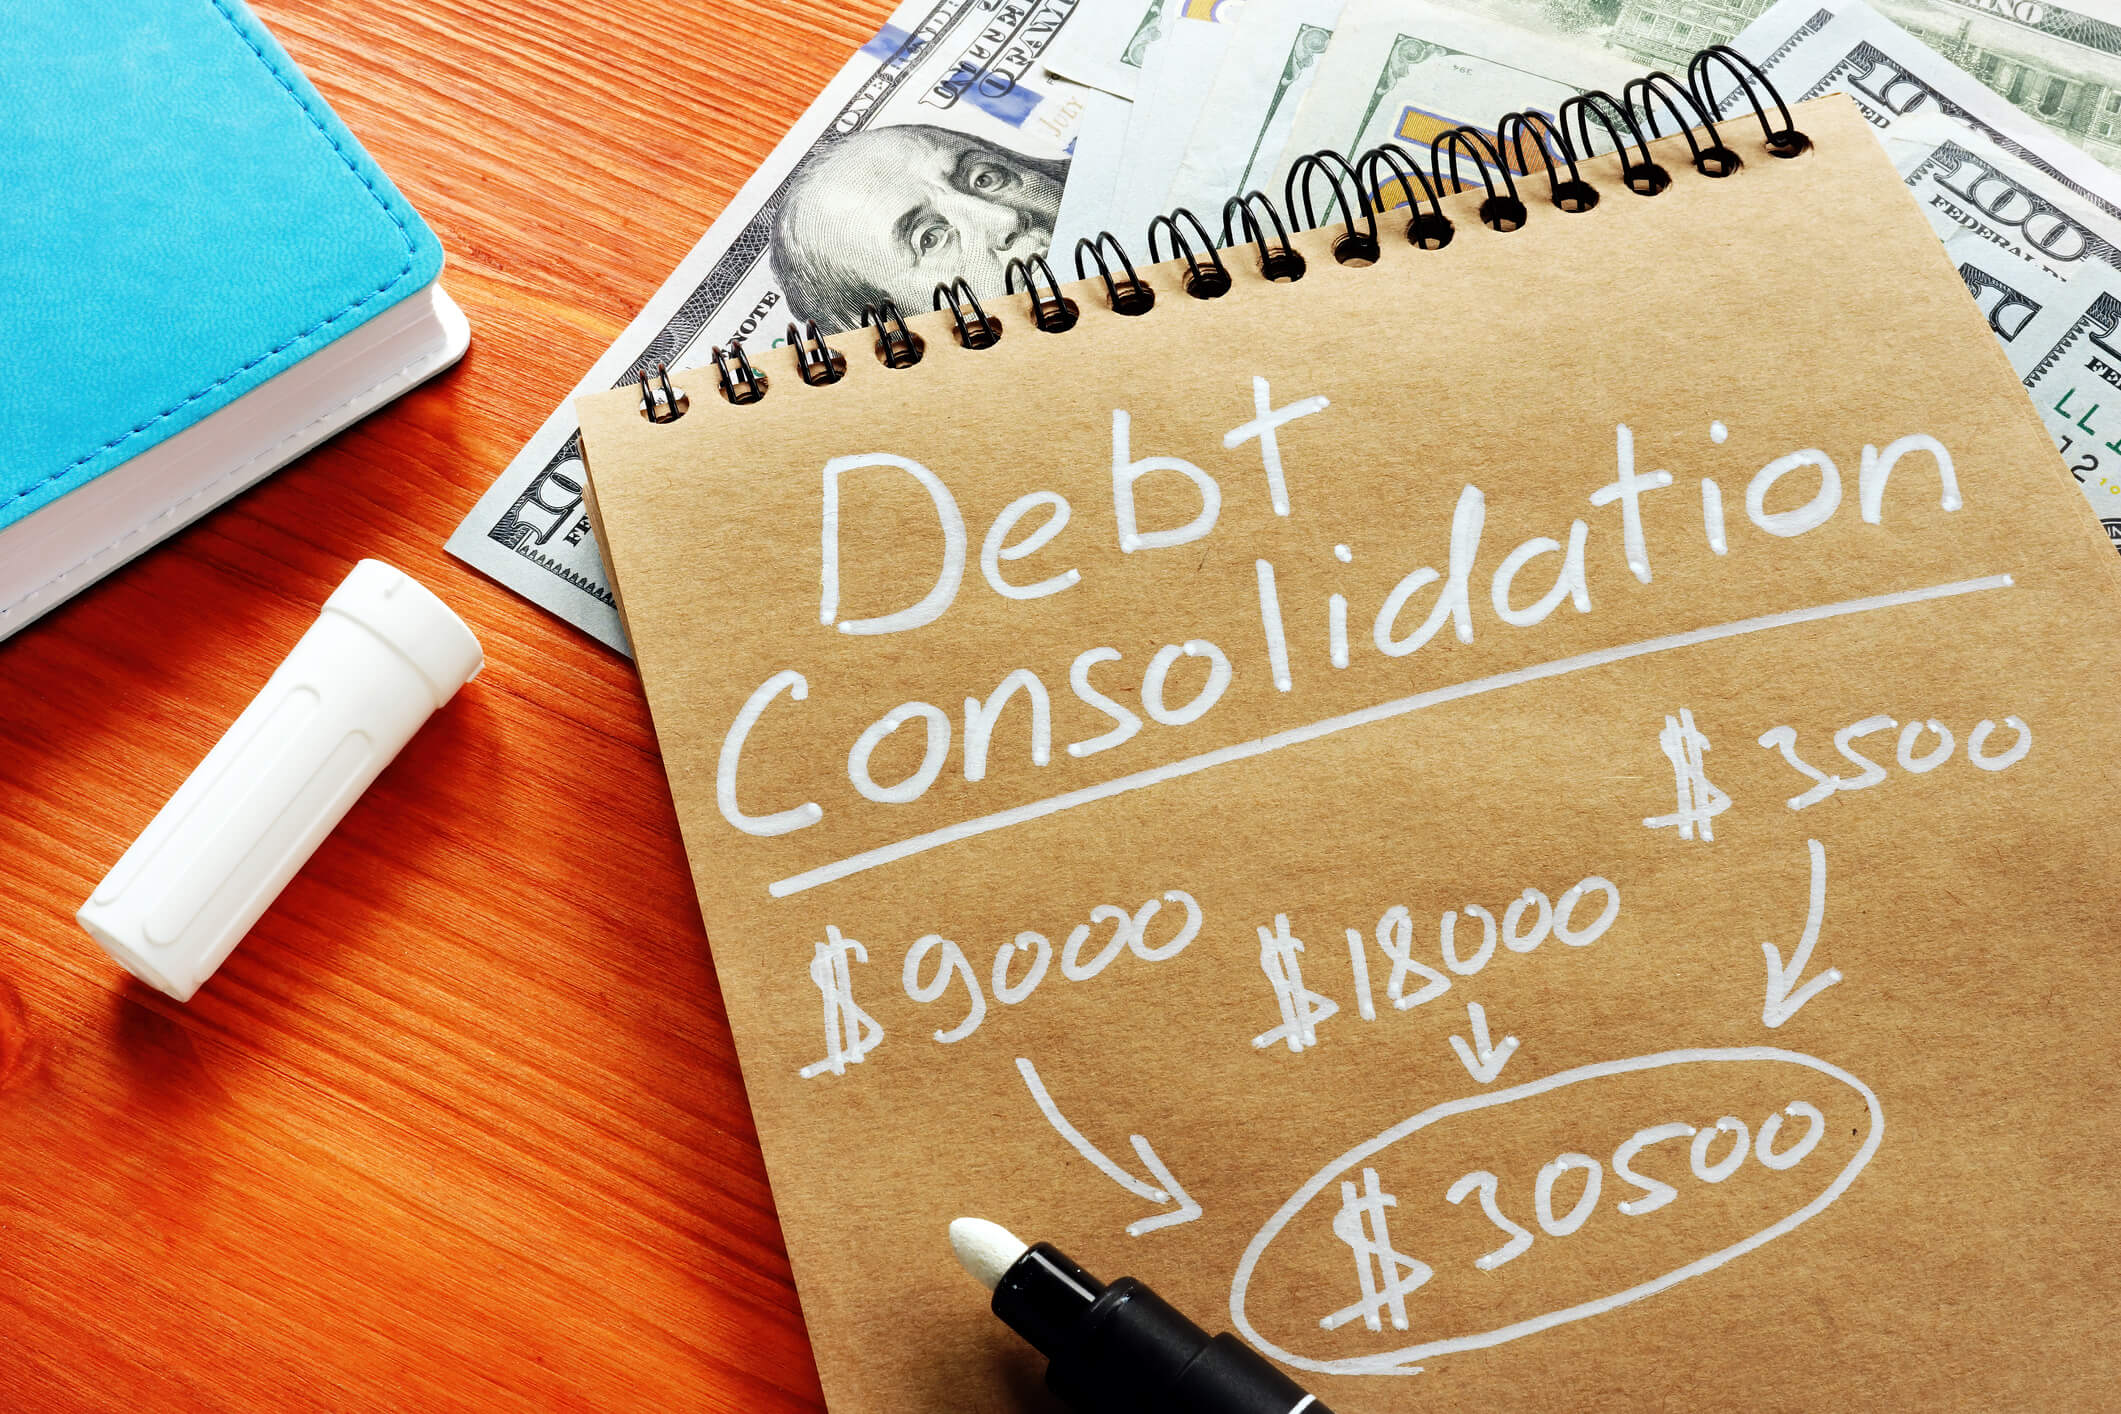
If credit cards keep your wallet full, ring up debts on many of them, and struggle each month even to make the smallest payments, it may be time to consider combining all that you owe into a single monthly expense.
There are five ways to consolidate unsecured debt, and one uses a collateralized loan.
Lend from a retirement savings plan like a Roth IRA or a 401(k)
Assemble a debt organizing payment plan via a nonprofit credit counseling agency
Use a home equity line of credit (HELOC) or home equity loan to pay off your creditors, efficiently transferring your balance to a minor interest loan, but one that uses your house as a warranty
Handover unpaid balances to a sole credit card with a minor interest rate
Take out a personal loan
Your tactic will pivot on your solvency. The FICO score, the number of credit rating activities assigned to your funds, is vital in defining if you can get a loan or business credit line vast enough to combine your debts at an interest rate that makes sense.
Nonprofit Credit Counseling Agency
Nonprofit agencies are businesses that examine your debt state and counsel you on the best sequence of action. If that includes merging your debt, the counseling agencies will discuss with your creditors and make a debt management plan. The credit counselor works with card businesses to obtain nominal interest rates and dues in return for a particular monthly payment. The credit counseling agencies collect the monthly expense and distribute it to the card corporations at the settled rate. There is little but sometimes no charge for the services.
Credit Card Balance Transfers
Transporting numerous credit card balances to a single card with a nominal interest rate is a do-it-yourself association. People who issue credit cards propose balance transmissions to construct new corporates. They provide current or new customers a no-interest-payment period on transported balances. The catch is the 0% interest lasts for a preliminary period, usually 12-18 months. That means you will have to pay off your balances before the period expires or face recurring to high-interest debt.
Personal Loans
Individual loans used to unite credit card debt are alternative ways of turning various balances into a single payment that is too monthly. These loans, which do not need security, are accessible through banks, credit unions, and many online moneylenders. They give those with less than excellent credit scores an opportunity to change rotating debt into a fixed monthly payment at nominal interest rates.
Home Equity Loans and Lines of Credit
Using a HELOC or a home equity loan to consolidate credit card debt can considerably lessen your monthly payments, but it is a risky strategy. Home loans use the dwelling as a guarantee. If you cannot afford to repay the loan, the lender can exclude your property, perhaps could even cost your home and whatever equity you have inside.
HELOC allows you to lend against your financial stake in your house. However, moneylenders only let you lend a part of your equity. What you borrow can also be a home equity loan or a credit line (HELOC), which you may use as you like for fixed years. To consolidate, you may use the equity loan carry on to pay off credit cards.
Retirement Loans
If you have a 401 (k) retirement strategy from past employment, you could be able to pay off your credit card debts from your balance. Not all employers plan permits this. If yours does, you can borrow $50,000 or half your devolved account balance, whichever is a smaller amount. You will have five years to repay that money. Most plans charge interest, advance, which is typically the prime rate plus 1%.
You may withdraw as well, but not borrow money from a Roth or an IRA to pay off your balances, but there are noteworthydrawbacks. If you’re younger than 59 ½, you will have to pay the penalty on IRA extractions. You may withdraw from the portion of your Roth IRA that you placed in the account. In both situations, you will face damaging your retirement savings.
If it is a combination, break down your debt into protected and unsecured groups. That is vital because protected debt is devoted to something you own. If you owe money on some car and do not pay, the creditor will reclaim the vehicle. If you own a house, failure to make expenses can lead to foreclosure.
Of course, there are pros and cons to everything, do your research and find out before you jump to conclusions.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Dangerous business thought patterns are the recurring mental habits—confirmation bias, sunk cost thinking, and groupthink—that quietly distort how leaders read data, weigh risk, and respond to dissent, often steering profitable companies straight into avoidable crisis. These patterns shape every major decision you make, from pricing and hiring to whether you keep funding a failing project, and they typically operate below conscious awareness until the damage shows up in your financials.
In my 20+ years building Complete Controller and working alongside thousands of business owners across nearly every industry, I’ve learned something that surprised me early on: poor strategy is rarely the root problem. The real culprit is almost always a dangerous business mindset that no one is brave enough to challenge. In this article, I’ll walk you through the three most damaging thought patterns I see in small and mid-sized businesses, show you how they connect to cognitive biases in leadership and corporate risk psychology, and give you the exact tools to replace them with healthier thinking that actually grows your company.
What are the 3 most dangerous business thought patterns to avoid and how do you change them?
The 3 most dangerous business thought patterns are: confirmation bias (“I’m right, so the data must be wrong”), the sunk cost fallacy (“We’ve invested too much to stop”), and groupthink (“If no one objects, we must be right”).
Each pattern distorts your perception of reality, causing you to ignore risk signals, double down on losing strategies, and miss critical chances to course-correct.
These distortions are powered by subconscious cognitive biases in leadership—habits of thought that feel true but aren’t grounded in balanced evidence.
Left unchecked, they fuel manipulative leadership tactics, rationalize financial fraud behavior, and normalize a groupthink culture where dissent gets suppressed.
You change them by building structured risk processes, inviting independent challenge, creating psychological safety, and training yourself to spot distortions in real time.
Dangerous Business Thought Pattern #1: “I’m Right, So the Data Must Be Wrong”
This first pattern is driven by confirmation bias in business—the tendency to favor information that confirms what you already believe and discount anything that contradicts it. It’s the most common distortion I see in founders, because the same conviction that helps you start a company can blind you to signals that your model needs to evolve.
How confirmation bias quietly destroys decisions
Confirmation bias leads you to seek, interpret, and remember information that supports your existing view while ignoring conflicting data. In leadership, this turns strategy meetings into echo chambers where leaders overweight “good” signals and dismiss “bad” ones as anomalies—delaying corrective action until a manageable issue becomes a full crisis.
Day-to-day, this looks like:
Dismissing a negative cash flow forecast as “too conservative” without testing assumptions
Ignoring your bookkeeper’s warnings about receivables because “our customers always pay”
Only attending conferences and reading content that validates your existing strategy
Case study: Blockbuster vs. Netflix
In 2000, Blockbuster passed on buying Netflix for about $50 million. Netflix later wrote that Blockbuster’s CEO called their offer “a very small niche business.” Blockbuster executives reviewed the same market trends as Netflix but framed digital streaming as a distant threat instead of an urgent call to transform. By 2010, Blockbuster filed for bankruptcy while Netflix became a global media leader. The takeaway: when leaders assume the data must be wrong because it contradicts their story, they turn manageable strategic risks into existential ones.
Practical guardrails
Document what would change your mind before every major decision—then watch for that evidence honestly.
Assign a rotating “red team” role so one person formally challenges assumptions in every key meeting.
Lead with the numbers. At Complete Controller, my team has a standing rule: if the data conflicts with my intuition, the data gets the first word and the last word.
Dangerous Business Thought Pattern #2: “We’ve Already Invested Too Much to Stop Now”
This pattern centers on the sunk cost fallacy, a trap where past investment—not future value—drives present decisions. It sounds reasonable in the moment (“we’ve spent $250,000 on this software, we have to make it work”), which is exactly why it’s so destructive.
Why sunk costs hijack strategy
Daniel Kahneman and Amos Tversky’s landmark research on Prospect Theory showed that people feel losses roughly twice as intensely as equivalent gains. That loss aversion is what keeps leaders funding failing projects—abandoning the investment feels like admitting defeat, so they tolerate ongoing risk to avoid acknowledging the loss.
When sunk costs slide into financial fraud behavior
Here’s what I’ve watched happen more than once. It starts with bending the story—optimistic timelines, “bridge” explanations to investors, vague answers to lenders. If the underlying problem isn’t corrected, some leaders escalate to manipulating KPIs, hiding liabilities, or “borrowing from next quarter” to cover this quarter. Many notable corporate scandals didn’t start with intent to defraud; they started with a refusal to admit a failed bet.
A founder’s framework: Kill criteria
Before launching a major project, define measurable conditions for three outcomes:
Continue – metrics on track
Pivot – mixed results but clear learning
Terminate – metrics off-track with no viable correction
Then review them quarterly with your CFO or outsourced controller. I’ve watched owners keep unprofitable divisions alive for years because they couldn’t let go of money already spent. The healthiest leaders I know decide based on future cash flows, not past checks written.
Better decisions start with better financial visibility. See how Complete Controller helps business owners turn numbers into actionable insights.
Dangerous Business Thought Pattern #3: “If No One Objects, We Must Be Right”
This pattern is driven by groupthink culture—when the desire for harmony overrides realistic appraisal of alternatives. Psychologist Irving Janis, who coined the term, described eight classic symptoms including “self-censorship” and an “illusion of unanimity,” where silent people get mistaken for agreement. That’s exactly what makes this pattern so risky.
Corporate Groupthink risk factors and signs of toxic leadership
In businesses, groupthink shows up as meetings where the CEO speaks first, everyone nods, and genuine risks go unspoken. Watch for these signs of toxic leadership in companies:
Leaders subtly penalize disagreement or label skeptics as “not team players”
Data is cherry-picked to fit a preferred narrative
Bad news gets softened as it moves up the chain
People use side conversations to pressure alignment before meetings, instead of inviting open debate
Authority bias amplifies this: teams overvalue the founder’s opinion simply because of their role, not the merit of the argument. Once a few senior people agree, the bandwagon effect pulls everyone else along.
Building an anti-Groupthink culture
Have the most senior person speak last. Your opinion should never anchor the discussion.
Require a designated risk advocate in every major decision to list specific downsides and failure modes.
Run quarterly pre-mortems where teams imagine a project failed and work backward to identify why.
Some of the best decisions we’ve made at Complete Controller started with someone telling me, “I don’t think this will work.” I learned to reward the person who brings the uncomfortable truth.
How These Patterns Show Up in Your Numbers
Every dangerous thought pattern eventually leaves a financial fingerprint. Persistent margin compression with no action plan often signals confirmation bias about pricing. Long-running unprofitable products point to sunk cost thinking. Budget forecasts that stay unchanged despite missed targets reveal groupthink in your planning process.
This is where independent financial oversight changes everything. A third-party controller brings outside perspective and doesn’t share your internal biases. They can benchmark your margins, cash cycles, and risk profile against industry standards—highlighting where your thinking, not just your operations, is off. Embedding simple risk assessment checklists into your budgeting process (a habit we reinforce in our work on regular account reconciliation) helps depersonalize tough calls and reduce bias before it costs you real money.
A Founder’s Checklist: Early Warning Signs
Run through this quick self-diagnostic honestly:
You catch yourself saying “I just know I’m right” more often than “What does the data say?”
You hold onto unprofitable projects because “I can’t afford to write this off now”
Your team rarely challenges you; dissenters have stopped speaking up or left
You feel personally attacked when someone questions your strategy
In the next 30 days, pick one major decision currently in play and run it through a structured risk assessment with an independent advisor. Then choose one dangerous business thought pattern you recognize in yourself and focus on replacing it for the next month. Small shifts compound fast.
Final Thoughts: Rethinking Your Thinking Is Your Best Risk Strategy
The three dangerous business thought patterns we’ve covered—confirmation bias, sunk cost fallacy, and groupthink—silently shape your risk profile, your financial health, and your culture. Each is powered by specific cognitive biases, and each has clear tools you can use to disarm it before it becomes a crisis.
From my experience at Complete Controller, the owners who grow sustainably aren’t the ones who never make mistakes. They’re the ones willing to change how they think when the numbers tell a different story. If you want a partner who will give you honest, unbiased visibility into what your books are really saying, reach out to the team at Complete Controller today. Your next great decision starts with clearer thinking.
Frequently Asked Questions About Dangerous Business Thought Patterns
What are the most dangerous business thought patterns leaders fall into?
The three most damaging are confirmation bias (rejecting data that contradicts your beliefs), the sunk cost fallacy (continuing to invest because of money already spent), and groupthink (assuming silence means agreement). Each one distorts risk perception and delays course correction.
How do cognitive biases affect business decisions in real time?
Cognitive biases shape which data you notice, how you interpret it, and what you remember. In practice, they cause leaders to dismiss negative forecasts, ignore early warning signs from finance teams, and overweight information that confirms existing strategy—often without realizing it’s happening.
What are signs of toxic leadership in companies tied to groupthink?
Watch for penalized disagreement, cherry-picked data, bad news that softens as it moves up the chain, leading questions in meetings (“we all agree, right?”), and a pattern of rewarding loyalty over accuracy. Low psychological safety is the clearest signal.
How can I prevent sunk cost thinking from leading to financial fraud behavior?
Define kill criteria before launching any major project, separate “what we’ve spent” from “what this will return going forward,” and build independent financial review into your process. Most fraud starts with a refusal to admit a failed bet, not malicious intent.
Can outsourced bookkeeping really help me avoid a dangerous business mindset?
Yes—a strong outsourced partner gives you independent data, third-party benchmarks, and the willingness to surface uncomfortable truths your internal team may avoid. That outside perspective is one of the most effective safeguards against cognitive bias.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Jennifer BrazerFounder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.
Everybody loves eating out now and then. When placing an order, the first thing that a customer looks at is the restaurant menu, which is essential when running a food service business. Generally, someone in the restaurant designs the menu and strategizes the dishes according to its theme. Some restaurants serve traditional dishes, so the menu design and theme represents the nature of the restaurant. Simultaneously, some use modern cooking techniques like liquid nitrogen, so the menu is also modern and has a refined look.
A restaurant menu is not just a list of dishes and their prices that a restaurant is serving. According to consulting companies, the menu represents the restaurants’ personality and the food they are serving. The menu usually focuses on highlighting the top-selling dishes to attract more customers.
There are different hacks that a restaurant uses to make us order more from them.
Use of technology
Technology has taken over the entire food industry. Restaurants get more revenue when they establish their identity online. The convenience offered by technology makes us less attentive to the things we purchase. Ordering food online allows restaurants to benefit from customers’ disbursal habit and results in getting more orders from a single customer. Because the ordering is easy, the consumer makes the mistake of ordering unnecessary items from the menu. Restaurants try to make it easier to order food with the touch of a fingertip, and often one does not even notice how much they are spending.
The Golden Triangle
Take a look at any restaurant’s menu. They all have a golden triangle. It comprises of
The middle zone of the menu
The upper right corner
The left corner
This is called a golden triangle. This area of the menu is expertly designed and used by many restaurants. Menu engineers put the most profitable dishes in this area.
Restaurants frequently work to improve the golden triangle of their menu to ensure profitability. The golden area of a menu can have more than one dish.
Color theme: Colors and designs are used in psychology. Color stimulates the brain and can play a part in creating and setting your mood. Successful restaurants utilize this psychology to enrich their business by designing menus with different colors to appease the senses. Here is how restaurants use color to entice customers to order more. Green color makes the customer feel fresh and reminds them of fresh green vegetables. The orange color is considered a funky color and is the color of most savory dishes. It automatically stimulates and triggers appetite and makes the customer order more than they can consume. Also, color stimulates the brain by increasing its oxygen supply. Orange is also associated with healthy food. Yellow brings satisfaction. It makes people feel happy and contended. It is an attractive color and is used in the menu to grab the customer’s attention. Red color attracts customers as it is very noticeable. The items that are listed in red color are generally ordered more than other dishes.
Mentioning price on the menu: Pricing the menu is the key to generate business in the food industry. It is essential to display pricing correctly and strategize how it is mentioned on the menu.
Putting prices in words: Some restaurants have adopted this technique. They have started mentioning price in words rather than digits because showing digits makes the price look higher. When prices are mentioned in words (for example, fifteen dollars rather than $15), the diners are likely to spend more. Another pricing strategy is to show the pricing as one or two cents less than the rounded number (for example, $9.99 instead of $10). This is psychological pricing and is a tactic that has been used by businesses for decades.
Placing items on the menu: Restaurants often use psychology when deciding where to place dishes. They place overpriced dishes on their menu despite their availability. This makes diners perceive that other items are cheaper, so they order them more. For example, a tenderloin steak is priced at $29, and other steaks are $22 (which is not less expensive itself). The diners will opt for other steaks rather than ordering the tenderloin steak.
Conclusion
While many aspects of the restaurant business are essential, psychology is heavily employed to maximize sales during the customer experience. Servers can also utilize psychology to increase sales, but the menu can boost sales by proper design, color, wording, and pricing strategies. Take all these factors into account when designing your restaurant menu.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.






 About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.