Consolidated Accounting Statements

Perfecting Consolidated Accounting Statements with QuickBooks

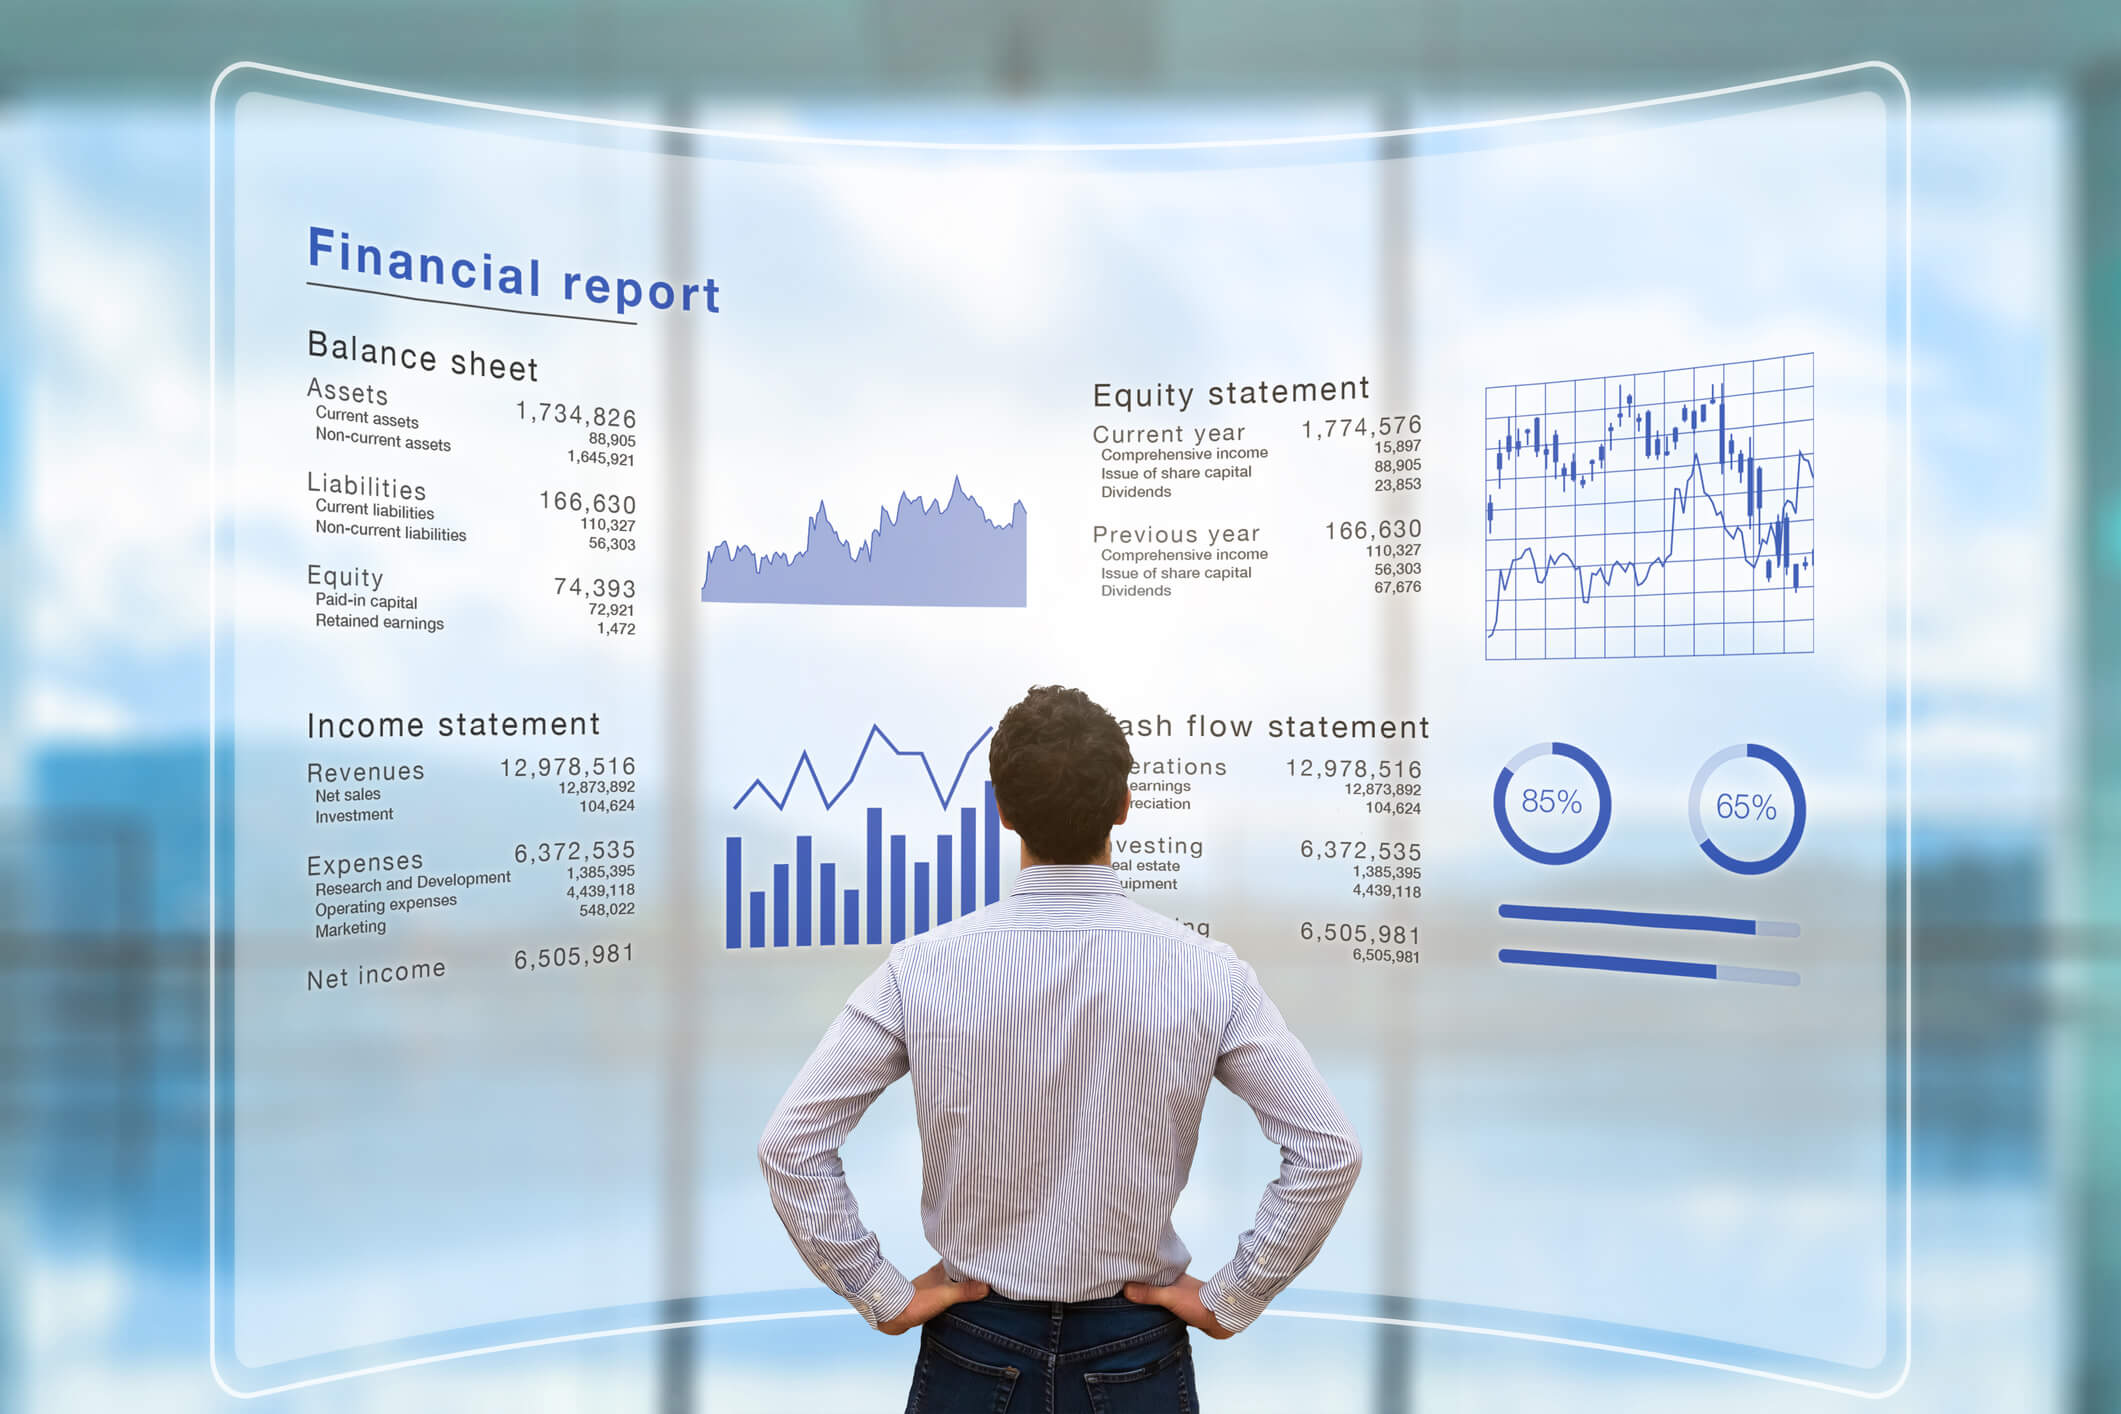
Consolidated Accounting Statements combine the assets, liabilities, equity, income, expenses, and cash flows of a parent company and its subsidiaries into one unified set of financial reports, and QuickBooks helps you get there by pulling data from multiple company files, standardizing charts of accounts, eliminating intercompany transactions, and generating group-level reports—often with the help of Excel or a third-party consolidation tool. Done right, this process treats your entire business as a single economic entity, streamlines financial reporting, reduces manual errors, and gives stakeholders a clear picture of group performance.

In my 20+ years leading Complete Controller, I’ve had the privilege of guiding hundreds of multi-entity businesses through the consolidation process—from family-owned holding companies to fast-growing SMEs juggling a dozen QuickBooks files. Here’s the truth I’ve learned: consolidation is the tipping point between “barely keeping up” and “running a truly scalable business.” In this article, I’ll walk you through what consolidated statements really are, how QuickBooks supports them, a step-by-step playbook to prepare them, common pitfalls to avoid, and a real-world case study showing what’s possible when it’s done right.

What are consolidated accounting statements with QuickBooks and how do you get them right?

  • Consolidated accounting statements combine multiple QuickBooks company files into one set of group-level financial reports, using aligned charts of accounts, intercompany eliminations, and proper consolidation adjustments.
  • They present the parent and all subsidiaries as a single economic entity across the balance sheet, income statement, cash flow, and equity statements.
  • QuickBooks Desktop Enterprise offers built-in “Combine Reports from Multiple Companies,” while QuickBooks Online typically requires third-party apps or spreadsheet workflows.
  • Accuracy depends on a standardized chart of accounts, disciplined intercompany reconciliation, and clear policies for adjustments and disclosures.
  • When implemented well, consolidated statements support IFRS/GAAP compliance and give leaders faster, more reliable visibility for decisions. CorpNet. Start A New Business Now

What Are Consolidated Accounting Statements and Why They Matter for QuickBooks Users

Consolidated Accounting Statements pull together the finances of a parent company and all its subsidiaries into a single set of reports, adjusted to remove internal transactions so the group’s numbers reflect only dealings with external parties. For QuickBooks users running several company files, this is how you move from siloed entity reporting to a true group view.

Definition and core components

Consolidated financial statements present a group—a parent and its subsidiaries—as though they were one economic entity.

  • Core components include a consolidated balance sheet, income statement, cash flow statement, statement of changes in equity, and explanatory notes.
  • Group accounting focuses on recognizing control, measuring investments in subsidiaries, and combining like items across entities.

When and why you must prepare consolidated accounting statements

Under IFRS 10, a parent must consolidate when three conditions are met: (1) it has power over the investee, (2) it’s exposed to variable returns from that investee, and (3) it can use its power to affect those returns. That three-part test is a clean gut-check for owners before they ever touch QuickBooks.

For QuickBooks users, consolidation becomes essential when lenders, investors, or boards need group-level reporting instead of stand-alone entity statements—or when you simply want a holistic view of performance and risk.

How QuickBooks Supports Consolidated Accounting Statements in Practice

QuickBooks doesn’t natively deliver full IFRS/GAAP consolidation across every version, but it provides the essential building blocks: separate company files, standardized charts of accounts, built-in combined reports in certain editions, and strong integration options.

QuickBooks desktop enterprise and multi-company reporting

Intuit confirms you can “Combine reports from multiple companies” in QuickBooks Desktop Enterprise—as long as the files share the same chart of accounts. Combined report options include Profit & Loss and Balance Sheet, which reinforces why standardizing accounts is step one.

  • Run standard reports per entity, then combine them.
  • Export to Excel for adjustments, eliminations, and formatting.

Intuit enterprise suite and multi-entity overview

Intuit’s Enterprise Suite and multi-entity dashboards let you view consolidated P&L, sales, expenses, A/R, and A/P across selected entities with configurable date ranges and KPI widgets—useful for executive-level financial reporting.

QuickBooks Online and third-party tools

QuickBooks Online lacks fully native consolidated financial statements, so most teams use a hybrid workflow:

  1. Set up separate company files for each entity.
  2. Align charts of accounts.
  3. Export reports to Excel or Google Sheets.
  4. Map accounts, reconcile intercompany balances, and eliminate.

Tools like Coefficient or dedicated consolidation platforms can automate the data pulls, mapping, FX adjustments, and eliminations.

Managing multiple entities is complicated enough. Your accounting doesn’t have to be. Complete Controller can help simplify your financial reporting, organize your books, and give you a clearer view across your business. See how Complete Controller can help.

Step-by-Step: How to Prepare Consolidated Accounting Statements with QuickBooks

Here’s the practical roadmap I walk clients through.

Step 1 – Design your group accounting framework

Before opening QuickBooks, define the group:

  • Identify the parent and every subsidiary based on control criteria.
  • Set a reporting currency, fiscal year-end, and accounting policies (revenue recognition, depreciation, inventory).
  • Establish rules for intercompany transactions, loans, and dividends.

Step 2 – Standardize charts of accounts

Consolidation depends on comparability. Create one master chart of accounts each QuickBooks file will mirror. Map any legacy accounts to the master structure so account-level roll-up is clean. This is non-negotiable for a smooth bookkeeping and accounting services workflow.

Step 3 – Extract entity-level financials

For each entity, run the P&L, Balance Sheet, Cash Flow, and Trial Balance. Export to Excel, Google Sheets, or your consolidation tool using consistent periods and filters.

Step 4 – Intercompany reconciliation and eliminations

Intercompany eliminations are the heart of accurate consolidation.

  • Reconcile intercompany receivables/payables and internal sales.
  • Eliminate intragroup balances, income, expenses, and cash flows.
  • Remove unrealized profits on inventory or fixed asset transfers.
  • Offset the parent’s investment in each subsidiary against that subsidiary’s equity.

Step 5 – Compile, review, and disclose

Aggregate the remaining external transactions into the four consolidated statements, then add notes on accounting policies, group structure, and intragroup relationships per IFRS 10.

Advanced Consolidation Adjustments and Compliance

Beyond basic combining, most groups need deeper consolidation adjustments.

Common adjustments

  • Foreign currency translation into the parent’s reporting currency.
  • Non-controlling interests when the parent owns less than 100%.
  • Unrealized profit eliminations on intragroup transfers.

Compliance and disclosures

Standards prescribe basis of consolidation, judgments about control, related-party transactions, and segment reporting. Documented processes and audit trails matter—SEC guidance underscores how vital transparency is for investors relying on group-level numbers.

Case Study: Consolidating 15 QuickBooks Companies into One Reporting Platform

A multi-entity business ran 15 separate QuickBooks environments plus ADP data and multiple Google Sheets. Leadership needed consolidated fixed-asset reporting, historical job-cost analysis, and invoice reconciliation across the group. FreedomDev built a synchronization app that pulled every environment into a single reporting platform—delivering true group-level visibility that manual processes could never match.

Takeaways:

  • Scaling from a handful to dozens of entities is possible when QuickBooks connects to a central reporting layer.
  • Intercompany reconciliation must be embedded in the process, not bolted on later.

Real-World Pitfalls (and My Founder’s Playbook to Avoid Them)

Most technical guides stop at “what” and “how.” I focus on making this sustainable.

Where teams slip

  • Misaligned charts of accounts: leads to messy mappings and hidden performance trends.
  • Weak intercompany tracking: forces last-minute manual fixes.
  • Over-reliance on spreadsheets: version control breaks down as you grow.

My first-hand checklist

  1. Start with governance, not software. Clarify structure, policies, and reporting needs first.
  2. Standardize relentlessly. One chart of accounts, consistent posting practices, always.
  3. Bake in intercompany discipline. Treat reconciliation as a monthly must-have.
  4. Automate where errors cluster. Use integrations to eliminate the human slip-ups.

For deeper reading, Investopedia’s overview offers a helpful conceptual refresher, and our team also publishes ongoing financial reporting insights tailored to SME leaders.

Conclusion: Bringing It All Together

Consolidated Accounting Statements with QuickBooks are absolutely achievable when you set up disciplined company files, standardize your chart of accounts, sync data into a central layer, handle intercompany eliminations with care, and produce group-level reports stakeholders can trust.

The real win isn’t just “getting a consolidated report.” It’s building a repeatable, compliant process that turns multi-entity complexity into clear, timely insight you can act on. When you’re ready to streamline consolidation, reduce errors, and reclaim serious time, visit Complete Controller for expert support in designing and implementing a QuickBooks-based consolidation strategy tailored to your business. Download A Free Financial Toolkit

Frequently Asked Questions About Consolidated Accounting Statements

What are consolidated financial statements?

Consolidated financial statements present the assets, liabilities, equity, income, expenses, and cash flows of a parent and its subsidiaries as one economic entity, with all intragroup transactions and balances eliminated.

How do I create consolidated financial statements in QuickBooks Online?

QuickBooks Online doesn’t offer fully native consolidation. Most teams export reports from each company file and combine them in Excel, or integrate a third-party consolidation app that connects to multiple QBO instances.

What is multi-entity reporting in QuickBooks?

It’s the ability—strongest in Desktop Enterprise and Intuit’s Enterprise Suite—to combine or view P&L, balance sheet, cash flow, and trial balance across multiple company files in one consolidated dashboard.

What are consolidated reports for multiple companies?

Combined QuickBooks reports (consolidated P&L, balance sheet, cash flow, check detail, trial balance) that present financial data from several company files in a unified format for group-level analysis.

Are consolidated financial statements required under IFRS?

Yes. Under IFRS 10, a parent that controls one or more subsidiaries generally must present consolidated financial statements, subject to limited exceptions.

Sources

Complete Controller. America’s Bookkeeping Experts About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.

author avatar
Jennifer Brazer Founder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Reviewed By: reviewer avatar Brittany McMillen
reviewer avatar Brittany McMillen
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.

Cloud Based Accounting Software

Cloud Based Accounting Software:
5 Benefits for SMBs

Cloud based accounting software helps small and mid-sized businesses manage finances in real time, automate routine bookkeeping, collaborate securely with advisors, and access financial data from any device, anywhere. For a founder-led SMB, it is one of the fastest ways to cut manual work while gaining the visibility, control, and confidence needed to make smarter daily decisions.

Here is what convinced me to build my entire firm around this model: in a 2024 Intuit QuickBooks small business survey, 63% of small businesses reported using accounting software—cloud tools are now the baseline, not the upgrade. Over 20 years leading Complete Controller, I have had the privilege of guiding thousands of SMBs across nearly every industry through this exact shift, and I can tell you the ones that win treat cloud accounting as a business transformation, not a software swap. In this article, I will walk you through the five biggest benefits, share a proven transition roadmap, and give you the real-world insights you need to move forward with clarity.

What is cloud based accounting software and how do you know if it is right for your SMB?

  • Answer: Cloud based accounting software is subscription-based, internet-delivered accounting that stores data on secure remote servers, updates automatically, and gives SMBs anytime access, automation, and multi-user collaboration.
  • Anytime access: Owners, staff, and advisors can log in from any device, which supports remote work and faster decisions.
  • Automation built in: Bank feeds, recurring invoices, and reminders reduce manual entry and human error.
  • Team-friendly: Multiple users can work in the same live file, eliminating version conflicts.
  • Scalable and predictable: Subscription pricing replaces heavy upfront hardware and license costs. Cubicle to Cloud virtual business

Real-Time Access Gives SMB Owners Better Financial Control

Cloud accounting delivers something desktop tools simply cannot: live visibility into cash flow, receivables, payables, and profitability the moment a transaction posts. That means you stop waiting for a month-end report to find out what already happened.

At Complete Controller, this is often the single biggest behavior change I see. Once owners can check the numbers before approving a hire, a purchase, or a new lease, they stop guessing and start managing.

User accounting dashboard for faster oversight

A centralized user accounting dashboard puts owners, managers, and bookkeepers on the same page—literally. Everyone sees the same numbers, which cuts down on version confusion, delayed approvals, and second-guessing.

Automation Cuts Busywork and Reduces Errors

Cloud systems automate the tasks that quietly drain your week: transaction imports, recurring entries, invoice reminders, and scheduled reports. The payoff is time and accuracy.

Most SMBs underestimate how much labor they lose to “small” manual tasks until they see the savings on paper. Automation is usually where the first measurable ROI shows up.

  • Automated bookkeeping cuts data entry so your team can focus on review and analysis
  • Bank reconciliation becomes faster because feeds flow directly into the system
  • Invoice management improves with fewer missed or duplicate entries
  • Billing and invoicing automation sends recurring invoices and reminders on autopilot, protecting cash flow

If you want a deeper look at how automation transforms daily workflows, our team at Complete Controller works with clients on this every day.

Secure Data Access Helps SMBs Work Anywhere Without Losing Control

Security is where most owners pause—and rightly so. Leading cloud vendors provide encryption, automatic backups, multi-factor authentication, and managed uptime that most small businesses simply cannot match on their own hardware. For current guidance on protecting your systems, the CISA Cyber Threats and Advisories resource is a smart bookmark.

Secure document storage for financial records

Secure document storage keeps receipts, statements, and supporting files organized, permissioned, and recoverable in one place. Combined with real-time expense tracking from any device and cleaner payroll reporting, your entire financial workflow becomes both mobile and defensible.

The practical habits matter as much as the technology: role-based access, strong passwords, and a quarterly review of who can see what.

Collaboration Improves When Your Accountant, Bookkeeper, and Team Share One System

Cloud accounting gives owners, staff, and outside advisors simultaneous access to the same live records. That means no more emailing spreadsheets back and forth, no more “which version is current,” and no more waiting on someone to send the file.

Founder-led firms especially benefit here. When your advisor sees exactly what you see, the conversation shifts from data cleanup to strategic guidance.

Small business bookkeeping software built for teamwork

Modern small business bookkeeping software is designed for shared access from day one. Add in accounts receivable automation to shorten your collections cycle, and connect a Xero integration or app marketplace to layer in payments, CRM, and expense tools. The result is a connected financial stack that grows with you.

Cloud Based Accounting Software Can Lower Costs and Scale With Growth

Cloud systems replace heavy upfront hardware and license costs with predictable monthly pricing—but the real savings run deeper. A Forrester study commissioned by Microsoft found SMB cloud migrations delivered an average 245% ROI over three years with a payback period of less than six months.

That is the total cost of ownership story: less IT maintenance, fewer errors, faster monthly close, and easier scaling.

QuickBooks alternative options and GAAP-compliant reporting

A QuickBooks alternative may fit better if you need different features, pricing, or workflows. Whichever platform you choose, GAAP-compliant reporting supports cleaner financial statements—critical when you are courting investors, lenders, or acquirers. Cloud tools scale by adding seats and integrations, not servers.

How to Transition Your Business to Cloud Accounting Without Disruption

A successful move to cloud accounting is a process, not a switch. Here is the roadmap I recommend to every client:

  1. Clean up your current books — resolve open balances, duplicate vendors, and uncategorized expenses first
  2. Map your core workflows — document how invoicing, bill pay, payroll, and month-end close happen today
  3. Assign one internal owner and one accounting partner — clear ownership prevents missed steps
  4. Train your team on access and approvals — set permissions before go-live
  5. Run parallel checks for one or two cycles — compare cloud reports to your old system until numbers match

The Human Side of Letting Software Handle the Routine Work

Automation is powerful, but it is not a replacement for judgment. Software handles the repetitive work beautifully—categorization, reminders, reconciliation—but humans still need to review exceptions, interpret trends, and set policy.

Compliance risk grows when businesses over-automate approval controls, tax treatment, or reporting consistency. The best results come when your platform handles the routine and your people handle the strategy. That balance is what protects both your numbers and your reputation.

Real-World Case Study: Cloud Accounting in Practice

The accounting firm PM+M documented a client who moved to cloud accounting and gained faster invoice production, automatic posting of customer payments, and the ability to approve invoices from a phone. Cash flow visibility improved almost immediately.

A similar story appears in the SBA’s New England Brewing Company profile, where cloud tools helped the owner stay on top of operations and financials during a growth phase. The lesson is consistent: cloud accounting delivers the most value when it removes friction from collections, sharpens cash visibility, and follows the owner wherever the business goes.

Final Thoughts

Cloud based accounting software gives SMBs five clear wins: real-time access, automation, secure collaboration, better teamwork, and lower long-term costs. In my two decades leading Complete Controller, the businesses that thrive with cloud accounting treat it as a process upgrade—paired with clean books, clear permissions, and one trusted system of record.

If you are ready to modernize with confidence, visit Complete Controller to see how our team helps SMBs transition, optimize, and scale their financial operations. Complete Controller. America’s Bookkeeping Experts

Frequently Asked Questions About Cloud Based Accounting Software

What is cloud based accounting software?

It is online accounting software that stores your financial data on secure remote servers and lets you access it from any device with an internet connection.

Is cloud based accounting software secure?

Yes. Leading providers use encryption, automatic backups, multi-factor authentication, and controlled user access—often stronger than what SMBs can build in-house.

How does cloud based accounting software help small businesses?

It saves time through automation, improves accuracy, makes collaboration easier with advisors, and gives owners real-time data to make faster decisions.

Can cloud based accounting software replace desktop accounting software?

For most SMBs, yes. It offers remote access, automatic updates, easier collaboration, and lower total cost of ownership than traditional desktop tools.

What is the best cloud based accounting software for SMBs?

The best fit depends on your size, budget, workflows, and integration needs. Popular options include QuickBooks Online, Xero, FreshBooks, Zoho Books, and NetSuite.

Sources

CorpNet. Start A New Business Now About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
author avatar
Jennifer Brazer Founder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Reviewed By: reviewer avatar Brittany McMillen
reviewer avatar Brittany McMillen
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.

Interpret Accounting Statements

Interpret Accounting Statements:
Essential For Entrepreneurs

Interpret accounting statements by reading your income statement, balance sheet, and cash flow statement together every month to see how profitable you are, what you own and owe, and whether you have enough real cash to run and grow your business. When you build this habit, you catch shrinking margins, tight liquidity, and negative operating cash flow early—so you can make smarter, faster decisions about pricing, spending, hiring, and financing before small issues become emergencies.

After more than two decades leading Complete Controller and working shoulder-to-shoulder with thousands of small and midsize business owners, I can tell you this: most founders don’t need more data—they need a simple, repeatable way to turn financial reporting into daily decisions. Consider this: the U.S. Bureau of Labor Statistics reports that about 20% of new businesses fail in their first year, and roughly 50% fail by year five. In this article, I’ll show you the exact monthly routine, ratios, and mindset shifts my team uses to help founders read their numbers with clarity, confidence, and courage—no CPA license required.

What are accounting statements and how do you interpret them to run your business confidently?

  • Accounting statements are standardized reports—income statement, balance sheet, and cash flow statement—that reveal profitability, financial position, and cash movement so you can make confident business decisions.
  • The income statement shows whether you made a profit this period, highlighting revenue, expenses, and margins critical to pricing and cost control.
  • The balance sheet shows what you own, what you owe, and what’s left for you (equity), revealing liquidity, leverage, and long-term stability.
  • The cash flow statement shows where cash came from and where it went, so you know if your business can pay its bills and fund growth.
  • Interpreting accounting statements means tying all three reports together using ratios, trends, and benchmarks that turn static numbers into action. ADP. Payroll – HR – Benefits

The Essential Accounting Statements Every Entrepreneur Must Understand

Accounting statements are formal records that summarize your company’s financial performance and position. For entrepreneurs, three core reports—income statement, balance sheet, and cash flow statement—form the foundation of meaningful financial reporting.

Each report answers a different question, and together they tell your business’s full story. Skip one, and you’re guessing.

Income statement – Your profitability scorecard

The income statement reports revenue, expenses, and profit over a specific period. It answers the simplest, most important question: did we make money?

Key lines to track:

  • Revenue trends: growth, flat, or decline versus prior periods and budget
  • Gross margin: whether your core operations are truly profitable
  • Operating expenses: spotting spending that outpaces revenue
  • Net income: the bottom line—but never the whole story without cash context

Balance sheet – What you own and owe

The balance sheet captures assets, liabilities, and equity at a fixed point in time, following the equation: Assets = Liabilities + Equity. A quick way to interpret accounting statements is to watch your current ratio (current assets ÷ current liabilities). According to the Corporate Finance Institute, a current ratio below 1.0 can signal liquidity trouble—meaning you may not have enough short-term assets to cover short-term bills.

Balance sheet analysis for entrepreneurs comes down to three moves:

  1. Compare current assets to current liabilities for liquidity risk
  2. Track debt-to-equity to see how aggressively you’re financing growth
  3. Watch equity trends to confirm owner value is building, not draining

For a deeper dive into liquidity health, review Complete Controller’s guide on how to ensure an ideal liquidity position.

Cash flow statement – Your real-world cash reality

The cash flow statement splits into three sections: operating, investing, and financing. Positive net income with negative operating cash flow often signals collections issues, inventory bloat, or aggressive revenue recognition.

Here’s a sobering example: in 2015, electronics retailer RadioShack filed for bankruptcy after reporting a net loss of about $161 million with just $62 million in cash on hand, according to Reuters. Losses and weak cash can collide fast—and they end businesses. Learn more from Investor.gov’s overview of the cash flow statement.

How to Interpret Accounting Statements Step-by-Step

Most entrepreneurs treat financial statements like a homework assignment—something to file away, not something to act on. A structured monthly review flips that script and turns interpretation into a habit that drives real decisions.

A 60-minute monthly financial review routine

Here’s the sequence I coach founders through:

  1. Gather your three statements for the current month, plus the same month last year and year-to-date
  2. Read the income statement first—flag any line that moved more than 10–15%
  3. Analyze the balance sheet—compute your current ratio and scan receivables
  4. Evaluate cash flow—confirm operating cash flow is positive and covers obligations
  5. Tie it all together—document 3–5 action items tied to pricing, spending, hiring, or financing

Reconciled books are the fuel for this routine. If your data isn’t clean, your interpretation won’t be either—here’s why reconciling your accounting statements regularly matters so much.

Ratios and benchmarks without the overwhelm

Focus on a small, powerful set:

  • Liquidity: current ratio, quick ratio
  • Profitability: gross margin, net margin, return on equity
  • Leverage: debt-to-equity, interest coverage

Compare each to your own history and industry benchmarks. Multi-period trends beat single-month snapshots every time.

Turn your financial statements into smarter business decisions with expert bookkeeping and real-time financial clarity from Complete Controller.

Turning Financial Reporting Into Smart Decisions

Interpreting accounting statements only matters if it changes what you do next. That’s where statement analysis becomes founder strategy.

Pricing, costs, and profitability moves

If gross margin drops, review pricing, discounts, and input costs immediately. If operating expenses grow faster than revenue, cut strategically—target the specific categories bloating your P&L rather than making across-the-board reductions that starve growth areas.

Cash, debt, and growth moves

Stable operating cash flow gives you permission to hire, market, and expand without leaning too hard on debt. A weak current ratio combined with rising short-term liabilities is your signal to restructure debt, pause capital spending, or shorten your cash conversion cycle before liquidity becomes a crisis.

Making Sense of GAAP, IFRS, and Accounting Jargon

Accounting statements are prepared under GAAP in the U.S. and IFRS internationally. These frameworks affect how revenue, leases, and inventory show up on your reports—which affects how you interpret them.

You don’t need to memorize the rulebooks. You do need to understand a few concepts that reshape the story your numbers tell.

Concepts that change how you read your statements

  • Accrual vs. cash basis: Accrual records revenue when earned; cash basis records it when money moves. The difference explains why profit and cash rarely match.
  • Depreciation and non-cash items: These hit net income but don’t touch cash. Separate operating performance from accounting adjustments when judging profitability.
  • Footnotes and MD&A: Policies, risks, and debt covenants live here. Skipping them means missing half the story.

A Practical Numbers-Habits System

Over the years, I’ve watched founders go from dodging their statements to leading investor conversations with poise. The turning point is never a course or a certification—it’s a simple, consistent routine. Here’s the 90-day plan I recommend.

Your 90-day financial clarity plan

  1. Days 1–30: Get your bookkeeping current and reconciled; confirm all three statements produce monthly
  2. Days 31–60: Block a recurring 60-minute review; define 3–5 core metrics (revenue growth, gross margin, current ratio, operating cash flow)
  3. Days 61–90: Link each metric to a specific decision and build a one-page dashboard for your leadership team

Confidence, not shame

Numbers are feedback, not judgment. Bring your bookkeeper or controller into the review and ask “why” until every major change makes sense in plain language. That’s how founders stop fearing the reports and start using them as a compass.

Final Thoughts: Read Your Numbers, Steer Your Business

When you consistently interpret accounting statements through a simple monthly rhythm, you stop flying blind and start leading with clarity. You’ll spot margin compression early, notice liquidity tightening before payroll is at risk, and know exactly when growth has earned the right to more hiring or financing.

I don’t review our financials to check a box—I use them as a conversation starter with my team: What changed? Why? What are we doing about it? That discipline has carried Complete Controller through growth spurts, downturns, and pivots with far more confidence than gut instinct ever could. If you want help installing this kind of numbers-driven system in your business, visit Complete Controller to explore how our cloud-based bookkeeping and advisory services can build a decision-ready company alongside you. Complete Controller. America’s Bookkeeping Experts

Frequently Asked Questions About Interpret Accounting Statements

What are the three main accounting statements every entrepreneur should understand?

The three core accounting statements are the income statement, balance sheet, and cash flow statement. Together they show profitability, financial position, and cash movement—the full picture of business health.

How often should small business owners review their financial statements?

Entrepreneurs should review all three statements at least monthly, comparing results to prior periods, budget, and key ratios so you can act on trends before they become emergencies.

What’s the difference between profit on the income statement and cash on the cash flow statement?

Profit reflects revenue and expenses under accrual accounting, while cash flow shows actual money in and out. A business can be profitable on paper and still run out of cash if collections, inventory, or financing aren’t managed well.

Which ratios are most important when interpreting accounting statements?

Focus on the current ratio and quick ratio for liquidity, gross margin and net margin for profitability, and debt-to-equity for leverage. These few ratios put raw numbers into meaningful context.

Do I need to understand GAAP or IFRS to interpret my company’s accounting statements?

You don’t need to be an expert, but a working knowledge of GAAP or IFRS—especially around revenue recognition, leases, and inventory—helps you interpret statements accurately and compare your results to peers and investors.

Sources

CorpNet. Start A New Business Now About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
author avatar
Jennifer Brazer Founder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Reviewed By: reviewer avatar Brittany McMillen
reviewer avatar Brittany McMillen
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.

Best Business Books Entrepreneurs Read

Best Business Books for Entrepreneurs & Professionals

The best business books entrepreneurs professionals should read are the ones that help you think clearly, build better systems, lead people well, and make sharper decisions under pressure—starting with The Lean Startup, The E-Myth Revisited, The 7 Habits of Highly Effective People, Good to Great, and High Output Management. For founders and working professionals alike, the strongest reading list blends entrepreneurship, leadership, productivity, business strategy, and financial literacy—rather than leaning too heavily on any single category.

I’m Jennifer Brazer, and after more than 20 years building Complete Controller into a nationwide cloud-based bookkeeping and accounting service, I’ve watched thousands of businesses rise and fall across nearly every sector you can name. The pattern is clear: books that actually move the needle are the ones you apply immediately, not the ones collecting dust on a shelf. In this article, I’ll walk you through the titles that create real change, why they matter at different business stages, and how to build a reading plan that turns pages into profit, promotions, and peace of mind.

What are the best business books for entrepreneurs and professionals?

  • The best business books for entrepreneurs and professionals are practical, repeatable, and relevant to both growth and execution.
  • For most readers, the strongest starting points are The Lean Startup, The E-Myth Revisited, The 7 Habits of Highly Effective People, Good to Great, and High Output Management.
  • If your focus is scaling or management, choose books that match your current business stage and daily decisions.
  • If your focus is career growth, prioritize books on productivity, communication, and influence.
  • The best reading list is not the longest one—it’s the one you can turn into habits, systems, and measurable results. Complete Controller. America’s Bookkeeping Experts

Best Business Books Entrepreneurs Professionals Should Read First

Every strong reading list starts with a foundation of five books that cover the essentials: experimentation, structure, habits, leadership, and management. These titles keep appearing on top business-book roundups because they solve the problems every founder and professional will eventually face.

  • The Lean Startup by Eric Ries — validated learning, fast testing, and reducing waste.
  • The E-Myth Revisited by Michael E. Gerber — turning a founder-dependent business into a system-driven one.
  • The 7 Habits of Highly Effective People by Stephen R. Covey — the foundation for personal effectiveness and leadership.
  • Good to Great by Jim Collins — disciplined execution, culture, and long-term performance.
  • High Output Management by Andrew S. Grove — practical operating discipline for managers and founders.

Why these books keep appearing on top business-book lists

Consider the stakes: about 20% of new businesses fail in the first year, and roughly 50% don’t survive past year five, according to the U.S. Bureau of Labor Statistics. That’s exactly why books focused on systems, execution, and repeatable processes—like The E-Myth Revisited and High Output Management—belong at the top of your list. They teach you to build a business that doesn’t depend on heroics.

Which Business Books Help with Entrepreneurship, Strategy, and Scaling?

Strategy books earn their place when they help you see around corners. The right pick depends on whether you’re validating an idea, differentiating in a crowded market, or scaling a proven model.

Business strategy books for scaling companies

  • Good to Great — what separates durable companies from average ones.
  • Zero to One by Peter Thiel — building something differentiated instead of copying competitors.
  • Blue Ocean Strategy — positioning and market creation.
  • The Lean Startup — testing ideas without overbuilding.
  • The E-Myth Revisited — repeatable systems for growing operations.

A quick cautionary tale: in 2000, Blockbuster had roughly 9,000 stores. By 2010, it had filed for bankruptcy as streaming rewrote the rules. That’s why strategy books about differentiation and market shifts aren’t optional—they’re insurance against becoming the next case study.

Best Books for Entrepreneurs Building from Scratch

  • The Lean Startup — validate before you invest.
  • The E-Myth Revisited — avoid becoming the bottleneck in your own company.
  • Zero to One — think originally, build defensibly.
  • Shoe Dog by Phil Knight — a founder’s raw story that normalizes the struggle.
  • The Hard Thing About Hard Things by Ben Horowitz — the emotional reality of leading through uncertainty.

A Founder Lesson from Complete Controller

From my seat watching small business finances up close, I’ve noticed something: many founders devour strategy books but underinvest in fundamentals like cash flow visibility and process documentation. A great reading list should help you think like a leader and run a tighter operation—see our cash flow management resources for the operational side.

Best Business Books for Leadership Development and Career Growth

Leadership books matter most when they change how you show up on Monday morning. The strongest ones give you frameworks for trust, communication, and delegation that you can use immediately.

Leadership and Management Books for Business Owners

  • High Output Management — how managers create leverage through structure.
  • Leaders Eat Last by Simon Sinek — trust, culture, and team loyalty.
  • Start with Why by Simon Sinek — mission and alignment.
  • The 7 Habits of Highly Effective People — self-management before people-management.
  • Dare to Lead by Brené Brown — feedback, vulnerability, and modern leadership.

Professional Development and Career Growth Reads

  • The 7 Habits of Highly Effective People — sharper habits, better decisions.
  • How to Win Friends and Influence People by Dale Carnegie — timeless communication.
  • Atomic Habits by James Clear — practical behavior change.
  • Deep Work by Cal Newport — focused performance in knowledge work.
  • Thinking, Fast and Slow by Daniel Kahneman — bias and better judgment.

Professionals often get the biggest career lift from books that sharpen prioritization, reliability, and communication. Those skills change how you lead meetings, handle conflict, and earn trust—which usually matters more than another motivational read.

Turn great business ideas into stronger financial decisions with expert bookkeeping and real-time financial clarity from Complete Controller.

Business Fundamentals Every Entrepreneur Should Understand

Financial literacy is the quiet superpower behind every well-run company. You can have the vision of a poet, but if you don’t understand margins, burn rate, and forecasting, the numbers will eventually win the argument.

Best Books for Decision Making and Execution

  • Thinking, Fast and Slow — bias and decision quality.
  • The Checklist Manifesto by Atul Gawande — process discipline and fewer avoidable mistakes.
  • The Effective Executive by Peter Drucker — prioritization and effectiveness.
  • Measure What Matters by John Doerr — goal setting and OKRs.
  • Essentialism by Greg McKeown — focus on what actually matters.

The case for The Checklist Manifesto isn’t theoretical. In a landmark study of surgical teams, a simple checklist reduced major complications from 11% to 7% and cut deaths from 1.5% to 0.8%. Process discipline prevents expensive mistakes—the same principle that separates well-run businesses from chaotic ones.

Why Financial Literacy Belongs on Every Business-Book List

Too many “best business books” articles over-index on motivation and skip the money conversation entirely. For entrepreneurs and professionals alike, financial clarity affects hiring, pricing, and survival. It’s not optional—it’s the scoreboard.

How to Choose the Right Business Books to Read Next

The best business books entrepreneurs professionals recommend won’t help you if you can’t match them to your current challenge. Here’s how to pick with purpose.

Match the Book to Your Business Stage

  1. Validating an idea → The Lean Startup
  2. Building systems → The E-Myth Revisited
  3. Managing people → High Output Management
  4. Improving habits → Atomic Habits or The 7 Habits of Highly Effective People
  5. Sharpening strategy → Good to Great or Zero to One

Build a Reading Plan that Produces Action

  • Choose one book each for entrepreneurship, leadership, and productivity.
  • Take notes only on ideas you can apply in the next 7 days.
  • Convert each book into one process change, one communication change, or one financial habit.
  • Revisit your notes quarterly so the ideas become part of your operating system.
  • Read less for volume and more for implementation.

A Real-World Lesson from Whatfix

Whatfix has been highlighted for tackling employee wellness and organizational growth through practical workplace initiatives, as noted in their HR challenges report. The takeaway for founders: growth isn’t just adding revenue—it’s building leadership habits, team trust, and sustainable systems. That operational thinking is exactly what books like High Output Management and Leaders Eat Last reinforce.

Final Thoughts

If you want the best business books entrepreneurs professionals can actually put to work, focus on titles that improve how you think, lead, and execute—not the ones that just sound impressive at a networking event. After two decades of watching businesses succeed and struggle at Complete Controller, I can tell you the smartest reading list is the one that helps you build stronger systems, make cleaner decisions, and grow with confidence.

Start with one book each in entrepreneurship, leadership, productivity, and business fundamentals. Then turn every book into action inside your company or career. When you’re ready for expert support on the financial and operational side of your business, visit Complete Controller and let our team help you turn insight into results. Cubicle to Cloud virtual business

Frequently Asked Questions About Best Business Books Entrepreneurs Professionals

What is the single best business book for entrepreneurs?

The Lean Startup by Eric Ries is often the best starting point because it teaches testing, validated learning, and reducing waste early—skills every founder needs before scaling.

What are the best business books for professionals focused on career growth?

The 7 Habits of Highly Effective People, Atomic Habits, Deep Work, and How to Win Friends and Influence People are strong choices for building the habits, focus, and communication skills that drive promotions.

Which business books help most with leadership development?

High Output Management, Leaders Eat Last, Dare to Lead, and The Effective Executive are among the most useful leadership books for building trust, structure, and team performance.

What business books help with scaling a company?

Good to Great, The E-Myth Revisited, and Zero to One are strong picks for systems thinking, differentiation, and disciplined execution during growth stages.

How should I choose between all these business books?

Choose based on your current challenge—startup validation, management, productivity, decision making, or financial literacy. The right book at the right time beats the “greatest hits” list every time.

Sources

  • Clear, James. Atomic Habits. Avery, 2018.
  • Collins, Jim. Good to Great. HarperBusiness, 2001.
  • Covey, Stephen R. The 7 Habits of Highly Effective People. Free Press, 1989.
  • Drucker, Peter F. The Effective Executive. Harper & Row, 1967.
  • Gawande, Atul, et al. “A Surgical Safety Checklist to Reduce Morbidity and Mortality in a Global Population.” New England Journal of Medicine, Jan. 29, 2009. https://www.nejm.org/doi/full/10.1056/NEJMsa0810119
  • Gerber, Michael E. The E-Myth Revisited. HarperBusiness, 1995.
  • Grove, Andrew S. High Output Management. Vintage, 1983.
  • Horowitz, Ben. The Hard Thing About Hard Things. Harper Business, 2014.
  • Kahneman, Daniel. Thinking, Fast and Slow. Farrar, Straus and Giroux, 2011.
  • Ries, Eric. The Lean Startup. Crown Business, 2011.
  • Siklos, Richard. “Blockbuster Files for Bankruptcy.” The New York Times, Sept. 23, 2010. https://www.nytimes.com/2010/09/24/business/24blockbuster.html
  • Thiel, Peter, and Blake Masters. Zero to One. Crown Business, 2014.
  • U.S. Bureau of Labor Statistics. “Entrepreneurship and the U.S. Economy — Business Employment Dynamics (BED).” Apr. 25, 2024. https://www.bls.gov/bdm/entrepreneurship/entrepreneurship.htm
  • Whatfix. “Top 21 HR Challenges in 2024 (+Solutions).” Oct. 18, 2022. https://whatfix.com
CorpNet. Start A New Business Now About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
author avatar
Jennifer Brazer Founder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Reviewed By: reviewer avatar Brittany McMillen
reviewer avatar Brittany McMillen
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.

Debt Will Destroy Your Company

Debt Will Destroy Your Company:
Protect Cash Flow Before It’s Too Late

Debt will destroy your company when repayment obligations outrun operating cash, leaving you unable to cover payroll, suppliers, or the everyday costs of running your business. The fix is straightforward but urgent: track liquidity weekly, cut fixed obligations where you can, renegotiate loan terms before you miss a payment, and treat borrowing as a strategic tool rather than a lifeline. Companies rarely collapse from one bad quarter—they collapse when debt service quietly eats the working capital that keeps the lights on.

After more than 20 years building Complete Controller and partnering with thousands of business owners across nearly every sector, I’ve watched this pattern play out too many times to count. Here’s the sobering number that should stop every founder in their tracks: according to a U.S. Bank study, 82% of small businesses fail because of poor cash flow management or a weak understanding of cash flow. Debt accelerates that failure. In this article, I’ll walk you through the warning signs I’ve seen destroy otherwise healthy companies, the ratios you should be watching every week, a 30-60-90 day survival plan, and the exact conversations to have with your lenders before pressure turns into panic. My goal is simple—help you build the financial clarity and cash flow discipline that keeps debt working for you, not against you.

What does “debt will destroy your company” mean, and how do you protect cash flow before it’s too late?

  • Debt will destroy your company when fixed repayment obligations outpace operating cash, choking payroll, inventory, marketing, and growth investment.
  • The real danger isn’t debt itself—it’s corporate debt that grows faster than revenue with no margin for error.
  • A business can slide from stress to business insolvency in weeks when collections slow but lenders still expect payment on schedule.
  • Early protection means catching the cash flow crisis signals before missed payments become default notices or a bankruptcy risk event.
  • The right response usually involves debt restructuring, tighter cash controls, and resetting payment terms before you hit a loan default. LastPass – Family or Org Password Vault

Why Debt Becomes Dangerous So Fast

Businesses rarely fail because of a single loan. They fail because repayment obligations shrink flexibility until the company can’t absorb shocks. Debt is especially dangerous when interest and principal are mandatory, because that reduces cash available for reinvestment, hiring, and customer acquisition.

Debt is also everywhere. The Federal Reserve’s 2023 Small Business Credit Survey found that 54% of employer firms reported debt outstanding, and 35% weren’t fully approved for the financing they needed. That mix forces owners to juggle payables, payroll, and loan payments all at once—a squeeze that breaks even good businesses.

Corporate debt and financial distress

Corporate debt can fuel growth, but it also raises fragility when the business depends on future cash flows that haven’t materialized yet. Financial distress typically appears before insolvency as shrinking margins, increasing borrowing, and stress on supplier relationships.

Interest coverage ratio and debt-to-equity ratio

A weak interest coverage ratio signals that operating profit isn’t comfortably covering interest expense, which increases the chance of a default spiral. A high debt-to-equity ratio stretches the balance sheet and limits your ability to borrow on favorable terms later.

The Warning Signs You Should Not Ignore

Most articles tell you debt is risky. Few give you a real monitoring system. Here’s what to watch every single week.

Signs of financial distress in a company

Common signs of financial distress in a company include:

  • Late vendor payments becoming routine
  • Payroll strain or funding payroll from a credit line
  • Repeated short-term borrowing to cover operations
  • Shrinking cash reserves month over month
  • Missed or delayed tax deposits

Loan default and credit rating downgrade

A loan default often begins with one missed covenant, then escalates through penalties, cross-default clauses, and pressure from multiple creditors at once. A credit rating downgrade raises borrowing costs and makes refinancing harder precisely when you need liquidity most.

Cash flow crisis

A cash flow crisis shows up before your income statement flashes red—especially when sales are booked but cash hasn’t hit the account. That U.S. Bank finding of 82% cash-driven failures makes weekly cash tracking non-negotiable, not optional.

How to Avoid Corporate Insolvency Before Debt Takes Control

How to avoid corporate insolvency comes down to reviewing cash weekly, tightening collections, preserving runway, and renegotiating terms before they break. Waiting is the enemy.

Managing business cash flow under high debt

Managing business cash flow under high debt means prioritizing receivables, cutting discretionary spending, and matching repayment schedules to realistic cash receipts—not hopeful forecasts. If your DSO is creeping up, that’s your earliest warning light.

Strategies for debt restructuring and survival

Strategies for debt restructuring and survival include:

  1. Extending loan maturities to reduce monthly payments
  2. Converting a portion of debt to equity
  3. Selling non-core assets to raise cash
  4. Seeking a formal workout before creditors lose confidence
  5. Consolidating high-interest obligations under better terms

Debt restructuring works best when the business is still viable and can prove that a revised repayment plan is more realistic than liquidation. Lenders would almost always rather restructure than write off.

Get clearer cash flow visibility and expert bookkeeping support to keep business debt from controlling your next move. See how Complete Controller can help.

What a Real Turnaround Looks Like When Debt Is Addressed Early

Consider Toys “R” Us. When the retailer filed for bankruptcy in 2017, it was carrying roughly $5 billion in long-term debt from its leveraged buyout. Bloomberg reporting noted that heavy interest costs limited the company’s ability to invest in stores and compete, and suppliers eventually tightened terms as concerns mounted. Debt service crowded out operations until there was nothing left to save.

Contrast that with a BDO Malaysia restructuring case where a client facing COVID-era cash flow mismatches used a combination of shareholder capital injection, partial repayment, debt waivers, equity settlement, and operational streamlining to successfully exit distress. The difference? Early action. A business with a credible operating model can survive a debt problem if leadership moves fast, aligns repayment with real cash flow, and negotiates transparently.

Where Leaders Make the Wrong Cash Flow Decisions

The biggest bankruptcy risk isn’t one bad quarter—it’s repeated delay in confronting the real numbers until lenders and suppliers force the issue. Founders often assume revenue growth will solve the debt problem. It usually doesn’t.

If leverage is already high, improving the debt-to-equity ratio may require equity injection or deleveraging, not another loan. When debt is heavy, protect cash first and growth second. Otherwise, you may be expanding your way into failure.

A Practical Debt Survival Plan for the Next 30, 60, and 90 Days

Here’s the plan I walk owners through when they call me in the red zone.

30 days: Stabilize

Build a true cash position report, list every debt obligation with terms and due dates, identify the most urgent payments, and freeze all nonessential spending.

60 days: Renegotiate

Renegotiate vendor and lender terms, accelerate collections aggressively, and honestly assess whether the company needs formal debt restructuring or equity support. See the British Business Bank’s guidance for helpful frameworks.

90 days: Rebuild

Reduce dependency on short-term borrowing, rebuild a cash reserve equal to at least one payroll cycle, and formalize a financing strategy that matches actual operating performance.

Track your interest coverage ratio monthly to know whether debt service is improving or eroding resilience. Prevent a credit rating downgrade by paying on time where possible and communicating early—silent defaults destroy lender trust faster than bad news does.

Final Thoughts

Debt will destroy your company if you let repayment obligations outrun cash generation—but that outcome is preventable when you act early, monitor the warning signs, and restructure before your business loses control of its liquidity. Treat cash flow like oxygen. Review debt weekly. Make the hard decisions before lenders or suppliers make them for you.

If you want help building a healthier financial operating system with real-time visibility into your cash, debt, and margins, connect with the experts at Complete Controller. We’ve helped thousands of business owners turn financial confusion into confident decision-making—and we’d love to help you do the same. ADP. Payroll – HR – Benefits

Frequently Asked Questions About Debt Will Destroy Your Company

How does debt actually destroy a company?

Debt destroys a company when fixed repayment obligations reduce operating cash so much that the business cannot pay expenses, invest in growth, or absorb setbacks. The failure usually comes from cash starvation, not the loan balance itself.

What are the earliest signs of debt trouble?

Watch for late supplier payments, rising short-term borrowing, weaker collections, funding payroll from credit lines, and repeated pressure on tax deposits. These typically appear months before a formal default.

Can a company recover from too much debt?

Yes—if it still has a viable business model and acts early enough to restructure obligations before default or insolvency. Lenders almost always prefer restructuring to liquidation when the operating business is sound.

Is debt always bad for a business?

No. Debt can accelerate growth when cash flow can safely service it. It becomes dangerous only when repayments exceed what the business can reliably handle across normal revenue cycles.

What should I do if I think my company is heading toward insolvency?

Review cash immediately, communicate proactively with creditors, cut unnecessary spending, and seek expert restructuring advice before the situation worsens. Speed and transparency are your biggest allies.

Sources

Complete Controller. America’s Bookkeeping Experts About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
author avatar
Jennifer Brazer Founder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Reviewed By: reviewer avatar Brittany McMillen
reviewer avatar Brittany McMillen
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.

IRS Small Business Tax Resources

IRS Small Business Tax Resources:
Key Tips to Know

IRS small business tax resources are the official tools, guides, publications, and online portals the IRS provides to help small business owners understand filing requirements, claim the right deductions and credits, choose the correct business tax forms, and stay compliant year-round. The most valuable ones include the Small Business and Self-Employed Tax Center, Tax Information for Businesses, Publication 334: Tax Guide for Small Business, the Online Tax Calendar, EFTPS for payments, and free IRS online learning workshops—all designed to make filing and paying business taxes simpler and less stressful.

Over 20 years running Complete Controller, I’ve watched thousands of small business owners pay penalties they never should have owed—simply because they didn’t know these free IRS tools existed. In this article, I’m going to walk you through the exact resources my team leans on daily, show you how to match forms to your business type, and share the documentation habits that keep audits manageable. You’ll walk away knowing which deductions are yours for the taking, how to set a bulletproof payment rhythm, and where to get real help when the IRS sends a scary-looking letter.

What are IRS small business tax resources and how do you use them?

  • IRS small business tax resources are official IRS tools, publications, forms, and online centers that help you file correctly, pay on time, and claim legitimate deductions and credits for your small business.
  • The Small Business and Self-Employed Tax Center is your primary hub for filing guidance, recordkeeping standards, and self-employment tax rules.
  • Publication 334 and the Guide to Business Expense Resources explain deductible expenses in plain language with examples.
  • EFTPS, the Online Tax Calendar, and estimated tax pages help you manage payment deadlines and avoid underpayment penalties.
  • Small business online learning, workshops, and the Taxpayer Advocate Service provide ongoing education and real human help when you’re stuck. Complete Controller. America’s Bookkeeping Experts

Your One-Stop Hub: The IRS Small Business and Self-Employed Tax Center

The Small Business and Self-Employed Tax Center is the IRS portal built specifically for businesses with assets under $10 million and taxpayers filing Schedules C, E, F, or Form 2106. Think of it as the front door to every IRS small business tax resource you’ll ever need.

Inside, the content is organized by task so you’re not hunting blindly across IRS.gov:

  • Preparing your taxes — deductions, credits, recordkeeping, employment taxes, and business tax transcripts
  • Filing and paying business taxes — form instructions, past-due returns, and payment tools
  • General topics — gig economy, ACA, retirement plans, and foreign account rules
  • Learning tools — free video lessons and online workshops covering the fundamentals

Small business online learning you can actually use

The IRS offers a full library of free video streaming and classroom-style courses through its Small Business Online Learning hub. These are perfect for new owners who want a plain-language explanation of self-employment tax, hiring employees, or filing Schedule C without paying for a course.

Essential Forms: Matching IRS Business Tax Forms to Your Entity

Choosing the right IRS business tax form is one of the biggest pain points I see with new clients. Filing the wrong form—or missing a required schedule—triggers notices, delays refunds, and racks up penalties fast.

Schedule C, Form 1040, and self-employed silers

Sole proprietors and single-member LLCs report business income on Form 1040 Schedule C: Profit or Loss From Business. This is where you claim your self-employed tax deductions—home office, vehicle mileage, supplies, advertising, and health insurance premiums. Publication 334 is your best friend here; it walks through every deduction line by line.

Corporate and partnership returns

  • Form 1120 — C corporations
  • Form 1120-S — S corporations
  • Form 1065 — partnerships and multi-member LLCs
  • Forms 940 and 941 — employment taxes for any business with employees

The Starting a Business page helps you match your entity type to the right forms before you file. And if you haven’t set up your business yet, our team at Complete Controller recommends nailing down your efficient business finance management system first so tax season is drama-free.

Deductions and Credits: Maximizing Legitimate Tax Savings

Most owners either under-claim deductions out of fear or over-claim without documentation. Both are expensive mistakes. IRS resources give you the exact rules so you can claim confidently.

IRS tax deductions for small businesses

Publication 334 and the Guide to Business Expense Resources cover the deductions every small business should know:

  1. Home office expenses (regular and simplified methods)
  2. Vehicle and mileage costs
  3. Business travel, meals, and lodging
  4. Advertising and marketing
  5. Professional fees, rent, utilities, and insurance
  6. Qualified Business Income (QBI) deduction — up to 20% of qualified income for eligible owners

Practical documentation and risk management

Here’s a truth bomb: The IRS warns that without proper records, you may not be able to prove your deductions and could end up owing extra tax plus penalties and interest. Records must be kept as long as needed to support income or deductions on a return (see the IRS Recordkeeping page).

I’ve watched businesses lose audits not because their deductions were wrong—but because their receipts were a mess. Align your chart of accounts with the categories in Publication 334, keep digital receipts, and log mileage in real time. For more tactical habits, check out our small business bookkeeping tips.

Staying Compliant: Deadlines, Payments, and Extensions

Compliance is about when and how you pay, not just what you file. The IRS gives you free tools to nail both.

IRS quarterly estimated tax payments and the tax calendar

The IRS says you generally need to make estimated tax payments if you expect to owe $1,000 or more when you file. Payments are usually due four times a year—April, June, September, and January (see Estimated Taxes). Miss them and you’ll owe an underpayment penalty on top of your tax bill.

The Online Tax Calendar shows every business due date and can send you email reminders or sync to your calendar app.

IRS tax payment options and extensions

  • EFTPS (Electronic Federal Tax Payment System) — free, traceable, and lets you schedule payments in advance
  • Direct Pay and same-day wire — for one-off payments
  • Form 7004 — extension of time to file (not to pay); use it strategically, not habitually
Tax rules are easier with clean books behind them. Complete Controller helps keep your bookkeeping accurate, organized, and tax-ready. Get your books in shape.

Starting, Running, and Closing a Business: Full Life Cycle Guidance

IRS small business tax resources cover you from day one through your final return.

Gettingyour EIN and setting up right

Most businesses need an Employer Identification Number (EIN)—your federal tax ID. You can apply online in about 10 minutes at IRS.gov. The Starting a Business hub also walks through income tax, employment tax, and excise tax obligations before you open your doors.

Closing cleanly

When it’s time to wind down, IRS “Close a Business” guidance walks you through filing final returns, canceling your EIN, and meeting final employment tax responsibilities—so nothing lingers to haunt you later.

Real-World Case Study: Avoiding Penalties with IRS Resources

A sole proprietor client came to us after receiving a proposed IRS deficiency notice for underreported income and misclassified expenses. Using Publication 334 and the Guide to Business Expense Resources, we recategorized her expenses correctly, prepared amended Schedule C filings, and substantiated every legitimate deduction. Her final penalty was reduced substantially.

Here’s a broader example of why quick action matters: A Treasury Inspector General for Tax Administration (TIGTA) audit found the IRS sent over 5 million math error notices tied to Premium Tax Credit claims—and often didn’t clearly explain next steps to taxpayers. That’s a real-world reminder that when an IRS notice arrives, using official resources and getting help fast prevents small errors from snowballing.

Final Thoughts

The IRS becomes far less intimidating when you treat its small business tax resources as tools instead of threats. Bookmark the Small Business and Self-Employed Tax Center, download Publication 334, sync the Online Tax Calendar to your phone, and set up EFTPS today. Match your bookkeeping categories to IRS guidance, document as you go, and file the right forms for your entity type—that’s the whole game.

Ready to turn IRS guidance into a rock-solid system for your business? Visit Complete Controller for expert cloud-based bookkeeping built for small business tax compliance. Cubicle to Cloud virtual business

Frequently Asked Questions About IRS Small Business Tax Resources

What is the IRS Small Business and Self-Employed Tax Center?

It’s the IRS’s main online hub for small businesses and self-employed taxpayers, offering guidance on preparing, filing, and paying business taxes, plus deductions, credits, and recordkeeping standards.

Which IRS publication should small business owners rely on for deductions?

Publication 334: Tax Guide for Small Business is the go-to resource for Schedule C filers. It explains common deductions, credits, and filing requirements with examples.

Do I really need to make quarterly estimated tax payments?

Yes, if you expect to owe $1,000 or more in tax when you file. Payments are due in April, June, September, and January—miss them and you’ll face underpayment penalties.

How do I apply for an EIN?

Apply free online at IRS.gov through the Get an Employer Identification Number page. Most applicants receive their EIN immediately.

Where can I get free help with a tough IRS tax problem?

Use the Taxpayer Advocate Service, an independent organization within the IRS that helps taxpayers resolve issues they can’t fix through normal channels.

Sources

Download A Free Financial Toolkit About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
author avatar
Jennifer Brazer Founder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Reviewed By: reviewer avatar Brittany McMillen
reviewer avatar Brittany McMillen
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.

Avoid Overcapitalizing Investments

How to Avoid Overcapitalization of Investment Capital

Avoid over capitalization of investment capital by funding only what your business can productively deploy, tying every dollar to a measurable return, and reviewing your capital structure often enough to catch idle cash, excess debt, or oversized equity before it drags down profitability. The practical fix is disciplined capital planning: define the exact amount needed, stage funding in phases tied to milestones, track ROI honestly, and redirect surplus toward debt reduction, higher-yield opportunities, or strategic reserves.

Here’s what I’ve learned after two decades at the helm of Complete Controller: overcapitalization almost always starts with good intentions. Founders raise a “just in case” cushion, then discover that cushion is expensive, idle, and loosely tied to results. Harvard Business Review research from Gray and Kester found that firms holding more cash than they needed earned lower return on assets than similar firms with leaner balance sheets—proof that extra capital is not automatically an asset. In this article, I’ll walk you through how to size your capital correctly, spot early warning signs, apply staged deployment, and use real-world discipline (the kind Apple famously demonstrated) to keep your capital working as hard as you do.

How do you avoid overcapitalization of investment capital?

  • Answer: Fund only the amount needed for your next growth stage, tie each dollar to a defined return, and review whether your capital structure is still earning an acceptable yield.
  • Start with a realistic capital budget based on operating needs, not optimism.
  • Release funding in phases so you can pause or redirect if results underperform.
  • Track capital efficiency using ROI, margins, and asset utilization—not just revenue.
  • Redirect surplus capital toward debt reduction, higher-return projects, or reserves. CorpNet. Start A New Business Now

What Overcapitalization Really Means and Why It Hurts Returns

Overcapitalization happens when a company holds more capital—stock, debt, or cash—than it can efficiently use, so earnings shrink relative to the total funds deployed. In plain terms, the business is carrying too much weight for the return it’s generating, which suppresses profitability and distorts valuation.

The Harvard Business Review study I mentioned earlier makes this concrete: firms with excess cash consistently underperformed peers on return on assets. Idle capital isn’t neutral—it actively drags down performance metrics investors and lenders care about.

Business investment and capital allocation: The core mistake

The most common error I see is treating funding size as a success metric instead of treating capital allocation as the real performance driver. A business can raise a large round and still underperform if that money spreads across low-return projects, slow-moving inventory, or oversized payroll.

How to Build a Business Capital Management Strategy That Prevents Overcapitalization

A strong business capital management strategy starts long before you sign a term sheet or draw on a line of credit. It begins with knowing exactly what the money is for, how fast it can generate returns, and what happens if it doesn’t.

Investment planning and market research before funding

Solid investment planning begins with market research, competitor benchmarking, and honest unit economics. The SBA offers practical guidance on market research and competitive analysis that founders can use to validate demand before overfunding capacity. Overcapitalization often traces back to building ahead of the market rather than with it.

Optimal allocation of capital for growth

To reach the optimal allocation of capital for growth, divide funding into four buckets:

  1. Core operations
  2. Revenue-producing assets
  3. Risk reserves
  4. Strategic experiments

This structure makes it obvious whether money is fueling productive growth or simply inflating the balance sheet.

Reduce excess capital and improve ROI with staged deployment

One of the cleanest ways to reduce excess capital and improve ROI is staged deployment. Instead of committing all funds at once, release capital in tranches tied to specific milestones—revenue targets, utilization rates, or customer acquisition costs. If a milestone slips, you pause. If it hits, you release the next tranche.

Practical Steps to Avoid Over Capitalization of Investment Capital

Discipline is what separates companies that scale profitably from those that scale into trouble. These are the habits I coach founders through most often.

ROI optimization and risk management

Every material use of capital should be tested against expected payback, margin improvement, or risk management value. If a project can’t show credible upside within a reasonable window, scale it back or delay it.

Asset management and avoiding idle resources

Strong asset management prevents capital from being locked into equipment, software, or facilities that don’t generate enough throughput. I recommend reviewing asset utilization monthly so underused purchases can be sold, leased, or repurposed quickly.

Investment portfolio optimization techniques for company cash

If your business holds surplus cash or multiple investment buckets, apply investment portfolio optimization techniques like rebalancing, diversifying across liquidity needs, and capping higher-risk bets at a small percentage of total capital. Guidance from professional bodies like the CFA Institute can help finance teams build repeatable frameworks for this.

Where Overcapitalization Shows Up First in a Business

Overcapitalization rarely announces itself. It creeps in through familiar habits: aggressive expansion, patient tolerance for weak returns, and debt loads that feel manageable until they aren’t.

Growth strategy that outpaces demand

Many companies overcapitalize because their growth strategy is too aggressive for their real market size. Rapid expansion into new locations, inventory, or headcount can drain returns long before demand catches up.

Long-term investing without a capital efficiency test

A long-term investing mindset works only when paired with capital efficiency metrics. Long-term patience is a strength; long-term tolerance for weak returns is not.

Debt-heavy structures

When debt is part of the mix, risk grows quickly if borrowing exceeds what the business can comfortably service. Refinancing, debt reduction, or repayment from retained profits can improve the capital structure and lift returns.

How to Reduce Excess Capital and Improve ROI Without Stalling Growth

Apple provides one of the clearest playbooks for what to do when cash builds faster than the business can deploy it. In 2012, CEO Tim Cook announced Apple would return $45 billion to shareholders over three years through dividends and buybacks after building a large cash pile. The lesson for founders: when capital exceeds productive uses, returning it—or redirecting it—is often smarter than letting it sit.

Here’s how to apply that thinking at any scale:

  • Verify demand before adding capacity. Use market research to confirm the next dollar will create demand, not just capacity.
  • Make investments milestone-based. Treat each business investment as a sequence of tests, not a permanent commitment.
  • Recover capital from non-core assets. Sell what you don’t need, consolidate duplicated tools, and redirect proceeds to higher-yield uses.
  • Always model the downside. Ask what happens if revenue lands 20% below plan for two quarters.

For more tactical guidance on cash discipline, my team’s bookkeeping and cash flow resources walk through the same frameworks we use with clients.

The Human Side of Avoiding Overcapitalization

Numbers matter, but behavior often decides the outcome. After the 2008–2009 crisis, Federal Reserve economists observed that U.S. nonfinancial companies piled up cash and kept it elevated for years, showing how easily “extra cushion” money becomes long-term idle capital when fear takes over.

Where human judgment still matters

Models and spreadsheets help, but human judgment decides whether to hold, deploy, or exit a capital position. In my experience, overcapitalization is as much a behavioral issue as a financial one—leaders get attached to the original plan and keep funding it long after the data has changed. The best capital decisions aren’t the boldest ones; they’re the ones that preserve flexibility while improving measurable returns.

Final Thoughts

To avoid overcapitalization of investment capital, fund only what you can use productively, assign every dollar a measurable purpose, and review returns often enough to correct course early. The companies that thrive combine honest market research, disciplined capital allocation, active risk management, and unflinching ROI tracking—then act quickly when the numbers signal that capital is not pulling its weight.

If you want a more disciplined way to manage cash, debt, and growth investments in your business, connect with the experts at Complete Controller for practical bookkeeping and financial guidance built for founders like you. ADP. Payroll – HR – Benefits

Frequently Asked Questions About Avoid Over Capitalization of Investment Capital

What is overcapitalization in simple terms?

Overcapitalization means a business holds more capital than it can use profitably, which drags down returns on invested capital and weakens key financial ratios.

What are the most common causes of overcapitalization?

The usual culprits are raising too much debt or equity, overestimating growth, buying assets you don’t fully utilize, and funding expansion before validating market demand.

How can a business reduce excess capital?

Repay expensive debt, sell unproductive assets, slow new investment, return cash to shareholders, or redirect funds toward higher-return opportunities aligned with your growth plan.

Is overcapitalization always bad?

It usually harms returns, but modest excess capital can provide flexibility when actively managed. The problem starts when that capital sits idle without a clear purpose or timeline.

How do I know if my business is overcapitalized?

Warning signs include weak return on invested capital, rising debt service costs, underused assets, growth that doesn’t translate to profitability, and cash reserves without a defined deployment plan.

Sources

Complete Controller. America’s Bookkeeping Experts About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
author avatar
Jennifer Brazer Founder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Reviewed By: reviewer avatar Brittany McMillen
reviewer avatar Brittany McMillen
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.
Home Office vs Leased Office Costs

Home Office vs Leased Office:
Cost & Setup Guide

A home office vs leased office decision comes down to total occupancy cost, setup complexity, tax treatment, and how well each option supports your workflow, team, and client-facing needs. For most solo founders and small teams, a home office wins on affordability and flexibility, while a leased office (or coworking alternative) earns its keep once you need dedicated space, stronger professional presence, or facilities that justify a long-term commitment.

Here’s a stat that reframes this whole conversation: U.S. workers spent an average of 27.8 minutes commuting one way in 2023—roughly 55.6 minutes per day of unbilled, unpaid time you lose the moment you sign a lease. Over 20 years growing Complete Controller from my kitchen table into a multi-location, cloud-enabled bookkeeping firm serving thousands of small businesses, I’ve watched clients across nearly every industry navigate this exact crossroads. Some saved tens of thousands by staying home longer than they thought possible. Others unlocked serious growth by moving into the right space at exactly the right moment. In this guide, I’ll walk you through the real numbers, tax angles, workflow trade-offs, and the decision framework I use with clients—so you can pick the office model that fits your stage, budget, and vision.

What is “home office vs leased office” and how do you get the trade-offs right?

  • Home office vs leased office means comparing working from home with renting dedicated business premises on cost, setup, tax impact, and workflow to choose the best fit for your team size, budget, and growth plans.
  • A home office keeps fixed costs low, avoids lease commitments, and suits solo owners and remote-first teams—but can blur work-life lines and limit client-facing polish.
  • A leased office offers space, amenities, and image, but carries multi-year leases, fit-out costs, and separate utilities.
  • Coworking spaces now bridge the gap—short commitments and bundled services at lower total occupancy cost than traditional leases in most cities.
  • The right call depends on team size, client expectations, cash flow stability, and your appetite for flexibility versus a fixed hub. Cubicle to Cloud virtual business

Home Office vs Leased Office: The Core Trade-Offs

The most important shift I’ve seen in small business office strategy is that “office” no longer means one thing. You’re comparing total occupancy cost, setup complexity, workflow fit, client perception, and long-term risk—not just monthly rent versus a spare bedroom.

Key dimensions to weigh:

  • Total occupancy cost (rent/mortgage share, utilities, equipment, commute, tax impact)
  • Setup and ongoing management (fit-out, furniture, IT, cleaning, compliance)
  • Workflow and productivity (distractions, collaboration, meeting space)
  • Client and brand perception (address, reception, in-person polish)
  • Flexibility and risk (lease length, scalability, exit terms)

How to decide home office or leased office

  1. Clarify your business stage. Early-stage or pre-revenue almost always favors a home office for cash preservation.
  2. Map your work patterns. If most work is remote and asynchronous, home or hybrid coworking wins.
  3. Stress-test your budget. Model 12–36 months of costs including hidden items like cleaning, insurance, and commute.
  4. Weigh lifestyle and focus. Founders with families may find home distractions expensive; others gain hours back daily.

Leased Office Cost Comparison: The Real Math

This is where founders get surprised. Advertised rent is only the tip of the iceberg—CAM charges, fit-out, and setup can double your first-year outlay.

Cost of home office setup vs leasing an office space

  • Home office setup: Desk, chair, monitor, lighting, storage—usually a few hundred to a few thousand dollars for a solid ergonomic setup.
  • Leased office setup: Security deposit (2–3 months’ rent), legal fees, renovation, partitions, furniture, signage, IT—commonly tens of thousands even for small footprints.
  • Recurring home costs: Slightly higher utilities, faster internet, business insurance.
  • Recurring lease costs: Base rent plus CAM/OPEX, utilities, cleaning, security, insurance, and sometimes parking.

Leased office cost comparison vs coworking space

Coworking has moved from novelty to serious contender. The U.S. had roughly 6,200 coworking spaces in 2024, up from 5,900 in 2023, and the reason is simple math:

  • Coworking memberships beat traditional leases in about 97% of U.S. cities analyzed for small teams.
  • Average leased office for a 10-person team: ~1,500 sq ft at $33/sq ft ≈ $4,125/month base rent, before extras.
  • Typical coworking: median ~$220/month per person, so ~$2,200/month for 10 people—furniture, internet, cleaning, and meeting rooms included.

Remote work setup and commuting costs

Here’s the number that changes minds: U.S. workers averaged 27.8 minutes each way commuting in 2023—nearly an hour per day, per person. Multiply that by a team, then by 250 workdays, and the “cheap” lease starts looking expensive. Remote-first home office setups eliminate that drain entirely.

Not sure which office option fits your finances? Complete Controller helps you see the real costs, cash flow, and numbers behind the decision. Get clarity before you commit.

Tax Rules: Home Office vs Business Office

Tax treatment is where a good bookkeeper earns her fee. Both options offer deductions, but they work very differently.

Home office tax deductions

A qualifying home office—used regularly and exclusively for business—can generate deductions for a proportional share of rent or mortgage interest, utilities, insurance, and repairs. If detailed tracking feels heavy, the IRS Simplified Option lets you deduct $5 per square foot up to 300 square feet, capped at $1,500 per year. It’s a fast way to estimate your benefit before doing full expense allocation. For a deeper dive on documentation, our team’s small business bookkeeping resources walk through what to track.

Home office expenses tax deductions vs leased office

  • Home office: Prorated deductions reduce taxable income but can complicate capital gains when you sell your home.
  • Leased office: Rent, utilities, and maintenance are clean business expenses—simpler bookkeeping, higher absolute cost.

Compare the tax benefit alongside actual cash cost, not in isolation. Saving on taxes while starving cash flow is a losing trade.

Workflow, Ergonomics, and Team Dynamics

Cost is only half the equation. How you actually work matters just as much.

Home office workspace & ergonomics

A supportive chair, adjustable desk, proper monitor height, and good lighting protect your health and your output. Working from the couch or kitchen table looks fine for a week and expensive after a year. Separate your work zone from your personal space—your focus and your family will thank you.

Small business office options & flexible working arrangements

Modern small business office options include full home office, traditional leased space, serviced offices, and coworking memberships. Hybrid models—remote most days, coworking for collaboration—give teams meeting rooms and a professional address without the full-time commitment. These flexible arrangements also help recruiting and retention.

When a Leased Office Actually Makes Sense

Sometimes leasing is the right move. Let’s talk about when.

Professional image and client expectations

For industries built on in-person meetings—law, wealth management, certain consulting practices—a reputable office address signals reliability. That said, service firms like ours build trust through digital signals: credentials, testimonials, secure client portals, and consistent delivery. Image can be built without square footage.

Leased office lease terms and risk

Traditional leases run 3–10 years with personal guarantees, escalation clauses, and unpredictable CAM charges. Before signing, understand every clause on repairs, insurance, and exit terms. Consulting a commercial real estate attorney is money well spent.

Case study: When to switch

Fora Financial documented the tipping point their team faced between remote work and leasing. Early on, home offices delivered clear savings and flexibility. As the team grew and client meetings multiplied, leasing became the smarter play. Their conclusion, per Fora Financial’s guidance: there’s no universal right answer—evaluate isolation tolerance, client expectations, and budget before you make the switch.

Jennifer’s Framework for Choosing Your Office Model

From advising hundreds of clients, here’s the simple framework I use:

  1. If your monthly occupancy cost would exceed 10–15% of stable monthly revenue, a traditional lease is premature.
  2. If 70–80% of work can be done remotely, invest in ergonomics and digital infrastructure first.
  3. If clients regularly need in-person meetings, try coworking with meeting rooms before signing a long lease.
  4. Revisit annually—most businesses evolve from home → coworking → leased office as they grow. Our outsourced accounting services can help you model each stage.

Final Thoughts: Choose the Office That Serves Your Stage

The home office vs leased office decision isn’t permanent—it’s a strategic choice that should grow with your revenue, team, and client needs. Home offices and hybrid coworking usually win on cost and flexibility for solo founders and small teams. Leased offices earn their place when sustained collaboration, specialized space, or brand presence justifies the commitment.

The most successful clients I’ve worked with delayed leasing until it clearly fueled growth—not ego. Start by optimizing your home setup, explore coworking as a middle path, and lease only when the math and the workflow demand it. For tailored advice on how your office choice affects your books, taxes, and cash flow, connect with our team at Complete Controller. LastPass – Family or Org Password Vault

Frequently Asked Questions About Home Office vs Leased Office

Is it cheaper to work from a home office or lease an office?

For most small businesses, a home office is cheaper because you skip rent, deposits, and fit-out costs, paying only incremental utilities and equipment. Leased offices add base rent plus utilities, cleaning, and maintenance, pushing total occupancy cost far higher.

When should a small business switch from a home office to a rented office?

Consider switching when collaboration needs, client expectations, and team size make remote work inefficient, and when cash flow can reliably cover multi-year lease and operating costs without strain.

Are coworking spaces cheaper than traditional office leases?

For small teams, coworking beats traditional leases in about 97% of U.S. cities studied, once you factor in setup, furniture, utilities, and amenities that come bundled with memberships.

Can I claim tax deductions for my home office?

Yes—if you use a portion of your home regularly and exclusively for business. You can use the IRS Simplified Option ($5/sq ft up to $1,500) or itemize actual expenses. Consult a tax professional for your situation.

What are the hidden costs of leasing an office?

Fit-out, furniture, utilities, cleaning, insurance, CAM charges, repairs, legal fees, and commuting time—all of which routinely make leases much more expensive than the advertised rent suggests.

Sources

Complete Controller. America’s Bookkeeping Experts About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
author avatar
Jennifer Brazer Founder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Reviewed By: reviewer avatar Brittany McMillen
reviewer avatar Brittany McMillen
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.
Avoid Small Business Banking Mix

Small Business Personal Banking Mix:
Why To Avoid It

A small business personal banking mix creates real problems because it blurs the line between business and personal activity—which makes bookkeeping harder, weakens tax support, and exposes owners to audit, penalty, and liability risk. The safest fix is straightforward: keep separate accounts, separate cards, and clean documentation so every transaction has a clear purpose and a defensible paper trail.

In my 20+ years leading Complete Controller, I’ve watched “just this once” turn into months of cleanup, missed deductions, and financial confusion for owners who are already stretched thin. Having partnered with thousands of small businesses across nearly every sector, I can tell you that separating your banking setup is one of the highest-ROI decisions you’ll ever make. In this article, I’ll walk you through why the mix is so risky, how it quietly damages taxes and legal protection, and the exact banking strategy I recommend to build a system that scales with you—so you can spend less time on cleanup and more time growing.

What is a small business personal banking mix and why should you avoid it?

  • Mixing personal and business banking means using the same account, card, or payment flow for both business and personal transactions, which makes records harder to trust and defend.
  • It complicates tax prep because personal expenses generally aren’t deductible, and shared expenses must be split between business and personal use.
  • It increases the chance of deposit confusion, where business deposits in a personal account may be treated as income until you prove otherwise.
  • It can weaken liability protection for entity-based businesses if commingling makes business and personal finances look indistinct.
  • The best practice is a small business checking account, a separate personal account, and clear rules for owner draws and reimbursements. ADP. Payroll – HR – Benefits

How Does a Small Business Personal Banking Mix Affect Taxes, Records, and Protection?

Mixing accounts touches every corner of your financial life—taxes, records, legal protection, cash flow, and decision-making. Each of these areas quietly loses accuracy when your business and personal activity share the same pool.

The IRS states that you must keep records that show your gross income and deductions, and those records must support what appears on your tax return (IRS Publication 583). When business and personal spending are mixed, proving what’s deductible becomes far harder—and that’s where owners lose money.

  • Taxes: Mixed accounts make it harder to identify deductible business expenses and easier to accidentally claim personal spending as business costs, which the IRS doesn’t allow.
  • Records: Mixed accounts create extra reconciliation work because each transaction must be classified after the fact instead of cleanly categorized at the point of purchase.
  • Protection: For LLCs and corporations, commingling can make the business look less separate from the owner, which may undermine legal safeguards in a dispute (AZ Tax Agents).
  • Cash flow: When business and personal spending share the same pool, owners lose sight of true operating cash and underfund tax reserves or payroll.
  • Decision-making: Clean separation gives you real visibility into margins, seasonality, and spending patterns.

Why Separation Matters for Day-to-Day Operations

Separate banking isn’t only a tax move—it’s an operating system for the business. It improves bookkeeping, simplifies owner pay, and supports better financial discipline across personal banking services, merchant services, and payment workflows. This is where our team at Complete Controller’s bookkeeping services sees the fastest wins for clients.

Personal banking services vs. business banking services

Personal accounts are built for household spending, while business accounts are designed for business deposits, vendor payments, and reporting. A business account makes it easier to isolate income, manage authorized users, and connect to bookkeeping and tax processes. Avoid routing client payments, vendor bills, or owner expenses through a personal account unless there’s a documented, temporary reason and a clear reimbursement trail.

Small business checking account setup

Open a dedicated small business checking account as the financial home base for all business receipts and expenses. Use one account for operating activity and, if needed, a separate business savings account for tax reserves.

A common objection I hear: “Business checking has fees.” True—FDIC data confirms many banks charge monthly maintenance fees on business checking (often avoidable with minimum balances). But that small monthly fee is nothing compared to the cost of tax-time cleanup, missed deductions, and professional fees when your records are a mess.

Business debit card and business credit card use

  • A business debit card should be used only for business purchases tied to the company’s bank account.
  • A business credit card helps isolate business spending, preserve receipts, and simplify rewards and expense tracking.
  • If you accidentally use a personal card for a business expense, record it immediately and reimburse it through a documented process.

What Is the Best Banking Strategy for Small Businesses?

The best banking strategy for small businesses is a simple, repeatable system: one business checking account, one business savings account, one business card, and one process for owner pay and reimbursements. Learn more about setting up a strong financial foundation at Complete Controller’s small business resources.

Online banking and cash management tools

  1. Use online banking for small business to monitor balances daily and flag unusual transactions.
  2. Add cash management tools or bookkeeping integrations so deposits and bill pay happen with minimal manual work.
  3. Reconcile accounts monthly so errors don’t pile up until tax season.

How to manage cash flow with personal and business accounts

Move money from business to personal only through a defined owner’s draw, salary, or distribution process based on your entity type (SBA business structure guide). Keep a business tax reserve in a separate savings account so quarterly taxes don’t come out of operating cash unexpectedly. Track vendor payments, payroll, and recurring subscriptions inside the business account for a true cash-flow picture.

Payment processing and merchant services setup

Keep payment processing tied to the business account so merchant deposits can be matched directly to business revenue. Make sure merchant services deposits, chargebacks, and processing fees flow through the same business ledger as the sales they relate to.

Mixing money makes messy books. Complete Controller helps keep your business finances organized, accurate, and ready for smarter decisions. Get financial clarity today.

How Do You Fix a Small Business Personal Banking Mix?

If your finances are already mixed, the goal is to cleanly separate them and rebuild a defensible paper trail. Our team at Complete Controller’s expert accounting team helps clients through exactly this process every week.

Combine personal and business banking setup: How to unwind it cleanly

  1. Open a new business checking account immediately and route all future business activity through it.
  2. Pull recent statements from mixed accounts and classify transactions as business or personal before year-end close.
  3. Document every owner transfer, reimbursement, and loan so money movement has a stated purpose.
  4. Update autopay, invoicing, payroll, and merchant deposit instructions to make the new structure the default.
  5. Work with a bookkeeper or accountant if the mixed period is long, because cleanup is faster and safer with professional review.

Small business checking vs personal account for taxes

A small business checking account supports cleaner deductions and simpler tax prep than a shared personal account. A personal account may work temporarily for a sole proprietor in the strict legal sense, but it’s still a poor tax and bookkeeping practice.

Real-World Case Study: When Records Are Inadequate

In Ramirez v. Commissioner (TC Memo 2017-174), the U.S. Tax Court upheld accuracy-related penalties where the taxpayer’s records were inadequate and personal and business items were mixed. The case is frequently cited as a warning that weak documentation costs real money—not just time.

The lesson is clear: when personal and business funds are mixed, bank deposits can be reconstructed as business income unless the owner can prove otherwise. That shifts the burden to you to show which deposits weren’t taxable and which expenses were legitimate deductions.

Conclusion

A small business personal banking mix creates avoidable problems in bookkeeping, taxes, and legal protection—while separate accounts make it easier to track cash flow, defend deductions, and keep your business structure credible. If I were starting over with a new company tomorrow, I’d open the business account first, keep personal spending out of it from day one, and treat clean separation as a non-negotiable operating rule.

If you’re still mixing accounts, take the first step today: open a dedicated business checking account, move ongoing activity over, and document past transfers before the problem grows. For help building a cleaner, more scalable financial system, visit Complete Controller and connect with our team. Complete Controller. America’s Bookkeeping Experts

Frequently Asked Questions About Small Business Personal Banking Mix

Can I use one bank account for both personal and business expenses?

It’s possible in some cases, but it’s not recommended. Mixing accounts makes taxes, bookkeeping, and legal protection harder to maintain and defend.

What is the biggest risk of mixing business and personal banking?

The biggest risk is losing clean records, which can lead to disallowed deductions, tax confusion, and a much harder time defending your numbers in an audit.

Do I need a business account if I’m a sole proprietor?

Yes. Even though it’s not legally required for sole proprietors, a separate account keeps records cleaner and makes it easier to separate deductible business activity from personal spending.

How do I separate business and personal spending after mixing them?

Open a new business account, move all future business activity there, classify old transactions, and document owner transfers and reimbursements before year-end.

Can mixing accounts affect my LLC protection?

Yes. Commingling can make the business look less separate from the owner, which may weaken the liability shield in a legal dispute.

Sources

    Download A Free Financial Toolkit About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
    author avatar
    Jennifer Brazer Founder/CEO
    Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
    Reviewed By: reviewer avatar Brittany McMillen
    reviewer avatar Brittany McMillen
    Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.
    Rapid Business Growth Challenges

    Rapid Business Growth Challenges:
    When It Becomes Painful

    Rapid business growth challenges become painful the moment revenue outruns your cash, systems, hiring pipeline, and leadership bandwidth. A company can look wildly successful on the outside while quietly struggling with drained bank accounts, broken processes, service quality slips, and exhausted teams on the inside. The pain point usually starts when growth outpaces the operating model, and the fix requires stabilizing cash flow, standardizing operations, and hiring with real capacity planning before chasing more expansion.

    Here is a stat that stops most founders cold: Gallup reports that U.S. employee engagement dropped to just 30% in 2023, and disengaged teams are exactly what breaks a fast-growing company from the inside out. Over 20 years of building Complete Controller and partnering with founders across nearly every industry you can name, I have watched the same story play out again and again—the businesses that survive rapid scale are the ones that treat bookkeeping, forecasting, and operational visibility as growth assets, not back-office chores. In this article, I will walk you through the real reasons growth turns painful, how to stabilize cash, how to protect your team, and a 30-day recovery plan you can start using tomorrow.

    What are rapid business growth challenges, and why do they become painful?

    • Answer: Rapid business growth challenges are the cash flow, operational, hiring, and leadership problems that surface when a company scales faster than its systems and people can support.
    • Cash flow tightens because growth demands upfront spending on payroll, inventory, and equipment before customer payments arrive.
    • Operations break down when informal processes that worked at a smaller size collapse under higher volume.
    • Hiring gets harder because recruiting, onboarding, and training all compete for stretched leadership attention at once.
    • Customer experience suffers when fulfillment and service teams cannot keep pace with demand.
    • Pain peaks when leadership bandwidth runs out before a scalable operating model is built. Complete Controller. America’s Bookkeeping Experts

    Why Rapid Business Growth Challenges Hit Harder Than Slow Growth

    Fast growth feels like a victory lap, but it exposes every weak seam in your business model at the same time. Slow growth gives you room to patch problems as they appear. Rapid scale hands you five problems at once, and each one amplifies the others.

    Scaling operations without breaking them

    Scaling operations is usually where founders feel the first crack. Order volume, customer requests, vendor coordination, and internal complexity all rise together, and any workflow held together by a single hero on your team will fail. According to Business Queensland’s guidance on rapid growth, documented systems and clear ownership are the difference between controlled growth and chaos.

    Cash flow management under oressure

    Cash flow management becomes life-or-death during expansion because profitable revenue does not equal available cash. The U.S. Small Business Administration warns that slow-paying customers are a leading cause of small business failure—even for firms showing strong profit on paper.

    Team capacity planning that actually works

    Team capacity planning fails when leaders forecast only for the work itself and forget the ripple effect: onboarding, communication, approvals, and supervision all multiply with headcount.

    The Most Common Business Growth Obstacles Founders Hit First

    Business growth obstacles rarely arrive one at a time. They cluster, which is why founders often describe growth pain as “everything breaking at once.”

    Sales pipeline bottlenecks

    Sales pipeline bottlenecks happen when demand spikes but your team cannot quote, close, deliver, or collect fast enough. A backed-up pipeline quietly kills momentum and margins.

    Customer acquisition costs and retention

    Customer acquisition costs climb during rapid growth if you keep spending on marketing while conversion or service quality weakens. That is why customer retention strategies matter even more during expansion than during steady state—churn during a scale-up can wipe out every new customer you paid to acquire.

    How to Fix Operations Before Rapid Business Scaling Breaks Them

    Strong operators do not wait for the wheels to come off. They simplify, standardize, and document before the next growth wave hits. Consider Starbucks: in 2008, Howard Schultz publicly admitted rapid expansion had “watered down the Starbucks experience,” and he closed hundreds of stores for barista retraining to reset service quality. If it can happen to Starbucks, it can happen to you.

    Managing operational scalability during growth

    Managing operational scalability during growth means building repeatable workflows so the business can absorb more volume without losing control. Your operations playbook should include:

    • Standard operating procedures for every core workflow
    • A single named owner for each recurring task
    • Dashboards tracking service speed, error rates, and backlog
    • A monthly review cycle to eliminate bottlenecks
    • Automation for repetitive admin work like invoicing and reporting

    Our team at Complete Controller’s cloud bookkeeping services sees this pattern constantly—the businesses that scale cleanly are the ones that automated invoicing, approvals, and reporting before volume tripled.

    How to scale a business quickly without the crash

    How to scale a business quickly is not about speed—it is about removing friction. What breaks first in real businesses? Invoicing, approvals, financial reporting, and customer follow-up. Manual heroics do not scale, and cloud-based financial visibility is what keeps surprises off your P&L.

    Rapid growth shouldn’t create financial chaos. Get expert bookkeeping, clearer cash flow, and the financial visibility to scale with confidence. Connect with Complete Controller today.

    Cash Flow Solutions for Fast-Growing Companies

    Cash flow pressure is the number-one reason growth turns painful. Fast growth can drain cash even when sales look phenomenal—the SBA specifically flags this pattern as a common cause of failure for otherwise profitable firms.

    Cash flow discipline that protects growth

    Cash flow solutions for fast-growing companies should focus on timing, visibility, and discipline:

    1. Forecast cash weekly, not monthly
    2. Track receivables aging and chase collections aggressively
    3. Negotiate extended supplier terms wherever possible
    4. Match hiring to confirmed revenue, not optimism
    5. Separate “growth spend” from “survival spend” in your budget

    EBITDA improvement during expansion

    EBITDA improvement matters because top-line growth without margin discipline creates a bigger company that is still financially fragile. Focus on revenue quality over revenue quantity, plug margin leakage from rushed hiring, and speed up collections to strengthen operating cash. See Investopedia’s EBITDA breakdown for the mechanics.

    Hiring, Leadership, and Fundraising Challenges During Fast Growth

    Growth exposes people problems before systems problems. Team members get stretched thin, managers get promoted too fast, and founders stay trapped in every decision. This is where the Gallup engagement data hits home—when engagement drops during a scale-up, turnover rises exactly when you need stability most.

    Whatfix’s research on HR challenges highlights employee wellness and work-life balance as major organizational risks during growth periods. The takeaway: rapid scaling has to be matched with support systems, not just output targets.

    Fundraising challenges and investor readiness

    Fundraising challenges show up fast when investors see growth outrunning your controls. Venture funding and investor readiness depend on clean books, clear startup growth metrics, and a believable plan for scaling without operational collapse. Investors want to see margin, churn, cash conversion, and fulfillment capacity—not just revenue.

    Where Rapid Scale-Up Strategy Creates New Market Risks

    A rapid scale-up strategy should define which markets, channels, and products to prioritize first. Market entry barriers—local competition, regulatory shifts, customer expectations—make expansion more expensive than most founders plan for. Rapid business scaling works best when you expand in sequence: systems first, then people, then process, then new markets.

    A Founder’s 30-Day Recovery Plan for Painful Growth

    When growth turns painful, month one is about stabilization, not expansion:

    1. Freeze nonessential hiring and spending for 30 days
    2. Review cash, receivables, and payables weekly
    3. Identify your top three delivery bottlenecks
    4. Standardize your most-repeated workflow first
    5. Assign one owner to each critical process
    6. Build a simple dashboard for cash, capacity, and response times
    7. Reassess whether current growth is profitable and sustainable

    Final Thoughts

    Rapid growth is only an advantage when your business can support it with cash discipline, scalable operations, and a team ready for more complexity. In my two decades leading Complete Controller, the founders who thrive are the ones who treat bookkeeping, forecasting, and financial visibility as growth strategy—not cleanup work.

    If you are feeling the squeeze of rapid business growth challenges right now, start by stabilizing cash flow, simplifying operations, and hiring with real capacity in mind. Then build the financial reporting and controls that let you grow without losing control of the wheel. Visit Complete Controller to connect with our team and get the expert support that helps founders scale with clarity and confidence. ADP. Payroll – HR – Benefits

    Frequently Asked Questions About Rapid Business Growth Challenges

    What are the biggest challenges of rapid business growth?

    The biggest challenges are cash flow strain, broken processes, hiring pressure, declining service quality, and leadership burnout. These usually appear together, which is why fast growth feels overwhelming.

    Why does a fast-growing business run out of cash?

    Because expenses rise before customer payments arrive—payroll, inventory, and equipment often get paid weeks before revenue lands. The SBA specifically warns that slow-paying customers can sink even profitable, fast-growing companies.

    How do you manage a business that is growing too fast?

    Focus on weekly cash forecasting, standardizing core processes, hiring with discipline, and building capacity plans before chasing more growth. Stabilize first, then scale.

    What is the most common mistake during rapid business scaling?

    Continuing to scale before fixing the operational bottlenecks that are already breaking. More volume on a broken system just amplifies the damage.

    How do you know if growth is becoming unsustainable?

    Warning signs include missed deadlines, rising customer churn, stressed or disengaged employees, poor cash visibility, and a founder who is stuck in every decision.

    Sources

    LastPass – Family or Org Password Vault About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
    author avatar
    Jennifer Brazer Founder/CEO
    Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
    Reviewed By: reviewer avatar Brittany McMillen
    reviewer avatar Brittany McMillen
    Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.