Retail Business Controller Services

Retail Business Controller Services:
Your Secret Weapon for Profitable Stores

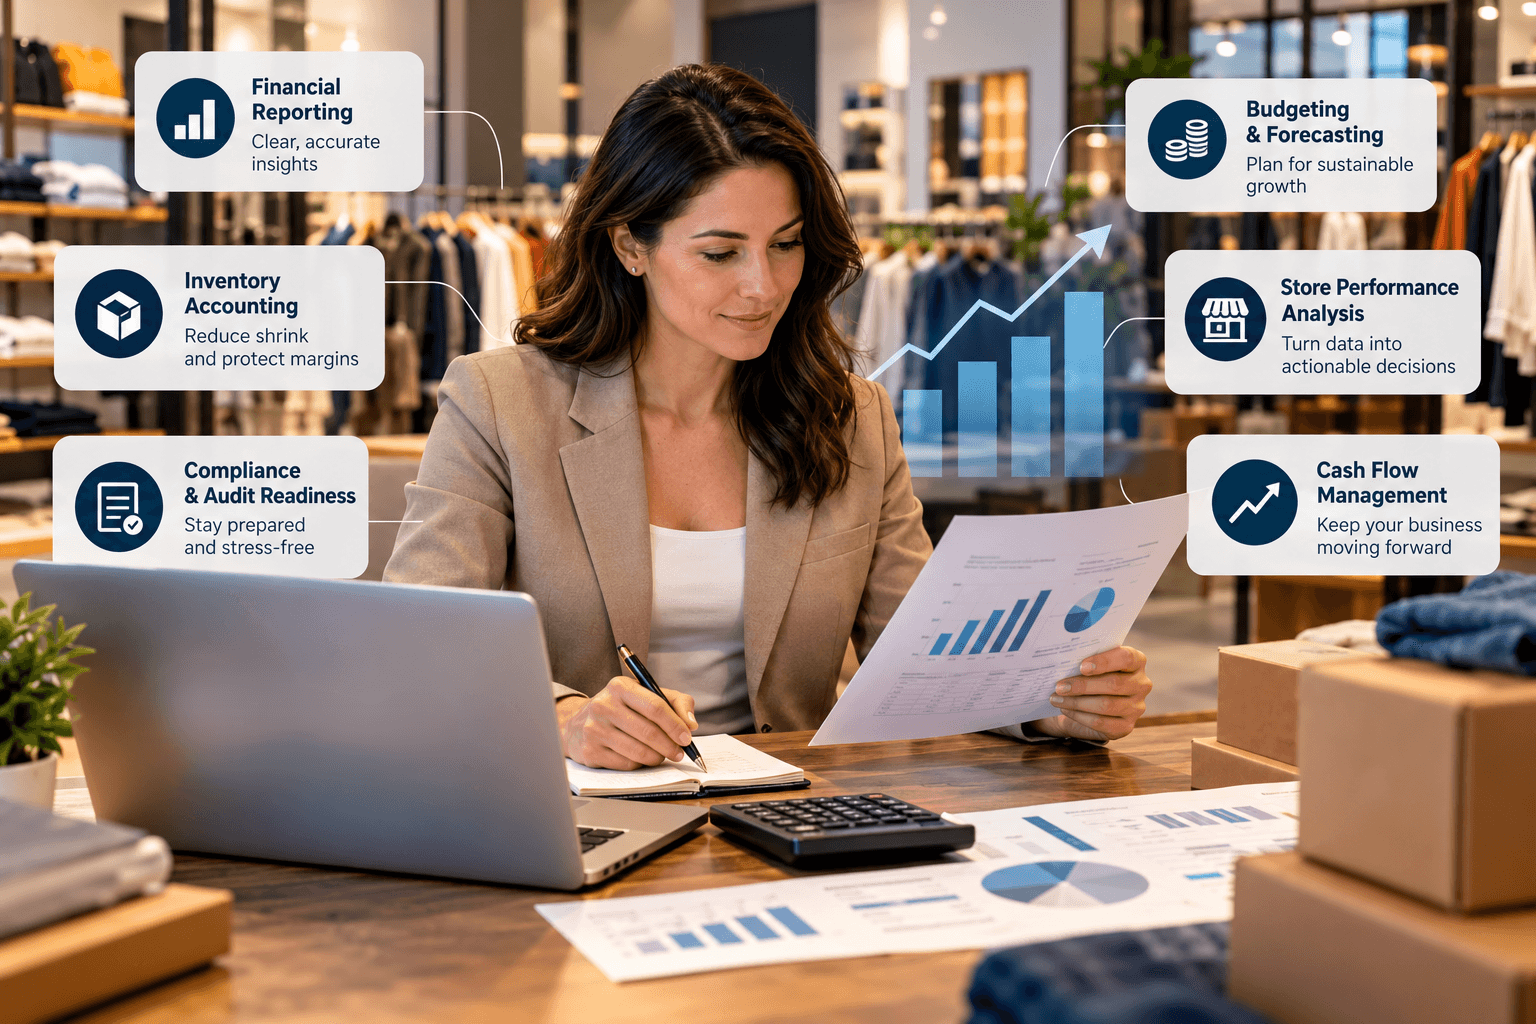
Retail business controller services give retailers expert-level financial oversight—month-end close, inventory accounting, KPI reporting, budgeting, and compliance—without the cost of a full-time controller, so you always know exactly where your money is going and why.

Here’s what I’ve learned after more than two decades leading Complete Controller: most retail owners aren’t losing money because of bad products or weak marketing. They’re losing it quietly—through shrink, messy books, and reports that arrive too late to matter. You can’t fix what you can’t see. And in retail, blind spots are expensive.

What are retail business controller services and why do they matter?

  • Retail business controller services provide outsourced financial leadership that manages reporting, inventory accounting, budgeting, compliance, and month-end close for retail businesses.
  • A retail financial controller turns raw sales and inventory data into reports you can actually act on.
  • These services protect margins by catching shrink, pricing errors, and cash leaks early.
  • They create a reliable monthly reporting rhythm so decisions are based on facts, not gut feelings.
  • For multi-store operations, controllers deliver store performance analysis that shows which locations earn—and which drain. Complete Controller. America’s Bookkeeping Experts
Why Retailers Can’t Afford to Fly Blind

Retail runs on thin margins and fast cycles. A JPMorgan Chase Institute study found that small retail businesses hold a median cash buffer of just 19 days. Nineteen days. That’s not a cushion—that’s a countdown clock.

This is exactly why structured retail finance operations matter so much. When your books are current and your reports are timely, you see cash crunches coming weeks ahead instead of discovering them at payroll. A controller builds that visibility into your routine, managing cash flow, margins, and operational performance so surprises become rare instead of routine.

The real cost of delayed data

Want a cautionary tale? Target Canada closed all 133 stores less than two years after launch—a collapse tied in part to inventory and supply-chain data failures that left shelves empty while warehouses overflowed. If bad data can sink a retail giant, imagine what it does to an independent retailer. Clean, monitored financial data isn’t optional. It’s survival.

Inventory Accounting: Where Margins Live or Die

Your inventory is your biggest asset and your biggest risk. U.S. retailers lost $112.1 billion to shrink in 2022, up from $93.9 billion the year before, according to the National Retail Federation. That’s theft, damage, and administrative error eating profits you already earned.

A retail controller fights back with disciplined inventory accounting—choosing the right valuation method, tracking cost of goods sold accurately, and reconciling physical counts against the books. The IRS has specific guidance on accounting methods and inventory treatment, and getting it right affects both your taxes and your true profitability.

Shrink reporting that actually protects you

Here’s what controller-level loss prevention reporting includes:

  • Monthly shrink analysis by location and category
  • Margin variance reports that flag pricing and receiving errors
  • Cycle count reconciliation so discrepancies surface fast
  • Vendor and PO auditing to catch overbilling before you pay it

When you measure shrink monthly instead of annually, you stop leaks while they’re drips—not floods.

Month-End Close and Reporting That Runs Like Clockwork

A consistent close cycle is the heartbeat of healthy retail finance. Reliable month-end close support means reconciled bank and merchant accounts, accurate sales postings, inventory adjustments booked on time, and financial statements in your hands within days—not weeks.

I’ve watched retailers transform simply by committing to this rhythm. When your P&L lands on the same day every month, you start spotting patterns: seasonal dips, creeping labor costs, that one SKU category quietly dragging margins down. Consistency creates clarity, and clarity creates confidence.

What a strong retail close includes

  1. Reconcile all bank, credit card, and POS merchant accounts
  2. Post and verify sales, returns, and discounts by location
  3. Record inventory adjustments and COGS
  4. Review accruals, prepaids, and payroll allocations
  5. Deliver financial statements with controller commentary

Notice the order matters here—skip step one and everything downstream wobbles.

Budgeting, Forecasting, and KPI Reporting for Retail

Great retailers don’t guess—they model. A controller builds retail budgeting and forecasting on real data, including authoritative benchmarks like U.S. Census Bureau retail sales figures, so your projections reflect market reality rather than wishful thinking.

Then comes the fun part: KPI dashboard reporting. Sales per square foot. Inventory turnover. Gross margin return on investment. Average transaction value by store. When these metrics hit your desk weekly, store performance analysis stops being an annual postmortem and becomes a living management tool. You compare locations, reward what works, and fix what doesn’t—while it still matters.

Tired of guessing where your retail profits are going? Complete Controller’s retail business controller services help you manage cash flow, track inventory, and protect your margins. Let’s bring clarity to your numbers!

Compliance, Controls, and Audit Readiness

Nobody loves thinking about audits. But documentation discipline is cheap insurance. The IRS publishes Audit Techniques Guides that show exactly how examiners approach businesses, which is why strong retail compliance and auditing practices—clean records, documented controls, sales tax accuracy—keep you prepared instead of panicked.

A controller builds these safeguards into daily operations: segregation of duties, approval workflows, sales tax tracking across jurisdictions, and a paper trail that holds up under scrutiny. Trust is built in the details, and so is audit readiness.

Should You Outsource Your Retail Controller Function?

Here’s my honest take: a full-time controller costs $100,000+ annually, and most growing retailers need the expertise—not the headcount. Outsourced retail accounting services deliver controller-level skill at a fraction of the overhead, with cloud-based access to your numbers anytime, anywhere.

That’s the model we pioneered at Complete Controller, and I’ve seen it change the game for thousands of businesses. You get experienced eyes on your financials, a team that scales with you, and freedom to focus on what you actually love—serving customers and growing stores. The old way—one overworked bookkeeper and a shoebox of receipts—was never built for modern retail. You deserve better, and better is available.

Conclusion: Take Control of Your Retail Finances

Retail business controller services turn financial chaos into competitive advantage. From inventory accounting that protects margins, to month-end close that delivers answers on schedule, to KPI reporting that makes every store accountable—controller-level oversight is how smart retailers stay profitable in a thin-margin world.

You’ve built something worth protecting. Now give it the financial leadership it deserves. Visit Complete Controller to connect with the team that pioneered cloud-based bookkeeping and controller services—and get expert eyes on your numbers today. CorpNet. Start A New Business Now
Frequently Asked Questions About Retail Business Controller Services

What does a retail business controller actually do?

A retail controller oversees financial reporting, inventory accounting, month-end close, budgeting, KPI analysis, and compliance—turning raw store data into decisions that protect profit.

How is a controller different from a bookkeeper?

A bookkeeper records transactions; a controller reviews, analyzes, and manages the entire finance function—ensuring accuracy, building controls, and advising leadership on performance.

Can controller services work for multi-store retailers?

Absolutely. Multi-store retailers benefit most, gaining consolidated reporting plus store-by-store performance analysis that reveals which locations drive profit.

How do controller services help reduce retail shrink?

Controllers track shrink through monthly inventory reconciliations, margin variance reports, and cycle count analysis—catching theft, damage, and errors before they compound.

Is outsourcing controller services cost-effective for small retailers?

Yes. Outsourced services deliver controller-level expertise at a fraction of a full-time salary, making professional financial oversight accessible to growing retailers.

Sources

ADP. Payroll – HR – Benefits About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
author avatar
Jennifer Brazer Founder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Reviewed By: reviewer avatar Brittany McMillen
reviewer avatar Brittany McMillen
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.

Healthcare Controller Outsourcing

Healthcare Controller Outsourcing:
The Smart Financial Move for Modern Medical Organizations

Healthcare controller outsourcing is the practice of hiring an external team of financial experts to manage your organization’s controller-level functions—financial reporting, compliance oversight, cash flow management, and internal controls—at a fraction of the cost of a full-time hire. For most healthcare organizations, it delivers stronger financial oversight, faster reporting, and better compliance without the $150,000+ salary of an in-house controller.

Here’s what nobody tells you: the biggest financial risk in healthcare isn’t a bad quarter. It’s the slow bleed of missed reimbursements, delayed reporting, and compliance gaps that quietly drain your margins while you’re busy caring for patients. I’ve spent over two decades watching medical practices and hospitals wrestle with this exact problem—and the ones who thrive are the ones who stopped trying to do it all in-house.

What is healthcare controller outsourcing and why does it work?

  • Healthcare controller outsourcing means delegating financial oversight, reporting, compliance, and cost accounting to an external expert team, typically at 30–50% less than an in-house controller’s cost.
  • Financial oversight includes month-end close, reconciliations, and cash flow visibility handled by seasoned professionals.
  • Compliance support covers internal controls aligned with HHS OIG guidance and Medicare cost reporting requirements.
  • Scalability lets you add or reduce services as your organization grows, merges, or adds locations.
  • Access to expertise means you get controller-level judgment without recruiting, training, or turnover headaches. CorpNet. Start A New Business Now

Why Healthcare Organizations Are Rethinking In-House Finance Teams

Let’s be honest—healthcare finance is not what it was ten years ago. National health spending reached $4.9 trillion in 2023 and continues climbing, according to CMS data on hospital financial management outsourcing context. Margins are tighter, payer rules change constantly, and skilled finance talent is harder to find and keep.

Meanwhile, the old model—one overworked controller juggling everything from payroll to Medicare cost reports—simply doesn’t hold up. When that person leaves (and they do), your institutional knowledge walks out the door with them. That’s not a finance strategy. That’s a gamble.

Outsourcing flips the equation: instead of one person, you get a team with built-in redundancy, cloud-based systems, and healthcare-specific experience. And that shift sets up the real question: what does the math actually look like?

The ROI Case for Healthcare Controller Outsourcing

The economics here are refreshingly simple. A full-time healthcare controller costs $130,000–$180,000 annually once you add benefits, software, and overhead. Outsourced controller services typically run a fraction of that—while delivering broader expertise.

At Complete Controller, we pioneered cloud-based bookkeeping and controller services precisely because we saw this gap. The economics of healthcare controller outsourcing favor organizations that need senior-level oversight but can’t justify (or can’t find) a full-time hire.

What you actually save

Beyond salary, consider the hidden costs you eliminate: recruiting fees, training time, turnover disruption, software licensing, and the expensive errors that happen when one person is stretched too thin. Studies consistently show outsourced accounting reduces total finance costs by 30–40% for mid-sized organizations. That’s money you can redirect to patient care, technology, or growth.

When Should You Outsource Healthcare Accounting Functions?

Timing matters. In my experience working with thousands of businesses, these are the signals that it’s time to make the move:

  1. Your books close late every month—decisions get made on stale data.
  2. Your finance lead is drowning in transactional work instead of strategic analysis.
  3. You’ve experienced turnover in your accounting department more than once in two years.
  4. You’re growing—new locations, new service lines, or a merger on the horizon.
  5. Compliance keeps you up at night because no one owns internal controls.

If two or more of these sound familiar, outsourced healthcare accounting will likely cost you less than the problems you’re currently absorbing. Transaction cost economics tells us the same thing: when internal coordination costs exceed the cost of outsourcing, the smart money moves outside.

Your healthcare team should focus on patients, not financial fire drills. Complete Controller delivers outsourced healthcare bookkeeping and controller-level support to strengthen cash flow, reporting, and financial clarity without the cost of another full-time hire.

Compliance and Internal Controls: Where Outsourcing Shines

Healthcare is one of the most regulated industries in America, and your finance function sits at the center of it. HIPAA-adjacent financial data, Medicare and Medicaid requirements, fraud prevention—the stakes are real.

An outsourced controller team builds segregation of duties into your workflow by default. That’s a control most small finance departments can’t achieve, because one person handles everything. The HHS Office of Inspector General publishes clear expectations for healthcare compliance accounting and internal oversight—and outsourced teams live in that guidance daily.

Cost reporting and reimbursement accuracy

Medicare cost reports are notoriously unforgiving. Errors delay reimbursement or trigger audits. Specialists in healthcare cost accounting outsourcing understand CMS documentation requirements and keep your reporting audit-ready year-round—not scrambled together at deadline.

Financial Reporting and Cash Flow Visibility You Can Trust

Here’s my bold take: if your financial reports arrive more than ten days after month-end, they’re history lessons, not management tools. You deserve better.

Outsourced controllers deliver structured, timely reporting—dashboards, variance analysis, rolling cash flow forecasts—so you always know where you stand. Strong outsourced financial reporting healthcare practices turn your numbers from a rearview mirror into a windshield. When you can see cash flow clearly, you negotiate better with payers, plan capital purchases confidently, and sleep better. Full stop.

How to Choose the Right Healthcare Controller Outsourcing Partner

Not all providers are created equal, and healthcare demands more than generic bookkeeping. Look for a partner with healthcare-specific experience, cloud-based systems with bank-level security, transparent flat-fee pricing, and a full team behind your account—not a single freelancer. Ask about their compliance training, their onboarding process, and how quickly they close the books. A great partner will answer confidently. A weak one will get vague fast.

Trust your instincts here. You’re not just buying a service—you’re choosing who guards your organization’s financial health.

Conclusion: Stronger Finances, Better Care

Healthcare controller outsourcing gives you expert financial oversight, airtight compliance, and real-time visibility—for less than the cost of one in-house hire. The organizations winning right now aren’t the ones working harder at old models; they’re the ones bold enough to build smarter ones.

I founded Complete Controller because I believe every organization deserves world-class financial management, not just the ones with deep pockets. If you’re ready to take control of your numbers, visit Complete Controller and connect with the team that pioneered cloud-based bookkeeping and controller services. Your mission is patient care—let us handle the books. Complete Controller. America’s Bookkeeping Experts

Frequently Asked Questions About Healthcare Controller Outsourcing

What does a healthcare controller do?

A healthcare controller oversees financial reporting, internal controls, compliance, cost accounting, and cash flow management—essentially serving as the financial quality gatekeeper for a medical organization.

How much does healthcare controller outsourcing cost?

Most organizations pay 30–50% less than a full-time controller’s total cost, with flat-fee pricing typically based on transaction volume and service scope.

Is outsourced accounting safe for healthcare organizations?

Yes—reputable providers use secure cloud platforms, strict access controls, and segregation of duties that often exceed what small in-house teams can achieve.

Can outsourced controllers handle Medicare cost reports?

Experienced healthcare controller services support CMS cost reporting requirements, keeping documentation accurate and audit-ready throughout the year.

When is the right time to outsource controller functions?

When books close late, turnover disrupts your finance team, compliance feels shaky, or growth outpaces your current capacity—outsourcing typically pays for itself quickly.

Sources

Cubicle to Cloud virtual business About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
author avatar
Jennifer Brazer Founder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Reviewed By: reviewer avatar Brittany McMillen
reviewer avatar Brittany McMillen
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.

Construction Industry Controller

Construction Industry Controller:
Cut Costs & Improve Cash Flow

A Construction industry controller helps construction companies cut costs, improve cash flow, and protect job profitability by bringing disciplined job costing, cash forecasting, and financial controls to every single project. This role transforms your books from a rearview mirror into a real-time dashboard for smarter decisions.

Here’s what I’ve learned after two decades serving thousands of construction businesses: most contractors don’t lose money on bad jobs—they lose money on jobs they thought were good. The margins quietly leak away through untracked change orders, late billing, and cost surprises that show up 60 days too late. A strong controller stops the leak before it starts, and I’m going to show you exactly how.

What is a construction industry controller and how do they cut costs?

  • A construction industry controller is a senior finance professional who manages job costing, cash forecasting, billing discipline, and internal controls to protect project margins and company cash flow.
  • Job costing gives you real-time visibility into whether each project is tracking to its estimated margin.
  • Cash forecasting predicts your cash position weeks ahead, so payroll and material purchases never catch you off guard.
  • Billing discipline ensures pay applications, retainage, and change orders get invoiced fast and accurately.
  • Internal controls catch errors, fraud, and cost overruns before they become five-figure problems. Download A Free Financial Toolkit

Why a Construction Industry Controller Beats a Bookkeeper Alone

A bookkeeper records what happened. A controller tells you what it means—and what to do next. That distinction matters enormously in construction, where a single mispriced change order can erase the profit on an entire job.

Consider the stakes: industry research consistently shows that construction has among the thinnest net margins of any sector, often in the 2–4% range. When your margin for error is that slim, you can’t afford to discover cost overruns at month-end. You need someone watching committed costs, work-in-progress schedules, and billing status daily.

The controller’s core responsibilities

Your controller should own the WIP schedule, over/under billing analysis, cash flow forecasting, job cost reviews, and month-end close. They should also lead controller troubleshooting and maintenance of your books—regular reconciliations and variance reviews that surface errors before they compound into cash flow crises. In my experience, companies that reconcile weekly instead of monthly catch billing mistakes 3–4 times faster.

How Job Costing Discipline Protects Every Project Margin

Job costing is where controllers earn their keep. Every dollar of labor, material, subcontractor cost, and equipment time must land in the right job and cost code—no exceptions, no “we’ll fix it later.”

Here’s the truth most contractors resist: your estimates are only as good as your historical cost data. If last year’s jobs were coded sloppily, this year’s bids are built on fiction.

Connecting field data to financial truth

Modern controllers don’t wait for paper timesheets. Connected job sites feed equipment hours, fuel usage, and material deliveries directly into cost reports through tools like an industrial IoT gateway, turning operational data into same-day cost visibility. When your controller sees labor burn outpacing schedule progress on Tuesday, you can fix it Wednesday—not at closeout.

Construction Industry Controller Strategies for Stronger Cash Flow

Cash flow kills more construction companies than lack of work ever will. Studies of construction payment cycles show contractors routinely wait 60–90 days for payment while covering payroll weekly. That gap is where businesses die.

Your controller closes the gap with these moves, in order of impact:

  1. Bill on time, every time. Pay applications go out the day they’re allowed—never a week later.
  2. Forecast cash 13 weeks out. A rolling forecast shows crunches before they arrive.
  3. Manage retainage actively. Track it, bill it at milestones, and chase it at closeout.
  4. Price and paper every change order. Unsigned change orders are donations, not revenue.
  5. Negotiate supplier terms that align payables with your receivable timing.

Every job should build your profit, not drain it. Complete Controller gives construction businesses accurate job costing, stronger cash flow visibility, and controller-level financial insight to keep every project on track.

Modernizing the Finance Function with Automation

You don’t need a bigger accounting department—you need a smarter one. Cloud-based systems and industrial automation principles applied to financial workflows eliminate manual data entry, cut close time from weeks to days, and free your controller to analyze instead of transcribe.

I pioneered cloud-based bookkeeping precisely because I watched talented finance people drown in paper. When AP approvals, receipt capture, and bank feeds run automatically, your controller spends their hours on margin analysis and forecasting—the work that actually moves your bottom line.

Don’t confuse financial controllers with equipment controllers

A quick clarification, because the terminology overlaps: a financial controller is not a programmable logic controller PLC or an HVAC control system. Those are operational technologies that run equipment and building systems. Your financial controller may use data from those systems, but their job is stewarding money, not machinery.

Governing Data and Security Across Connected Job Sites

The more connected your projects become, the more your controller must think about data integrity and security. Financial systems now touch project management software, telematics, and even machine control systems on equipment—and NIST’s guidance on operational technology security makes clear that every connection is a potential vulnerability.

Your controller should champion access controls, segregation of duties, and vendor payment verification. Payment fraud targeting construction companies is rising sharply, and a controller who requires dual approval on wire transfers has saved more than one of my clients from six-figure losses.

Using Building and Facility Data to Sharpen Lifecycle Budgets

For contractors doing service work, tenant improvements, or design-build, facility data is a goldmine. Systems built around a building automation controller generate performance data—energy use, equipment runtime, maintenance cycles—that a savvy controller folds into job costing for service contracts and lifecycle budgeting.

This is where controllers become strategic partners: they help you price maintenance agreements profitably, forecast warranty exposure, and identify which project types deliver the best long-term margins. That’s the difference between staying busy and staying profitable.

Conclusion

A construction industry controller isn’t overhead—it’s the highest-ROI hire most contractors never make. Disciplined job costing tells you the truth about margins. Rolling cash forecasts keep payroll safe. Tight billing and controls stop the quiet leaks that drain profit from good work. I’ve watched this role transform chaotic, gut-feel operations into companies that bid confidently and sleep soundly.

You built your company with skill and grit. Now build the financial engine it deserves. Visit Complete Controller for expert guidance from the team that pioneered cloud-based bookkeeping and controller services—we’ll help you get real visibility into every job, every dollar, every day. CorpNet. Start A New Business Now

Frequently Asked Questions About Construction Industry Controller

What does a construction industry controller do?

They manage job costing, cash flow forecasting, billing, WIP reporting, and internal controls so every project’s profitability is visible and protected in real time.

How is a controller different from a CFO in construction?

A controller manages day-to-day financial operations and reporting accuracy, while a CFO focuses on long-term strategy, financing, and growth. Many mid-size contractors need a strong controller before they need a CFO.

When should a construction company hire a controller?

Typically when revenue passes $3–5 million, when multiple jobs run simultaneously, or when the owner can no longer personally track job margins and cash position.

Can a construction company outsource the controller role?

Yes. Outsourced controller services deliver senior-level expertise at a fraction of a full-time salary—ideal for contractors who need discipline and visibility without the overhead.

How does a controller improve cash flow specifically?

By billing pay applications immediately, forecasting cash 13 weeks ahead, tracking retainage, enforcing signed change orders, and aligning payables with receivables timing.

Sources

Complete Controller. America’s Bookkeeping Experts About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
author avatar
Jennifer Brazer Founder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Reviewed By: reviewer avatar Brittany McMillen
reviewer avatar Brittany McMillen
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.

Restaurant Financial Controller

Restaurant Financial Controller:
The Role That Turns Chaos Into Profit

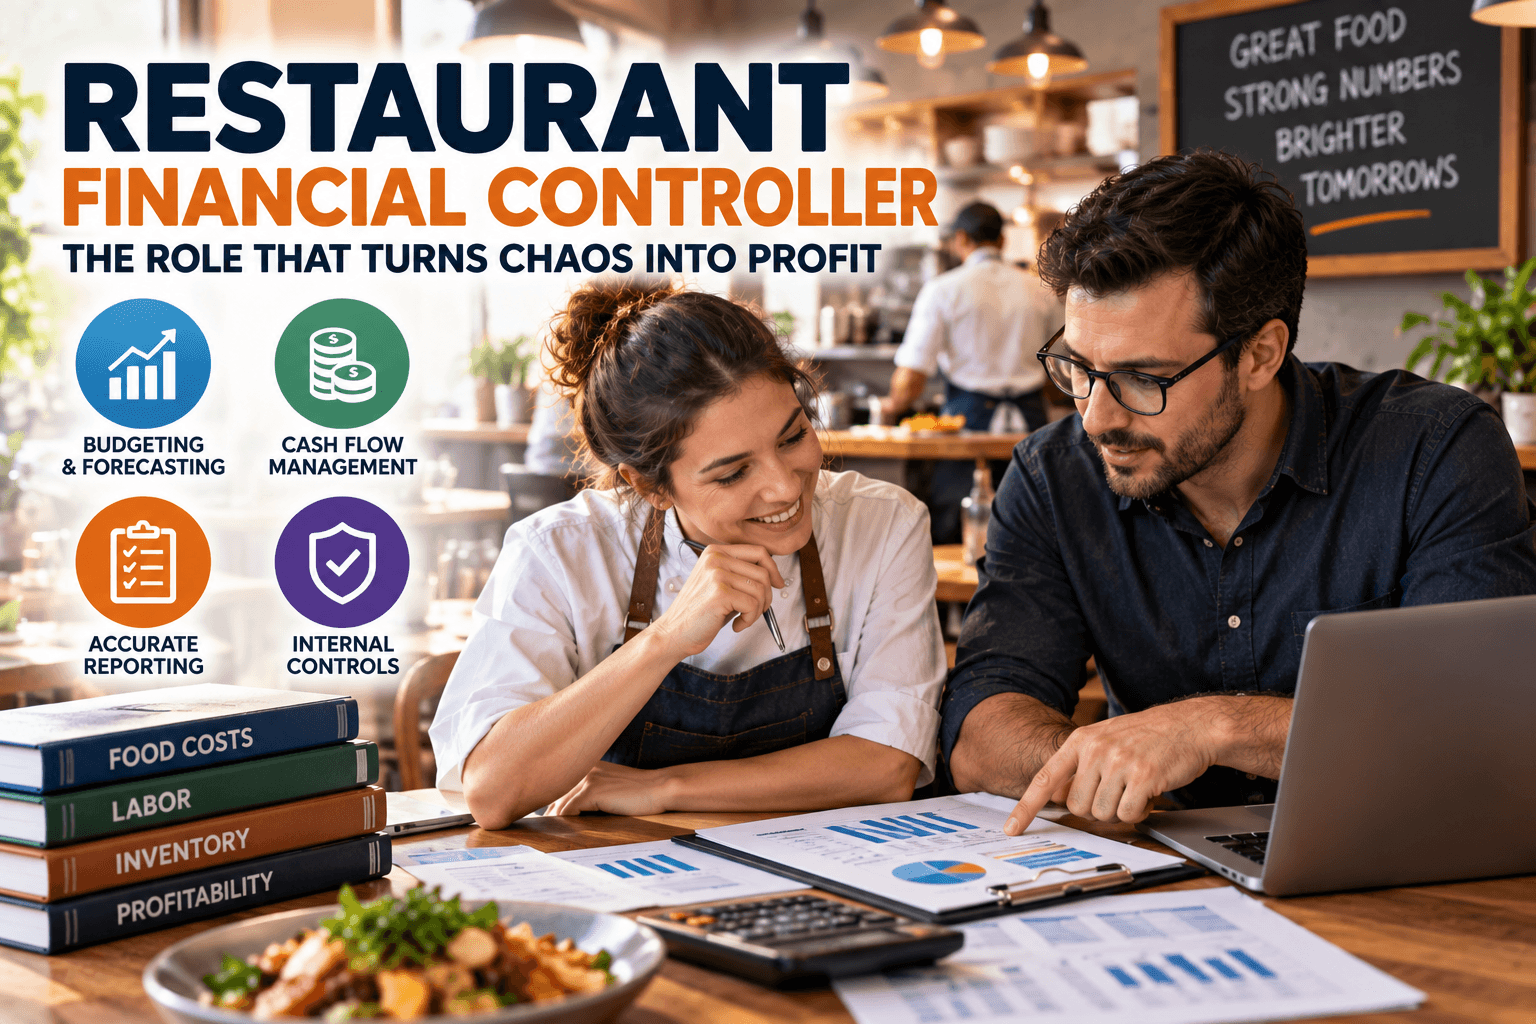
A restaurant financial controller is the financial leader who manages your restaurant’s accounting, budgeting, cash flow, internal controls, and reporting—so you can make decisions based on real numbers instead of gut feelings. Whether you run one location or twenty, this role transforms scattered receipts and mystery margins into a clear financial picture.

Here’s the truth most restaurant owners learn the hard way: great food doesn’t guarantee a great business. I’ve spent over two decades helping food service entrepreneurs, and the ones who thrive aren’t always the best chefs—they’re the ones who know their numbers cold. With the U.S. restaurant industry projected to hit $1.1 trillion in sales and employ 15.7 million people in 2024 (National Restaurant Association), the stakes have never been higher. Razor-thin margins don’t forgive financial blind spots.

What does a restaurant financial controller do and why does it matter?

  • Quick answer: A restaurant financial controller oversees bookkeeping accuracy, cash flow forecasting, budgeting, POS reconciliation, internal controls, and financial reporting—protecting profitability and preventing fraud.
  • They own the numbers, meaning daily sales, food costs, labor percentages, and vendor payments all flow through systems they design and monitor.
  • They forecast the future, using historical data to predict slow seasons, plan purchases, and keep cash reserves healthy.
  • They protect your business, building internal controls that catch errors and theft before they drain your accounts.
  • They translate data into decisions, turning reports into actionable moves on menu pricing, staffing, and growth. LastPass – Family or Org Password Vault

The Restaurant Financial Controller Job Description, Explained

Think of a controller as your restaurant’s financial quarterback. A bookkeeper records what happened. A controller tells you what it means and what to do next.

The core restaurant controller responsibilities include overseeing daily accounting, managing the month-end close, enforcing spending controls, preparing financial statements, and guiding budgets. According to the Bureau of Labor Statistics, financial managers—including controllers—earn strong six-figure median salaries, and you can review current restaurant controller responsibilities and salary data to benchmark your hiring plans.

Controller vs. Bookkeeper vs. Finance manager

Here’s the hierarchy in plain terms: bookkeepers record transactions, a restaurant finance manager analyzes them, and a controller owns the entire system—accuracy, compliance, controls, and strategy. For multi-location operators, a controller becomes non-negotiable, because inconsistent records across stores will quietly bury your profits.

Why Strong Restaurant Bookkeeping Is the Foundation

No controller can work magic on messy books. Daily sales tracking, vendor payment schedules, tip reporting, and payroll accuracy form the raw material of every financial decision you’ll make. Strong restaurant bookkeeping habits—recorded daily, categorized correctly, and reviewed weekly—give your controller clean data to work with.

Clean books aren’t optional—they’re also the law. The IRS requires businesses to maintain accurate records supporting income, deductions, and payroll, and solid restaurant accounting practices keep you audit-ready year-round. When your documentation is airtight, tax season becomes a formality instead of a fire drill.

Running a restaurant is hard enough without guessing at the numbers. Complete Controller gives you restaurant bookkeeping and controller-level financial clarity to manage cash flow, protect profits, and make smarter decisions.

POS Reconciliation and Internal Controls: Your Fraud Shield

This is where bookkeeping alone falls short—and where a controller earns their keep. In the ACFE’s 2024 global fraud study, the median occupational fraud loss was $145,000, and 32% of cases were tied directly to a lack of internal controls. Restaurants, with their heavy cash flow and high staff turnover, are prime targets.

A controller builds the defenses: separating duties so no single person handles cash from register to bank, reviewing voids and comps, and requiring approvals on vendor payments. Daily POS reconciliation—matching your point-of-sale totals against bank deposits and accounting records—catches discrepancies while they’re small and fixable, not after they’ve become a five-figure mystery.

The daily reconciliation rhythm

  1. Pull the POS end-of-day report and verify total sales by payment type.
  2. Match credit card batches against processor deposits.
  3. Count and verify cash deposits against register totals.
  4. Investigate and document any variance the same day.

Order matters here—skip a step, and errors compound.

Cash Flow, Budgeting, and Forecasting for Restaurants

Cash flow is oxygen. You can be profitable on paper and still miss payroll if timing goes sideways. The Federal Reserve’s Small Business Credit Survey consistently shows that uneven cash flow management is one of the top financial challenges small businesses face—and restaurants feel it more than most, with seasonal swings and weekly vendor terms.

Costs won’t sit still, either. Food-away-from-home prices rose 7.1% in 2023 after climbing 7.7% in 2022 (USDA). A controller tracks these shifts in real time, adjusting menu pricing, food cost targets, and budgets before inflation eats your margin. That’s the power of restaurant controller cash flow and forecasting—structured systems that turn financial oversight into a competitive advantage.

Financial reporting that actually drives decisions

Your controller should deliver a monthly package you can use: a P&L with prime cost percentages, a cash flow statement, a budget-versus-actual comparison, and location-level breakdowns if you operate multiple stores. Reports that sit unread are decoration. Reports that spark action are strategy.

Should You Hire a Restaurant Financial Controller—Or Outsource One?

Here’s my honest take after two decades in this industry: most independent restaurants don’t need a full-time, six-figure controller on payroll. They need controller-level expertise without the controller-level price tag. That’s exactly why I built Complete Controller—to give growing businesses access to expert financial oversight, cloud-based systems, and real-time reporting at a fraction of the in-house cost.

If you’re searching “hire restaurant financial controller near me,” widen the lens. Cloud-based controller services mean your financial expert doesn’t need a desk in your back office. They need access to your POS, your bank feeds, and your goals.

Signs you need controller-level support now:

  • You can’t state your food cost or labor percentage from last month
  • Your books close weeks late (or not at all)
  • You’re expanding to a second location
  • Cash flow surprises keep catching you off guard

The Bottom Line: Numbers Are Your Competitive Edge

A restaurant financial controller isn’t a luxury for big chains—it’s the difference between guessing and knowing. From bulletproof bookkeeping and daily POS reconciliation to fraud-fighting internal controls and forward-looking cash flow forecasting, this role protects the business you’ve poured your heart into. You didn’t open a restaurant to drown in spreadsheets. You opened it to build something that lasts.

Ready to get controller-level clarity without the full-time cost? Visit Complete Controller and connect with the team that pioneered cloud-based bookkeeping and controller services. Your numbers are trying to tell you something—let’s make sure you hear it. Download A Free Financial Toolkit

Frequently Asked Questions About Restaurant Financial Controller

What does a restaurant financial controller do?

They oversee all accounting operations—bookkeeping accuracy, POS reconciliation, budgeting, cash flow forecasting, internal controls, and financial reporting—so owners can make profitable, data-driven decisions.

How much does a restaurant financial controller cost?

Full-time controllers typically earn six figures, per Bureau of Labor Statistics data. Outsourced controller services deliver the same expertise for a fraction of that cost, making them ideal for independent and multi-unit operators.

What’s the difference between a restaurant bookkeeper and a controller?

A bookkeeper records transactions; a controller designs the financial system, enforces internal controls, analyzes results, and guides strategy. Controllers work above bookkeepers in the financial hierarchy.

Do small restaurants really need a financial controller?

Yes—especially with fraud losses averaging $145,000 per case and rising food costs. Small restaurants benefit most from outsourced controller services that scale with their needs.

How does a controller help with restaurant cash flow?

They forecast weekly cash needs, time vendor payments strategically, monitor seasonal trends, and maintain reserves—so you never get blindsided by payroll or supplier deadlines.

Sources

Complete Controller. America’s Bookkeeping Experts About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
author avatar
Jennifer Brazer Founder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Reviewed By: reviewer avatar Brittany McMillen
reviewer avatar Brittany McMillen
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.

Small Business Cash Flow Forecast

Small Business Cash Flow Forecasting:
How to Predict, Plan, and Protect Your Cash

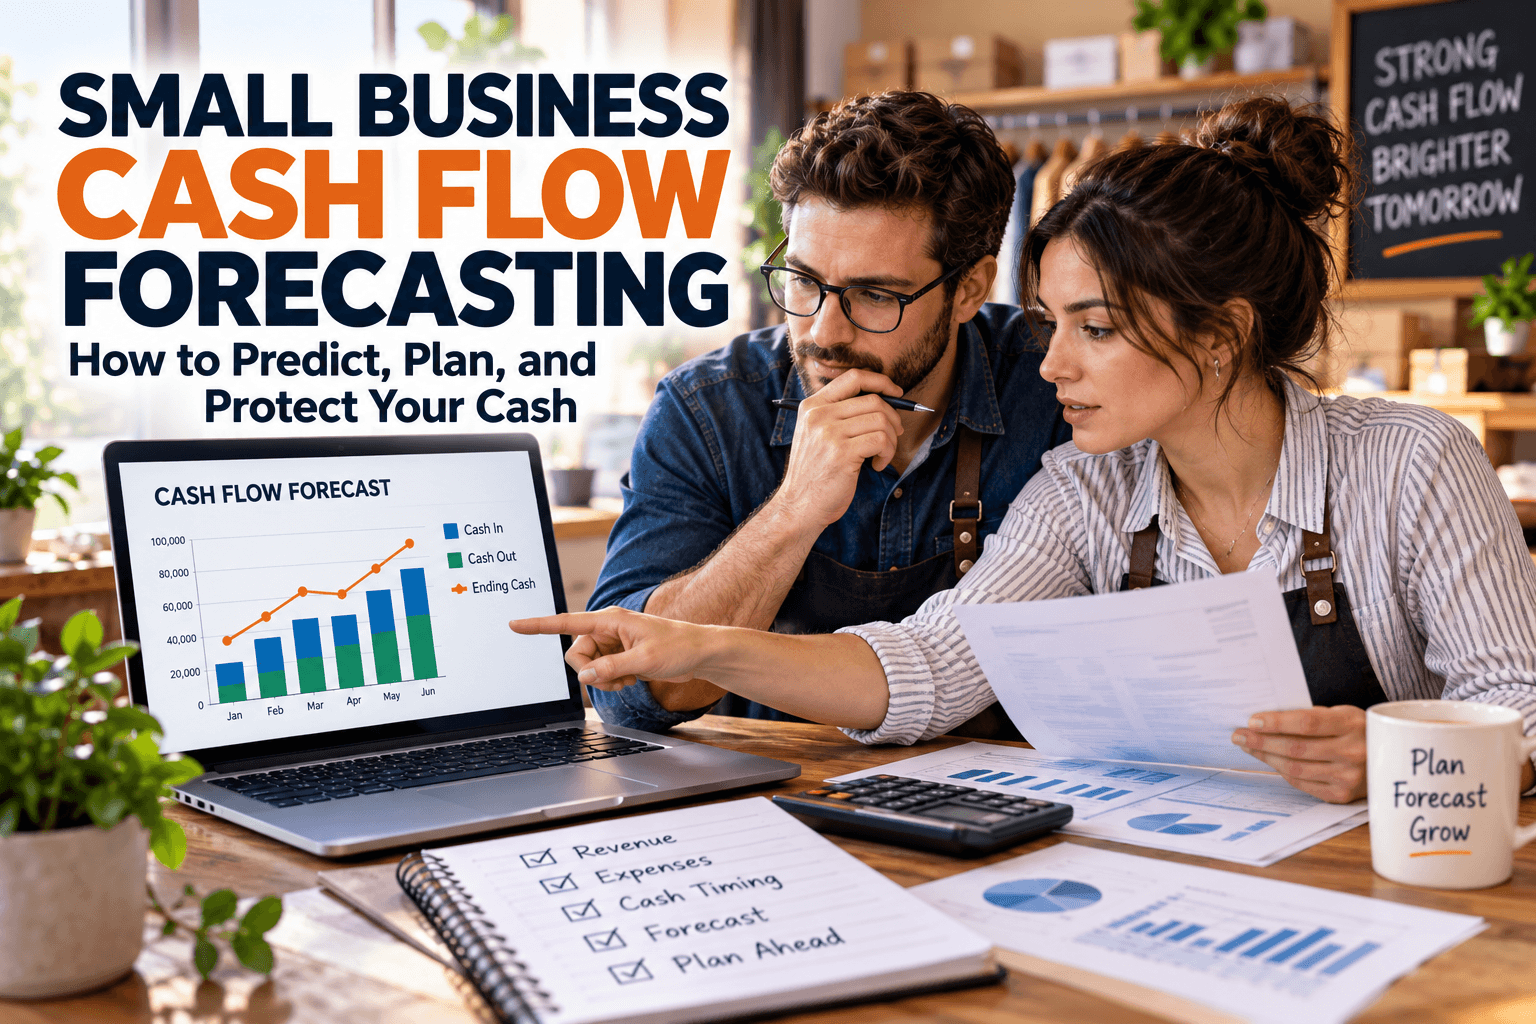
Small business cash flow forecasting is the process of estimating the money moving in and out of your business over a set period—weekly, monthly, or quarterly—so you can predict shortfalls, plan spending, and make confident decisions before problems hit your bank account.

Here’s what nobody tells you when you start a business: profit and cash are not the same thing. I’ve watched profitable companies scramble to make payroll because their cash was locked up in unpaid invoices. After 15+ years leading Complete Controller and serving thousands of small businesses, I can tell you this with certainty—the businesses that survive lean seasons aren’t always the most profitable ones. They’re the ones that see the future of their cash before it arrives. Let me show you how.

What is small business cash flow forecasting and how do you do it right?

  • Small business cash flow forecasting means projecting future cash inflows and outflows using your bookkeeping records, revenue estimates, and payment timing—done best on a rolling weekly or monthly basis.
  • Inflows include customer payments, loans, and investments—tracked by when cash actually lands, not when invoices are sent.
  • Outflows cover payroll, rent, inventory, taxes, and debt payments—mapped to their real due dates.
  • Forecast frequency matters: weekly forecasts catch short-term crunches; monthly forecasts guide strategy and growth planning.
  • Accuracy improves over time as you compare forecasts to actuals and adjust your assumptions. Complete Controller. America’s Bookkeeping Experts

Why Cash Flow Forecasting Matters More Than Your P&L

A profit-and-loss statement tells you where you’ve been. A cash flow forecast tells you where you’re going—and that’s the report that keeps the lights on. According to a widely cited U.S. Bank study, 82% of small business failures are tied to poor cash flow management or poor understanding of cash flow. That’s not a talent problem. That’s a visibility problem.

The Small Business Administration emphasizes that strong cash flow management is foundational to daily operations and long-term stability. I agree—and I’d take it further. Forecasting isn’t a finance chore. It’s a leadership tool. When you know your cash position 13 weeks out, you negotiate better, hire smarter, and sleep easier.

The cost of flying blind

QuickBooks research found that 61% of small businesses regularly struggle with cash flow, and nearly a third can’t pay vendors, loans, or employees on time as a result. Forecasting turns those surprises into line items you saw coming.

Start With Clean Books—Your Forecast Is Only as Good as Your Data

Every reliable forecast starts in the same place: accurate, current bookkeeping. If your transactions are miscategorized or three months behind, your forecast is fiction with a spreadsheet attached. Clean records give you real patterns—seasonal dips, payment lags, expense creep—that power both forecasting and small business budgeting.

What your books should tell you

Before you forecast, your records should clearly answer: How long do customers actually take to pay? Which expenses are fixed versus variable? What months historically run tight? At Complete Controller, we pioneered cloud-based bookkeeping precisely so business owners could answer these questions in real time, not at tax time.

Cash flow surprises are expensive. Complete Controller keeps your books accurate and current, giving you the financial clarity you need to forecast cash flow, plan ahead, and make smarter business decisions.

Build Your Forecast: Revenue In, Expenses Out

Now for the build itself. You don’t need fancy software to start—a simple small business cash flow projection spreadsheet works beautifully. What you need is honesty about timing.

Follow these steps in order:

  1. Choose your period. Start with a rolling 13-week forecast—long enough to plan, short enough to stay accurate.
  2. Project your inflows. Base revenue projections on signed contracts, historical sales, and realistic pipeline estimates—the same forward-looking assumptions the SBA recommends for business planning and funding conversations.
  3. Map your outflows. List every expense by due date: payroll, rent, inventory, loan payments, taxes.
  4. Calculate your net position. Beginning cash + inflows − outflows = ending cash for each period.
  5. Compare forecast to actuals. Review weekly, find the gaps, and refine your assumptions.

Don’t forget scenario planning

Build three versions: best case, expected case, and worst case. Then run a cash runway analysis—if revenue dropped 25% tomorrow, how many weeks could you operate? Startups especially need this number tattooed on their brains.

Master the Timing Game: Receivables and Payables

Here’s where forecasts live or die—timing. An invoice sent isn’t cash received. Xero’s research shows small businesses wait an average of two weeks beyond payment terms to get paid, and that lag can quietly strangle an otherwise healthy company.

Tighten your accounts receivable forecasting by setting clear payment terms upfront, invoicing immediately, and offering early-payment incentives. On the flip side, accounts payable forecasting means scheduling your outgoing payments strategically—paying on time, but not weeks early when that cash could be working for you.

Track your cash conversion cycle

The gap between paying suppliers and collecting from customers is your cash conversion cycle. Shrink it, and your forecast improves automatically because less cash sits in limbo.

Use Your Forecast to Strengthen Working Capital

Your forecast isn’t just a prediction—it’s a decision engine. Working capital—current assets minus current liabilities—measures your short-term financial health, and your forecast shows you exactly when that cushion thins out.

Smart working capital management means using forecast data to time inventory purchases, secure a line of credit before you need it, and decide when you can genuinely afford that next hire. Lenders love a business owner who walks in with a 13-week forecast. It signals you’re running the business—not letting the business run you.

Improve Forecasting Accuracy Over Time

Your first forecast will be wrong. That’s fine—mine was too. Accuracy is a muscle you build through repetition.

  • Review weekly. A weekly cash flow forecast for small business owners catches drift before it becomes a crisis.
  • Track forecast vs. actual variance. If you’re consistently off on collections, adjust your assumptions, not your hopes.
  • Update for real events. New contract signed? Vendor raised prices? Update the forecast that day.
  • Automate the data feed. Cloud bookkeeping pulls live transaction data into your forecast, cutting manual errors dramatically.

The goal isn’t a perfect forecast. It’s a forecast that gets less wrong every single week.

Conclusion: Your Cash Deserves a Crystal Ball

Cash flow forecasting turns anxiety into strategy. Start with clean books, project inflows and outflows by actual timing, run scenarios, and refine weekly. The businesses I’ve seen thrive over two decades aren’t lucky—they’re informed. You deserve that same clarity.

If you’re ready to build forecasts on a foundation of accurate, real-time financials, the team at Complete Controller is here to help. We pioneered cloud-based bookkeeping and controller services so business owners like you can see your cash clearly—and lead boldly. CorpNet. Start A New Business Now

Frequently Asked Questions About Small Business Cash Flow Forecasting

How far ahead should a small business forecast cash flow?

A rolling 13-week forecast is the sweet spot for operational decisions, paired with a 12-month forecast for strategic planning. Update both regularly as actuals come in.

What’s the difference between a cash flow forecast and a budget?

A budget sets spending targets for the year; a cash flow forecast predicts the timing of money entering and leaving your account. You need both—they answer different questions.

How do I forecast cash flow for a startup with no history?

Use signed contracts, industry benchmarks, and conservative pipeline estimates. Build worst-case scenarios and track your cash runway monthly until you have real data to refine against.

What tools do I need for small business cash flow forecasting?

A spreadsheet template works to start. As you grow, cloud accounting software with live bank feeds improves accuracy and saves hours of manual entry.

Why are my cash flow forecasts always wrong?

Usually it’s payment timing—assuming customers pay on invoice terms when they actually pay weeks later. Track your real average collection time and forecast from that number instead.

Sources

Download A Free Financial Toolkit About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
author avatar
Jennifer Brazer Founder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Reviewed By: reviewer avatar Brittany McMillen
reviewer avatar Brittany McMillen
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.

SMB Financial Statement Preparation

SMB Financial Statement Preparation:
Your Complete Guide to Getting It Right

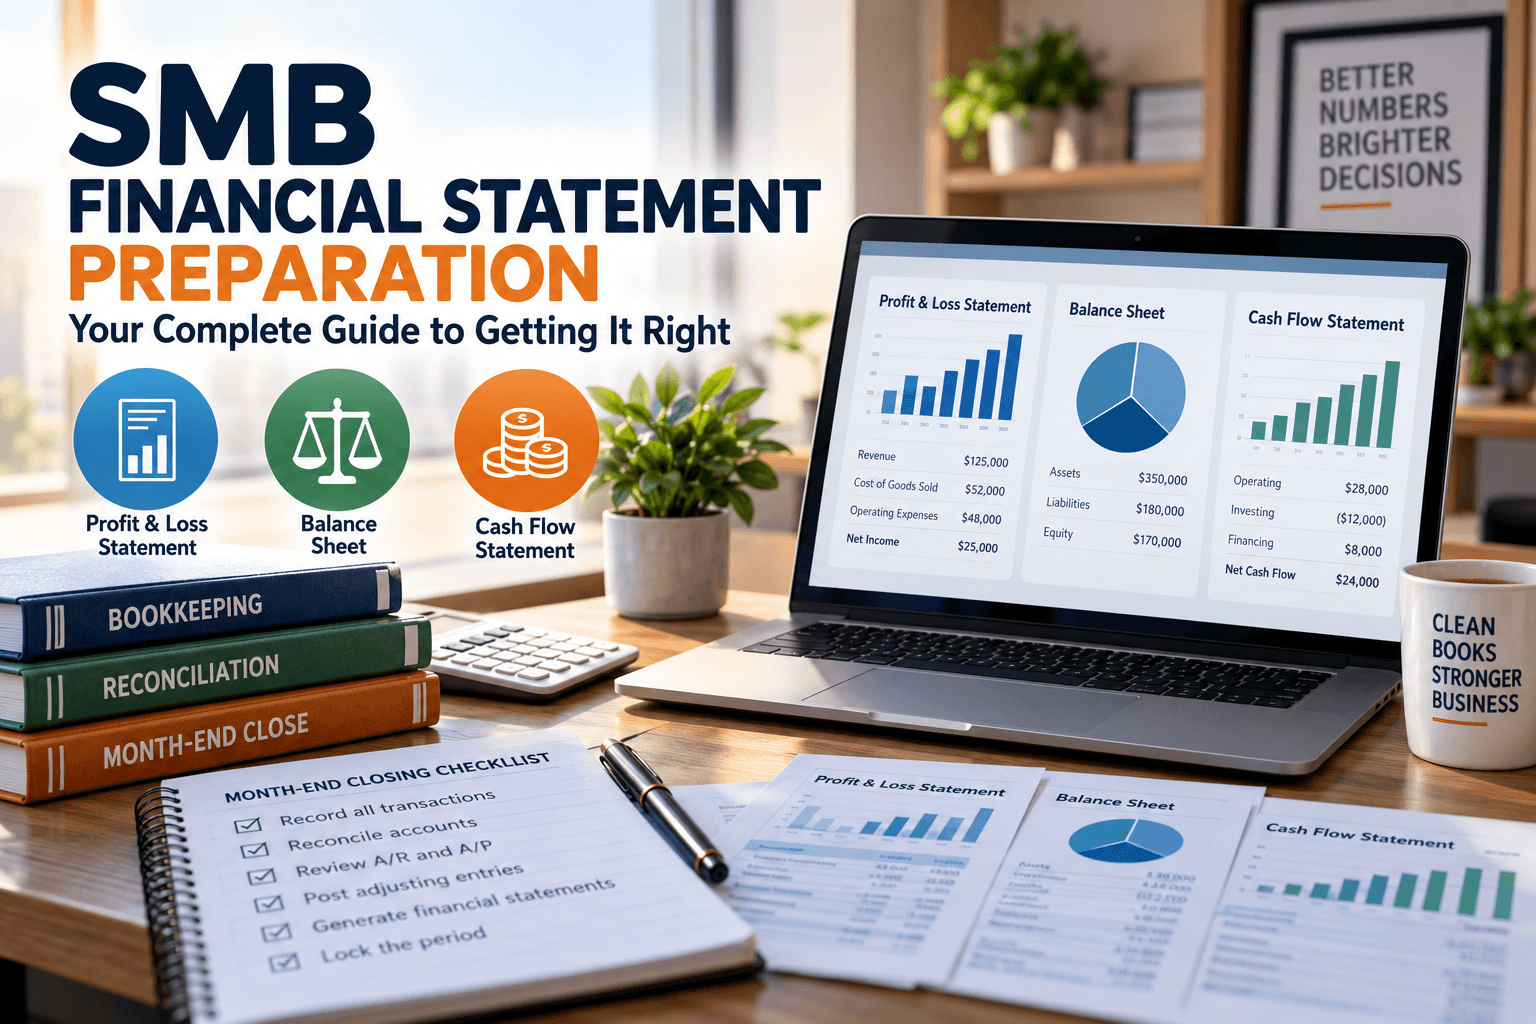
SMB financial statement preparation is the process of organizing your business’s financial data into three core reports—the profit and loss statement, balance sheet, and cash flow statement—through accurate bookkeeping, account reconciliation, and a consistent month-end closing routine.

Here’s what nobody tells you: most small business owners don’t struggle with financial statements because the math is hard. They struggle because their books are messy, their process is inconsistent, and they’re preparing statements reactively instead of proactively. After more than two decades leading Complete Controller and helping thousands of businesses clean up their financial reporting, I can tell you this—the businesses that master statement preparation don’t just survive tax season. They make smarter decisions all year long.

What is SMB financial statement preparation and how do you do it right?

  • SMB financial statement preparation means transforming clean, reconciled bookkeeping data into three tax-ready reports: the profit and loss statement, balance sheet, and cash flow statement.
  • Accurate bookkeeping is the foundation—every statement is only as reliable as the records behind it.
  • Reconciliation verifies that your books match your bank accounts before you report anything.
  • Month-end closing locks in your numbers on a consistent schedule so statements stay comparable over time.
  • Compliance standards like GAAP or IFRS keep your reports credible with lenders, investors, and the IRS. CorpNet. Start A New Business Now

Why Financial Statements Matter More Than You Think

Your financial statements are not paperwork—they’re your business’s story told in numbers. Lenders read them before approving loans. Investors read them before writing checks. And you should be reading them before every major decision.

The U.S. Small Business Administration emphasizes strong financial reporting for small businesses as a cornerstone of business management—and for good reason. Studies consistently show that cash flow problems contribute to the majority of small business failures, and you cannot manage what you don’t measure. Your statements are the measurement.

Once you understand the “why,” the next step is building the foundation those statements rest on.

Start With Clean Books: The Foundation of Every Statement

You can’t build a solid house on sand, and you can’t build accurate statements on sloppy books. Strong small business accounting habits—categorizing transactions weekly, separating business and personal expenses, and keeping digital records of receipts—make statement preparation almost effortless.

Habits that keep your books statement-ready

  • Record transactions as they happen, not at quarter’s end
  • Keep business and personal finances in completely separate accounts
  • Use cloud-based accounting software so your data is current and accessible
  • Store receipts and invoices digitally with clear naming conventions

When your books are clean, the next step—reconciliation—becomes a quick check instead of a forensic investigation.

Tired of wondering if your numbers are actually right? Let Complete Controller handle your SMB financial statement preparation so you can spend less time fixing the books and more time using them to make smarter business decisions.

Reconcile Before You Report

Reconciliation is the truth test. Before you prepare a single statement, bookkeeping reconciliation confirms that your ledger matches your bank statements, credit card statements, and loan balances. Skip this step, and you risk reporting numbers that simply aren’t real.

Here’s my rule: if it hasn’t been reconciled, it hasn’t happened. Reconcile monthly at minimum. Catch duplicate entries, missed transactions, and bank errors while they’re fresh—because a $200 discrepancy in March becomes a nightmare in December.

With reconciled accounts in hand, you’re ready to close the books.

Master the Month-End Closing Process

A disciplined month-end closing routine is what separates businesses with reliable statements from those scrambling every April. Closing the books means finalizing all entries for the period so your statements reflect a complete, locked picture.

Your month-end closing checklist

  1. Record all revenue and expenses for the period
  2. Reconcile bank, credit card, and loan accounts
  3. Review accounts receivable and payable for accuracy
  4. Post adjusting entries (depreciation, accruals, prepaid expenses)
  5. Review the trial balance for anything unusual
  6. Lock the period and generate your statements

The order matters here—generate statements before reconciling, and you’ll be redoing everything. Follow the sequence, and preparation becomes routine instead of chaos.

Preparing the Three Core Financial Statements

Now for the main event. Each statement answers a different question about your business.

The profit and loss statement

Your P&L answers: Am I making money? It summarizes revenue, cost of goods sold, and operating expenses over a period. Prepare it monthly and compare against prior periods—trends tell you more than any single month ever will.

The balance sheet

Your balance sheet answers: What do I own and owe? It’s a snapshot of assets, liabilities, and equity at a single point in time. If Assets ≠ Liabilities + Equity, something’s wrong—go back to reconciliation.

The cash flow statement

Your cash flow statement answers: Where is my money actually going? Profit on paper means nothing if cash isn’t in the bank. This statement tracks cash from operations, investing, and financing—and it’s the one most owners skip at their peril.

Stay Compliant and Tax-Ready Year-Round

Consistency and compliance turn good statements into credible ones. Following recognized standards like GAAP and IFRS compliance for SMB ensures your reports are comparable, understandable, and trusted by outside parties. The IFRS for SMEs standard was built specifically for smaller entities—proof that professional-grade reporting isn’t just for corporations.

On the tax side, the IRS is clear about maintaining tax-ready financial statements for small businesses through solid recordkeeping. Keep supporting documents organized, retain records for the required periods, and your tax preparation becomes a handoff—not a crisis.

Conclusion: Turn Your Numbers Into Your Advantage

SMB financial statement preparation comes down to a simple truth: clean books, reconciled accounts, and a consistent month-end close produce statements you can actually trust. Master the P&L, balance sheet, and cash flow statement, keep your reporting compliant, and you’ll stop guessing and start knowing where your business stands.

I built Complete Controller because I believe every small business deserves big-business financial clarity—without the big-business price tag. If you’re ready to hand off the bookkeeping and get expert-prepared, tax-ready statements every month, visit Complete Controller and let the team that pioneered cloud-based bookkeeping and controller services show you what’s possible. Complete Controller. America’s Bookkeeping Experts

Frequently Asked Questions About SMB Financial Statement Preparation

What financial statements does a small business need?

The three essentials are the profit and loss statement, balance sheet, and cash flow statement. Together they show profitability, financial position, and cash movement.

How often should an SMB prepare financial statements?

Monthly is the gold standard. Monthly statements catch problems early and make quarterly and annual reporting nearly effortless.

Can I prepare financial statements myself?

Yes, with cloud accounting software and disciplined bookkeeping. However, many owners outsource to bookkeeping and controller services to ensure accuracy and save time.

What’s the difference between bookkeeping and financial statement preparation?

Bookkeeping records daily transactions; statement preparation transforms those reconciled records into formal reports. One feeds the other.

Do small businesses have to follow GAAP or IFRS?

Most private SMBs aren’t legally required to, but following GAAP or IFRS for SMEs makes your statements credible to lenders, investors, and buyers.

Sources

Download A Free Financial Toolkit About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
author avatar
Jennifer Brazer Founder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Reviewed By: reviewer avatar Brittany McMillen
reviewer avatar Brittany McMillen
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.

Family Business Financial Governance

Family Business Financial Governance:
Building a Framework That Protects Your Legacy

Family business financial governance is the system of financial controls, board oversight, policies, and accountability structures that keeps a family-owned company transparent, compliant, and financially healthy across generations. Get it right, and you protect both the business and the relationships behind it.

Here’s what most family business owners don’t want to admit: the biggest financial risks usually aren’t from competitors or the economy—they come from inside the house. Blurred lines between family money and business money, handshake agreements instead of documented policies, and “we trust each other” standing in for actual internal controls. I’ve spent over two decades helping business owners build financial clarity, and I can tell you this—trust is not a control system. Love your family, absolutely. But govern your finances like a professional.

What is family business financial governance and how do you build it?

  • Family business financial governance combines a financial control framework, board oversight, documented policies, internal controls monitoring, and compliance safeguards to protect the company’s finances and legacy.
  • A financial control framework sets the rules for budgets, spending authority, and reporting so decisions aren’t made on emotion.
  • Board oversight and audit committee governance add independent eyes to financial reporting and risk management.
  • Internal controls and anti-fraud measures catch errors and misconduct before they become crises.
  • Succession and ownership planning ensures the governance system outlives any single family member. LastPass – Family or Org Password Vault

Why Family Business Financial Governance Matters More Than You Think

Family businesses aren’t a niche—they’re the engine of the economy. According to the Family Business Alliance, family businesses create 64% of U.S. GDP and employ 62% of the U.S. workforce. That’s staggering influence, and it comes with real responsibility.

Yet many of these companies run on informal habits that would make a corporate CFO break out in hives. When Dad approves his own expense reports and the family Thanksgiving doubles as the annual budget meeting, you don’t have governance—you have hope. And hope is not a regulatory compliance strategy.

The good news? Formal governance doesn’t kill the family culture. It protects it. Clear financial rules mean fewer arguments, cleaner audits, and a business that banks, investors, and the next generation can actually trust.

Designing Your Financial Control Framework

Every strong governance system starts with a documented financial control framework—the written playbook for how money moves through your business. This is where budgetary control systems and financial policy and procedures come to life.

The core elements you need

  1. Spending authority limits – Define who can approve what, and at what dollar amount. Yes, even family members. Especially family members.
  2. Budgeting and forecasting cadence – Annual budgets, quarterly reviews, monthly variance checks.
  3. Separation of duties – The person writing checks shouldn’t also reconcile the bank statement.
  4. Documented financial policies – Compensation, dividends, loans to family members, and related-party transactions all get written rules.

When these elements exist on paper—not just in someone’s head—you’ve converted family goodwill into institutional strength. That framework only works, though, if someone is watching over it. That’s where the board comes in.

Board Oversight and Audit Committee Governance

Strong board-level financial oversight processes are what separate family firms that endure from those that implode in generation two. The OECD’s principles of corporate financial governance emphasize board accountability, transparency, and independent oversight—standards that apply whether you’re a global giant or a third-generation manufacturer.

What effective board oversight looks like

Bring in at least one or two independent directors who aren’t at the family dinner table. They ask the questions family members won’t. Establish an audit committee—even an informal one—responsible for financial reporting oversight, reviewing statements, meeting with external accountants, and monitoring risk management governance.

For a real-world model, look at Ford. Its 2024 proxy statement shows Ford family members hold Class B shares carrying 40% of general voting power, even though public investors own most of the stock. The lesson: you can structure ownership and voting rights to preserve family control while embracing professional governance and public accountability. Structure isn’t the enemy of legacy—it’s the guardian of it.

Family trust is priceless—but your finances still need structure. Complete Controller helps family businesses build clearer books, stronger controls, and financial confidence that lasts for generations.

Internal Controls Monitoring and Reporting Accuracy

Governance lives or dies in the daily details. Regular internal controls monitoring—reconciling accounts, reviewing variances, investigating discrepancies—is how you catch small problems before they become expensive ones.

The U.S. Government Accountability Office’s Green Book sets the gold standard for internal control compliance reporting, covering the control environment, risk assessment, and monitoring activities. You don’t need to be a government agency to borrow its wisdom: design controls, document them, test them, and fix what breaks.

Monthly reconciliations, timely financial statements, and a clear paper trail turn your books from a guessing game into a decision-making tool. And when reporting is reliable, compliance gets a whole lot easier—which brings us to the regulatory side.

Regulatory Compliance and Ethics Safeguards

Even privately held family firms benefit from public-company discipline. The Sarbanes-Oxley Act—the foundation of SOX compliance—requires executive certification of financial statements and documented internal controls. Family businesses that adopt SOX-style habits are audit-ready, lender-ready, and sale-ready at any moment.

Ethics matter just as much as rules. Strong ethics and anti-fraud controls protect the business and the family from the devastating scenario nobody wants to imagine: misconduct by someone with a shared last name. Preventive controls, anonymous reporting channels, and a zero-tolerance policy applied equally to everyone—that’s governance risk compliance (GRC) with heart and backbone.

Succession Planning: Governance That Outlives You

Here’s the sobering truth: PwC’s Global Family Business Survey found only 34% of family businesses have a robust, documented, and communicated succession plan. That means two-thirds are betting their legacy on improvisation.

Your governance framework should answer these questions before a crisis forces the issue:

  • Who inherits ownership, and how are shares valued and transferred?
  • Who takes financial leadership roles, and what qualifications are required?
  • How are non-active family members compensated or bought out?
  • What happens to voting control across generations?

A documented succession plan tied to your financial governance structure is the single greatest gift you can leave the next generation. It transforms an emotional transition into an orderly one.

Conclusion: Govern Like a Pro, Lead Like a Family

Family business financial governance isn’t red tape—it’s legacy insurance. A documented financial control framework, independent board oversight, disciplined internal controls, real compliance safeguards, and a communicated succession plan turn family trust into institutional strength. I’ve watched businesses transform when they stop running on habit and start running on structure—and the family relationships get stronger, not weaker.

Ready to build governance that protects what you’ve worked so hard to create? Visit Complete Controller for expert guidance from the team that pioneered cloud-based bookkeeping and controller services. Your legacy deserves nothing less. ADP. Payroll – HR – Benefits

Frequently Asked Questions About Family Business Financial Governance

What is family business financial governance?

It’s the system of financial controls, board oversight, policies, and accountability structures that keeps a family-owned company transparent, compliant, and financially sound across generations.

Why do family businesses need formal financial controls?

Informal, trust-based practices create risk of errors, fraud, and family conflict. Documented controls protect both the business’s finances and the family’s relationships.

Does a family business need an independent board?

While not legally required for private firms, independent directors add objectivity, challenge assumptions, and strengthen financial oversight—key advantages as the business grows.

How does succession planning fit into financial governance?

Succession planning documents how ownership, voting rights, and financial leadership transfer between generations. Only 34% of family businesses have a robust, communicated plan, per PwC.

Do SOX compliance rules apply to private family businesses?

SOX legally applies to public companies, but its principles—executive accountability and documented internal controls—are best practices that make private family firms audit-ready and lender-ready.

Sources

Complete Controller. America’s Bookkeeping Experts About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
author avatar
Jennifer Brazer Founder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Reviewed By: reviewer avatar Brittany McMillen
reviewer avatar Brittany McMillen
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.
Mid-Market Business Controller Guide

Mid-Market Business Controller:
The Role That Turns Growing Companies Into Well-Run Companies

A mid-market business controller is the senior finance professional who owns your company’s accounting accuracy, internal controls, budgeting, and financial reporting—translating raw numbers into decisions leadership can actually trust. If your revenue sits between $10 million and $1 billion, this is the person who keeps your financial engine running clean while your CFO (or you, the owner) steers strategy.

Here’s what most growing companies get wrong: they treat the controller role as a luxury hire instead of a load-bearing wall. I’ve spent over two decades watching businesses scale beautifully—and watching others stall out—and the difference almost always traces back to whether someone credible owned the numbers. Consider this your roadmap to getting it right.

What is a mid-market business controller and why does the role matter?

  • A mid-market business controller leads accounting operations, financial reporting, internal controls, and budgeting for companies with roughly $10M–$1B in revenue, bridging day-to-day bookkeeping and executive strategy.
  • Scope: They own the month-end close, reconciliations, compliance, and the systems that make financial data reliable.
  • Impact: The U.S. middle market represents about one-third of private-sector GDP and employment (National Center for the Middle Market), so these controllers support real economic weight.
  • Position: The controller sits between your bookkeeping team and your CFO—accuracy below, strategy above.
  • Flexibility: The role can be filled full-time, fractionally, or through outsourced business controller services depending on your stage. Cubicle to Cloud virtual business

The Core Responsibilities of a Business Controller

Think of your controller role in three layers: record it right, control it tight, and report it fast.

The foundation is management accounting—the internal discipline of measuring costs, margins, and performance so leaders can plan and evaluate with confidence. If you want the textbook version, management accounting is the study of exactly this: using financial data for internal decision-making rather than just external compliance. A great controller lives here daily.

From bookkeeping to decision support

Bookkeepers record transactions. Controllers make those transactions mean something. That includes month-end close discipline, reconciliations, variance analysis, and clean financial reporting delivered on a schedule leadership can set a watch by. When your close takes 25 days, you’re managing your business with a month-old map. A strong controller gets you answers in days, not weeks.

Growing past basic bookkeeping? Complete Controller gives you controller-level financial clarity, reporting, and support—without adding another full-time hire.

Internal Controls: Your Quiet Competitive Advantage

Internal controls aren’t red tape—they’re the difference between a business that knows its numbers and one that hopes they’re right.

This became a board-level issue after the Sarbanes-Oxley Act. In 2003, the SEC adopted rules requiring public companies to include management’s assessment of internal controls over financial reporting in annual reports. You may not be public—but lenders, investors, and acquirers now expect that same rigor from mid-market firms. Your controller builds it: segregation of duties, approval workflows, fraud prevention, and audit readiness.

Translation: when the bank asks hard questions or a buyer opens due diligence, a controller means you answer in hours, not weeks.

Budgeting, Forecasting, and Cash Flow: Where Controllers Earn Their Keep

Growth eats cash. That’s not a warning—it’s math. Every new contract, hire, and inventory order pulls dollars out the door before revenue lands.

A mid-market controller builds the budgeting and forecasting discipline the SBA rightly calls essential for growing businesses. That means rolling forecasts instead of static annual budgets, scenario planning before big commitments, and honest variance reviews every month.

Cash visibility keeps you in business

Profitable companies fail from cash constraints all the time. Your controller owns cash flow management—monitoring working capital, receivables aging, and liquidity runway so you see a crunch coming months out, not the week payroll gets tight. That visibility is the difference between negotiating from strength and scrambling.

When Should You Hire or Upgrade Your Controller?

Timing matters more than titles. Here are the signals, in the order they usually appear:

  1. Your close drags past 15 days, and reports arrive too late to act on.
  2. You’re making six-figure decisions on gut feel because the data isn’t trustworthy.
  3. Lenders or investors request financials you can’t produce confidently.
  4. Your bookkeeper is drowning in complexity that outgrew their role.
  5. You’re planning a raise, acquisition, or exit and need audit-ready books.

Move quickly when you see these—the market won’t wait for you. The U.S. Bureau of Labor Statistics projects financial manager jobs to grow 17% from 2023 to 2033, much faster than average. Senior finance talent is in demand, and competition for it is real.

Full-Time, Fractional, or Outsourced: Choosing Your Controller Model

Here’s where I challenge the old playbook: you don’t need a $180,000 full-time hire to get controller-level rigor. Many mid-market firms get better outcomes—and better economics—through outsourced business controller services that deliver senior expertise, cloud-based systems, and built-in redundancy at a fraction of the cost.

Matching the model to your stage

A full-time controller makes sense when complexity is constant and high—multiple entities, heavy compliance, daily strategic finance needs. Fractional or interim business controllers fit companies in transition. Outsourced controller teams shine for firms that want enterprise-grade mid-market finance operations without carrying enterprise-grade payroll. At Complete Controller, we pioneered cloud-based bookkeeping and controller services precisely because we saw this gap—growing companies deserved big-company financial discipline without big-company overhead.

Conclusion: Strong Numbers Build Strong Companies

A mid-market business controller isn’t overhead—it’s infrastructure. The right controller gives you accurate books, tight internal controls, forward-looking forecasts, and cash visibility that lets you lead with confidence instead of guessing. Whether you hire in-house, go fractional, or partner with an outsourced team, the takeaway is the same: own your numbers before they own you.

Ready to bring controller-level clarity to your business? Visit Complete Controller for expert guidance from the team that pioneered cloud-based bookkeeping and controller services. Your numbers deserve it—and so do you. Complete Controller. America’s Bookkeeping Experts

Frequently Asked Questions About Mid-Market Business Controller

What does a mid-market business controller do?

They oversee accounting operations, financial reporting, internal controls, budgeting, and cash flow management for companies with roughly $10M–$1B in revenue, ensuring leadership has accurate, timely financial data.

What’s the difference between a controller and a CFO?

A controller ensures the numbers are accurate and processes are sound; a CFO uses those numbers to drive strategy, capital raising, and long-term planning. Controllers look back and inward; CFOs look forward and outward.

When should a growing company hire a controller?

When the month-end close exceeds 15 days, financial data isn’t trusted for major decisions, or lenders and investors need reliable reporting—typically as revenue passes $10 million or complexity spikes.

Can a controller role be outsourced?

Yes. Outsourced and fractional controller services provide senior-level expertise, cloud-based systems, and audit-ready processes at significantly lower cost than a full-time hire—ideal for many mid-market firms.

How does a controller improve cash flow?

By forecasting cash needs, monitoring receivables and payables, managing working capital, and flagging liquidity risks early so leadership can act before a crunch hits.

Sources

ADP. Payroll – HR – Benefits About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
author avatar
Jennifer Brazer Founder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Reviewed By: reviewer avatar Brittany McMillen
reviewer avatar Brittany McMillen
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.
Financial Metrics for Startups Guide

Financial Metrics for Startups:
The Numbers That Keep Your Business Alive

Financial metrics for startups are the measurable indicators—like burn rate, runway, customer acquisition cost (CAC), lifetime value (LTV), gross margin, and monthly recurring revenue (MRR)—that tell you whether your business is growing sustainably or quietly running out of road.

Here’s what two decades of working with founders has taught me: most startups don’t fail because of bad ideas. They fail because nobody was watching the numbers. CB Insights found that 38% of failed startups cited running out of cash or failing to raise new capital as a reason they shut down. That’s not a rounding error—that’s the number one killer. The good news? Every metric that could have saved those companies is knowable, trackable, and fixable. Let me show you which ones deserve your attention.

What are financial metrics for startups and which ones matter most?

  • Financial metrics for startups are performance indicators covering cash (burn rate, runway), growth (MRR, revenue growth rate), efficiency (CAC, LTV, gross margin), and retention (churn, cohort behavior).
  • Cash metrics tell you how long you can survive—runway is your countdown clock.
  • Growth metrics show investors and your team whether momentum is real or wishful.
  • Unit economics reveal if each customer makes you money or costs you money.
  • Retention metrics prove whether your product actually keeps the customers you paid to acquire. Complete Controller. America’s Bookkeeping Experts

Why Startup KPIs Are Your Early Warning System

Think of your metrics like the gauges on a dashboard. You wouldn’t drive cross-country with the fuel gauge covered in tape—yet founders do the equivalent every day by skipping monthly financial reviews.

The foundation isn’t fancy software or an expensive CFO. It’s clean, consistent bookkeeping. When your books are accurate and current, every KPI you calculate is trustworthy. When they’re not, you’re making decisions on fiction. That’s why I always point founders to the basics of financial metrics for startups before anything else. Garbage in, garbage out—and in startup land, garbage out can mean game over.

With that foundation in place, the first gauge to watch is cash.

Burn Rate and Runway: How Long Can You Survive?

Burn rate is how much cash you spend each month beyond what you bring in. Runway is your cash on hand divided by that burn rate—the number of months you have left before the tank hits empty.

If you have $300,000 in the bank and burn $30,000 monthly, you have ten months of runway. Simple math, massive consequences. Before you can trust that math, though, you need honest expense estimates—the SBA offers a solid framework for how to calculate startup burn rate and runway starting with realistic startup costs.

The Airbnb lesson in financial resilience

Even giants aren’t immune. In May 2020, Airbnb CEO Brian Chesky announced that revenue was forecast to be less than half of 2019 levels, and the company cut about 1,900 people—nearly 25% of its workforce. If Airbnb has to manage runway and revenue risk that aggressively, your startup absolutely does too. Pair your burn rate with strong cash flow forecasting metrics for startups so hiring, spending, and fundraising decisions are grounded in reality, not hope.

Surviving is step one. Growing profitably is where unit economics come in.

Unit Economics: CAC, LTV, and the Math of Every Customer

Unit economics answer one blunt question: does each customer make you money?

Customer acquisition cost (CAC) is your total sales and marketing spend divided by new customers acquired. Lifetime value (LTV) is the total gross profit a customer generates over their relationship with you. Harvard Business School Online offers an excellent breakdown of why customer acquisition cost CAC sits at the heart of sustainable growth.

The benchmark most investors want to see is an LTV:CAC ratio of 3:1 or better. Below that, you’re buying growth you can’t afford. And here’s the part founders miss—CAC isn’t just a finance number. It’s a marketing execution number. Tying your customer acquisition cost CAC to a scalable, measurable marketing strategy is how the ratio improves over time.

Once you know what a customer is worth, the next question is whether they stick around.

Churn, Retention, and Cohort Analysis: The Truth About Your Growth

New revenue is exciting. Retained revenue is a business.

Churn rate—the percentage of customers or revenue you lose each month—quietly erodes everything your marketing dollars build. A SaaS startup adding $10K in new MRR while churning $8K isn’t growing; it’s running on a treadmill.

Why cohorts beat averages

Averages lie. Cohort analysis groups customers by when they signed up and tracks their behavior over time, revealing whether your newest customers retain better or worse than earlier ones. If your January cohort keeps 80% of customers at month six but your June cohort keeps 60%, something changed—and averages would have hidden it completely.

Retention feeds directly into the balance every investor scrutinizes: growth versus profitability.

Want a clearer picture of your startup’s cash flow, runway, and financial health? Complete Controller can help you keep the numbers organized so you can focus on what comes next.

The Rule of 40: Balancing Growth and Profit Like a Pro

Brad Feld helped popularize the SaaS “Rule of 40,” which says your revenue growth rate plus your profit margin should add up to 40% or more. Growing 60% while losing 20%? You pass. Growing 10% while earning 10%? You’ve got work to do.

I love this rule because it kills a false debate. You don’t have to choose between growth and profitability—you have to balance them, and the Rule of 40 gives you one number to hold yourself accountable. Combine it with gross margin and revenue growth rate tracking, and you have a genuinely investor-ready dashboard.

Building Your Investor-Ready Metrics Dashboard

You don’t need fifty metrics. You need the right handful, reviewed monthly, in this order:

  1. Cash on hand and runway – survival first, always.
  2. Burn rate – gross and net, trended over time.
  3. MRR and revenue growth rate – your momentum story.
  4. CAC, LTV, and gross margin – your efficiency story.
  5. Churn and cohort retention – your durability story.

Review these on the same day every month. Consistency turns numbers into narratives, and narratives are what convince investors—and yourself—that the business is working.

Conclusion

Financial metrics for startups aren’t busywork—they’re the difference between founders who steer and founders who drift. Watch your burn rate and runway like your life depends on it (your company’s does), demand healthy unit economics from every customer, track retention through cohorts, and balance it all with the Rule of 40. I’ve watched hundreds of businesses transform once they stopped guessing and started measuring. Yours can too. For expert guidance from the team that pioneered cloud-based bookkeeping and controller services, visit Complete Controller—we’ll help you build the financial clarity your startup deserves. ADP. Payroll – HR – Benefits

Frequently Asked Questions About Financial Metrics for Startups

What are the most important financial metrics for startups?

Burn rate, runway, MRR, revenue growth rate, CAC, LTV, gross margin, and churn. Cash metrics come first—38% of failed startups cite running out of cash.

How do I calculate my startup’s burn rate?

Subtract monthly revenue from monthly expenses. If you spend $50K and earn $20K, your net burn is $30K per month.

What is a good LTV to CAC ratio for early-stage startups?

Aim for 3:1 or higher—each customer should generate at least three times what you spent to acquire them.

What is the Rule of 40 in SaaS?

Your revenue growth rate plus profit margin should equal 40% or more, signaling a healthy balance of growth and profitability.

How often should startups review financial metrics?

Monthly at minimum, with cash and runway checked weekly during tight periods or fundraising.

Sources

LastPass – Family or Org Password Vault About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
author avatar
Jennifer Brazer Founder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Reviewed By: reviewer avatar Brittany McMillen
reviewer avatar Brittany McMillen
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.
Decision-Making Financial Reports

Decision-Making Financial Reports:
How Smart Leaders Turn Numbers Into Action

Decision-making financial reports are structured financial documents—like income statements, cash flow analyses, budgets, and KPI dashboards—that give business leaders the accurate, timely data they need to make confident strategic choices. When built and read correctly, these reports transform raw numbers into a roadmap for growth, profitability, and risk management.

Here’s what I’ve learned after two decades helping thousands of business owners: most leaders aren’t short on data—they’re drowning in it. The problem isn’t access. It’s clarity. If you’ve ever stared at a spreadsheet at 11 p.m. wondering whether you can afford that new hire, this article is for you. Let’s fix how you use your numbers, once and for all.

What are decision-making financial reports and how do you use them?

  • Decision-making financial reports include income statements, balance sheets, cash flow reports, budgets, forecasts, and KPI dashboards—used together to guide strategy, spending, hiring, and risk decisions.
  • Core statements (income, balance sheet, cash flow) show where you’ve been and where you stand today.
  • Forward-looking reports like budgets and forecasts help you plan what’s next with confidence instead of guesswork.
  • KPI dashboards distill everything into a handful of metrics you can check weekly, not quarterly.
  • Risk and variance reports flag problems early—before they become expensive surprises. ADP. Payroll – HR – Benefits

The Big Three: Core Statements Every Leader Must Read

Before you can make great decisions, you need to speak the language of your three core financial statements. The income statement tells you if you’re profitable. The balance sheet tells you what you own and owe. The cash flow statement tells you if you can pay your bills—and yes, those are three very different questions.

Too many owners look only at the profit line and call it a day. That’s how profitable businesses run out of cash. The U.S. Securities and Exchange Commission offers an excellent primer on how to interpret financial reports for decisions, and I recommend every founder read it—not because you need to become an accountant, but because you can’t delegate understanding.

Reading between the lines

Look at trends, not snapshots. One month of declining revenue is noise. Three months is a signal. Comparing this quarter to the same quarter last year removes seasonality and shows you the truth.

Profitability Analysis: Know Which Dollars Actually Work for You

Revenue is vanity; profit is sanity. Profitability analysis reports break down your margins by product, service line, or client so you can see which parts of your business earn their keep—and which quietly drain resources.

I’ve watched business owners discover their “best” client was actually their least profitable one once time and overhead were factored in. That single insight changed their entire pricing strategy. Consider that according to U.S. Bureau of Labor Statistics data, roughly 20% of small businesses fail within their first year—and cash and margin blindness are leading culprits. Using profitability analysis reports to track net profit margin regularly keeps you out of that statistic.

The takeaway? Don’t just ask “Did we make money?” Ask “Where, exactly, did we make it—and where did we lose it?”

Cash Flow Reports: The Lifeblood Metric You Can’t Ignore

Profit is an opinion; cash is a fact. A business can post strong profits and still collapse because cash arrives too slowly to cover payroll. That’s why cash flow analysis reports deserve a permanent seat at your decision-making table.

Liquidity ratios—like your current ratio and quick ratio—tell you whether you can handle short-term obligations without scrambling. Small and midsize businesses face unique challenges here, which is why we built resources like our guide on cash flow analysis reports specifically for SME leaders. A U.S. Bank study famously found that 82% of business failures trace back to poor cash flow management. Let that number guide your priorities.

What to check weekly

Review your cash position, upcoming payables, and outstanding receivables every single week. Fifteen minutes. That’s the whole habit—and it will save you from 90% of cash surprises.

Turn financial reports into smarter decisions. Complete Controller gives you clear, accurate financials so you can act with confidence.

Budgeting and Forecasting: Planning Beats Reacting Every Time

A budget isn’t a cage—it’s a compass. Budgeting and forecasting reports turn your goals into numbers and your numbers into decisions. Should you hire in Q2? Expand into a new market? Your forecast answers those questions before you commit a single dollar.

The Small Business Administration provides solid, free guidance on budgeting and forecasting reports for strategic decisions, and it pairs beautifully with a rolling forecast approach. Here’s my recommended rhythm:

  1. Build an annual budget tied to your strategic goals.
  2. Update forecasts monthly as real numbers come in.
  3. Run variance analysis comparing budget to actual.
  4. Adjust decisions—not just numbers—based on what you learn.

Variance analysis is where the magic happens. When actuals drift from plan, the why behind the gap is your most valuable business intelligence.

Risk Assessment and Internal Controls: Protect What You’ve Built

Great decisions require knowing what could go wrong, not just what could go right. Risk assessment financial reports identify exposure—concentration risk, fraud risk, compliance gaps—before it costs you. The Committee of Sponsoring Organizations (COSO) sets the gold standard here, and their framework on risk assessment financial reports is widely used by leadership teams to build risk-aware reporting.

Strong internal controls aren’t corporate bureaucracy—they’re how you sleep at night. Segregated duties, reconciled accounts, and documented approvals turn your reports from “probably right” into “trustworthy.”

Clean Books, Clear Decisions: Why Accuracy Comes First

Every report we’ve discussed rests on one foundation: accurate, current bookkeeping. Garbage in, garbage out—there’s no dashboard sophisticated enough to fix bad data. That’s the truth I built Complete Controller on when we pioneered cloud-based bookkeeping and controller services.

Reliable management accounting reports start with disciplined daily processes: timely transaction entry, monthly reconciliations, and consistent categorization. When your books are clean, your reports become decision tools instead of decoration. When they’re not, every “insight” is a guess wearing a suit.

Conclusion: Your Numbers Are Talking—Start Listening

Decision-making financial reports aren’t paperwork; they’re power. The core statements show where you stand, profitability and cash flow reports show what’s working, budgets and forecasts show what’s next, and risk reporting protects the whole operation. Leaders who master these tools stop reacting and start steering.

You don’t have to do it alone. My team at Complete Controller has spent over two decades giving business owners the clean books, expert controller support, and clear reporting they need to make bold, confident decisions. Your best financial decision might be the one that gets you the right partner. Come see what clarity feels like. Download A Free Financial Toolkit

Frequently Asked Questions About Decision-Making Financial Reports

What are the most important financial reports for decision making?

The income statement, balance sheet, and cash flow statement are essential, supported by budgets, forecasts, and KPI dashboards for forward-looking decisions.

How often should I review financial reports?

Review cash flow weekly, full financial statements and variance reports monthly, and forecasts quarterly—or whenever a major decision is on the table.

What’s the difference between financial reporting and management accounting reports?

Financial reporting follows standardized formats for external parties, while management accounting reports are customized internal tools designed to guide leadership decisions.

How do KPI dashboards improve decision making?

Dashboards condense complex data into a few key metrics—margin, cash runway, revenue trends—so leaders can spot issues and act fast without digging through spreadsheets.

Can small businesses benefit from risk assessment financial reports?

Absolutely. Even simple variance monitoring and basic internal controls help small businesses catch fraud, cash shortfalls, and budget drift before they become crises.

Sources

Complete Controller. America’s Bookkeeping Experts About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
author avatar
Jennifer Brazer Founder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Reviewed By: reviewer avatar Brittany McMillen
reviewer avatar Brittany McMillen
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.