


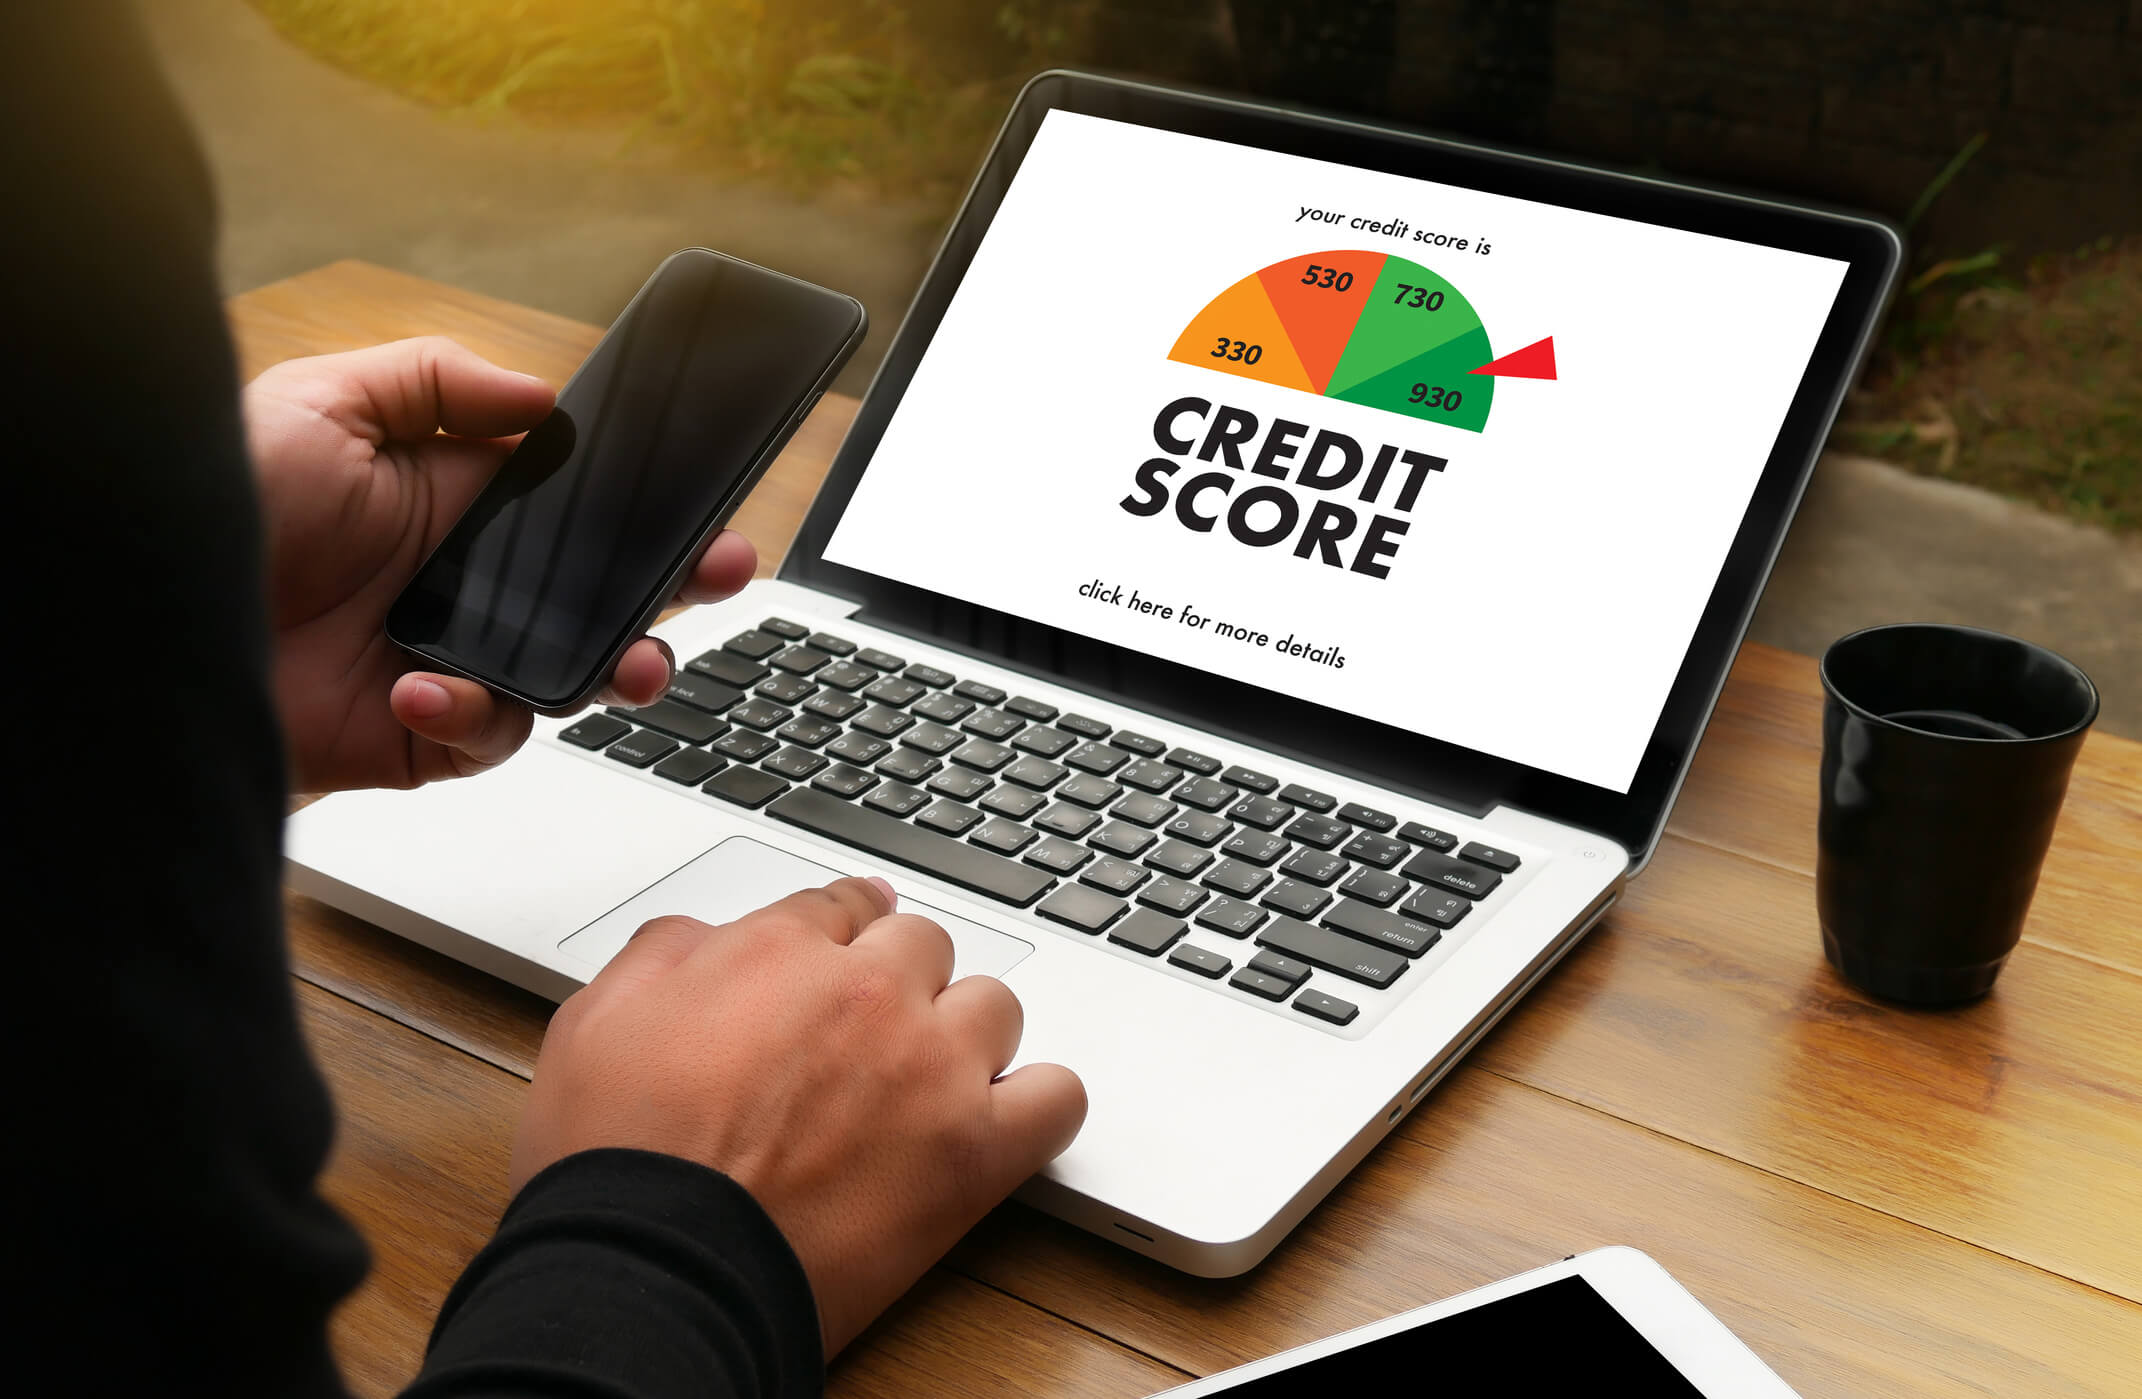
Monitor Your Credit For Free — Keep Tabs Safely
Monitor your credit for free by pairing weekly report pulls from AnnualCreditReport.com with no-cost bureau alerts and a reliable free score tracker, so you can catch errors, fraud, and surprise changes before they cost you money or borrowing power. The official, federally authorized source is AnnualCreditReport.com, where you can request free reports from Equifax, Experian, and TransUnion weekly, and then layer in free monitoring alerts from Experian or TransUnion for ongoing oversight without paying a subscription.
Here’s the honest truth I’ve learned in more than 20 years leading Complete Controller and working shoulder-to-shoulder with business owners across nearly every industry you can name: most people don’t check their credit until they need something from it—and by then, a small error or unnoticed fraud alert has already turned into a funding headache. In this article, I’ll show you exactly how to build a simple free-monitoring routine, which tools are worth your time, how the three bureaus differ, and how to respond fast if something suspicious shows up. You’ll walk away with a repeatable system that protects your personal credit and your business’s financing options—without spending a dime.
How do you monitor your credit for free and keep tabs safely?
- The short answer: Use AnnualCreditReport.com for weekly free reports, turn on free bureau alerts, and track your score with a reputable no-cost tool.
- Free reports: Federal law guarantees free weekly access to reports from all three bureaus through AnnualCreditReport.com.
- Free alerts: Experian, TransUnion, and several free apps notify you of new accounts, inquiries, and balance changes.
- Score tracking: Free score tools show direction over time but should always be paired with report review.
- Safety layer: Fraud alerts and credit freezes are free by federal law and give you fast protection if something looks off.
What Free Credit Monitoring Actually Covers
Free credit monitoring means you’re using no-cost tools to review your credit reports and receive alerts about meaningful changes to your file. It’s not one single product—it’s a combination of official report access, bureau-provided monitoring, and score tracking that, when used together, gives you a reliable picture of your credit health.
The trick is knowing what each piece does. Reports show the raw data lenders see. Scores summarize risk. Alerts flag movement. If you rely on only one, you’ll miss things.
Credit report access vs. Credit score tracking
A free credit report shows the underlying accounts, inquiries, and personal information on your file. A free credit score summarizes that data into a number lenders use to price your loan. Both matter, but they answer different questions—reports tell you what happened, and scores tell you how it looks.
Best free credit monitoring tools to consider
The best free tools share a few traits: no credit card required, clear alert definitions, easy dashboard access, and transparent privacy terms. Look for these features when choosing:
- No-cost score refreshes at least monthly
- Alerts for new accounts, hard inquiries, and address changes
- Clear identification of which bureau is being monitored
- No pressure to upgrade before you can see basic alerts
How to Monitor Your Credit for Free Without Missing Changes
Start with the official source and build outward. AnnualCreditReport.com is the only federally authorized site for free reports from all three bureaus, and the CFPB confirms consumers can now access these reports weekly through this portal. From there, layer in bureau alerts and a free score tool so you’re never more than a few days away from spotting something unusual.
Here’s the simple 4-step routine I recommend to every business owner I work with:
- Pull one bureau’s report every month on a rotating schedule (Equifax in January, Experian in February, TransUnion in March, repeat).
- Turn on free alerts from at least one bureau so new inquiries and accounts hit your inbox immediately.
- Track your score monthly through a free tool to watch for unexplained drops.
- Respond within 48 hours to any alert you don’t recognize.
Credit bureau alerts worth turning on
Not all alerts carry the same weight. Focus your attention on the high-signal ones: new account openings, hard inquiries, balance jumps of 30% or more, address changes, and any new collection or public record. These are the changes most likely to indicate fraud or a reporting error that could tank a loan application.
Good credit opens doors. Good financials help you walk through them. See how Complete Controller helps small businesses stay financially ready.
How Equifax, Experian, and TransUnion Compare for Free Monitoring
Each of the three major bureaus offers something different, and knowing the differences helps you build smarter coverage without duplicating effort.
- Equifax: Free reports through myEquifax and AnnualCreditReport.com, plus additional free reports if you’ve been denied credit or suspect fraud.
- Experian: Free monitoring alerts covering the Experian file, with optional paid upgrades for broader coverage and identity theft insurance.
- TransUnion: Free score, report, monitoring, and alert access, along with direct links to AnnualCreditReport.com for weekly report pulls.
Why multi-bureau coverage matters
Lenders don’t all report to the same bureau, so a fraudulent account could show up on one file and not the others. Rotating your monthly review across all three—and using free alerts from at least one—closes that gap without pushing you toward a paid service.
Identity Theft Protection and Real-World Monitoring Examples
Identity theft protection is only as strong as your response time. The faster you see a suspicious change, the faster you can freeze your credit, dispute the account, and stop the damage. This is where free monitoring earns its keep.
According to the Federal Trade Commission’s Consumer Sentinel Network Data Book 2023, the FTC received 1.1 million reports of identity theft in 2023, with credit card fraud ranking among the most common types. That number alone should tell you monitoring isn’t optional—it’s basic hygiene.
And when fraud does happen, your protections are free. The FTC confirms that placing and lifting a credit freeze at Equifax, Experian, and TransUnion is free by federal law—no fees, no strings.
Case study: Free monitoring after a major breach
The 2017 Equifax breach exposed data on roughly 147 million consumers, and as part of the settlement, affected individuals could claim free credit monitoring or cash compensation. That event permanently reshaped how people think about credit oversight—and it’s a reminder that even when a company hands you free monitoring after the fact, the real protection comes from making monitoring a habit before something goes wrong.
Takeaway: Free monitoring works best when it’s already running before a breach happens, so alerts land immediately and you can freeze credit fast.
Building a Monitoring Routine That Fits a Business Owner’s Life
For founders and small business owners, credit monitoring isn’t just personal—it’s operational. Your personal credit often backs business financing, vendor terms, and lease approvals, which means an unnoticed error can ripple through your company. A steady routine, paired with clean bookkeeping and accounting services, keeps both sides of your financial life ready for opportunity.
Mortgage and loan credit check prep
Before you apply for any financing, pull all three reports and review them line by line. Dispute anything inaccurate through the CFPB’s dispute process at least 60 days before you apply. Lenders price risk on what they see, and a single stale collection can cost you thousands in interest or push a denial your way.
Credit monitoring without payment: The long game
You do not need a paid subscription to stay protected. What you need is consistency—monthly report review, active alerts, and a fast response plan. That’s the whole game.
Final Thoughts
Monitor your credit for free by combining weekly report access, no-cost bureau alerts, and a free score tracker into a simple monthly routine you’ll actually stick with. Add fraud alerts and credit freezes to your toolkit, respond fast when something looks off, and remember that your personal credit is a business asset worth protecting. If you’d like more expert guidance on building a rock-solid financial foundation—covering everything from credit hygiene to full-service bookkeeping—the team at Complete Controller is ready to help you take the next step.
Frequently Asked Questions About Monitor Your Credit For Free
How can I monitor my credit for free?
Use AnnualCreditReport.com for free weekly reports from all three bureaus, then layer in free alerts from Experian or TransUnion and a free score tracker for ongoing oversight.
Is free credit monitoring actually safe to use?
Yes, when you use trusted providers like the three major bureaus and the official AnnualCreditReport.com portal, and pair them with strong passwords and two-factor authentication.
Does a free credit report include my credit score?
Usually not—free reports show account and inquiry data, while scores typically come from separate free tools offered by bureaus, banks, or credit card issuers.
How often should I check my credit reports?
The CFPB now allows free weekly report pulls through AnnualCreditReport.com; a practical routine is to rotate one bureau per month and review alerts as they arrive.
What should I do if I spot fraud on my credit report?
Place a free fraud alert or credit freeze at all three bureaus, dispute the fraudulent account directly with the bureau, and file a report at IdentityTheft.gov.
Sources
- AnnualCreditReport.com. (2026). Annual Credit Report. https://www.annualcreditreport.com
- California Attorney General. (2026). Consumer Notice on Credit Monitoring and Free Reports After a Breach. https://oag.ca.gov
- Consumer Financial Protection Bureau. (2025). How Do I Get a Free Copy of My Credit Reports? https://www.consumerfinance.gov/ask-cfpb/how-do-i-get-a-free-copy-of-my-credit-reports-en-5/
- Consumer Financial Protection Bureau. Credit Reports and Scores. https://www.consumerfinance.gov/consumer-tools/credit-reports-and-scores/
- Equifax. (2026). Get a Free Credit Report. https://www.equifax.com/personal/credit-report-services/free-credit-reports/
- Experian. (2026). Free Credit Monitoring. https://www.experian.com/consumer-products/free-credit-monitoring.html
- Federal Trade Commission. (2023). Free Credit Reports. https://www.consumer.ftc.gov/articles/free-credit-reports
- Federal Trade Commission. (2019, July 22). Equifax Data Breach Settlement. https://www.ftc.gov/enforcement/refunds/equifax-data-breach-settlement
- Federal Trade Commission. (2024, February). Consumer Sentinel Network Data Book 2023. https://www.ftc.gov/reports/consumer-sentinel-network-data-book-2023
- Federal Trade Commission. (2024, March 11). Credit Freeze FAQs. https://consumer.ftc.gov/articles/what-know-about-credit-freezes-and-fraud-alerts
- IdentityTheft.gov. Identity Theft Protection. https://www.identitytheft.gov/
- TransUnion. (2025). Free Credit Score, Report, Monitoring & Alerts. https://www.transunion.com/free-credit-score
 About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.



 Brittany McMillen