Moving for most people is like a nightmare that never stops haunting their dreams. Uprooting your life and packing everything up into different boxes is traumatizing. Changing your residence to an entirely new location can be stressful, and that can easily overwhelm you. To ensure your move is as smooth as possible, avoid these common problems during an activity.
Unnecessary Items
Retaining unnecessary items is a common mistake when beginning life in a new home. It’s impractical to pack belongings that have been collecting dust on shelves for years, especially when you know you won’t use them. To streamline your move, consider parting with items unused for over a year. Donate them to charity or include them in a yard sale—avoid investing time and money in things destined to remain unused.
Lack of Planning
The lack of planning is akin to setting oneself up for failure; as the saying goes, “If you fail to plan, you plan to fail.” This phrase aptly captures the essence of moving without careful consideration. Would you embark on a skydiving adventure without a parachute, adopting a “Let’s see how it goes” approach? Moving shares similarities, albeit a bit scarier. Without thorough planning up to the last detail, things can quickly spiral out of control.
Here are the things you need to prepare
Plan your finances (enough money in the bank for payments)
Getting all the paperwork in order
Make a timetable or calendar of the involved tasks
Discussing your moving details with the moving company (how you want things done)
Before engaging a professional moving company, it’s essential to consider a few key factors. Movers won’t automatically identify sensitive or fragile items within your boxes and won’t be aware of your budget unless you communicate your needs. Establishing a two-way relationship with clear communication is crucial. Here are some effective strategies to optimize your moving experience and save money.
Hiring Professional Movers
Contrary to common perception, hiring professional movers is often more cost-effective than attempting a DIY move. When you enlist a moving company’s services, you ensure precision in handling every box and item according to your preferences. In a DIY scenario, the responsibility for any breakages rests solely on you, and you bear the expenses of replacing the damaged items. Opting for professional movers provides a service guarantee and minimizes the financial burden associated with potential damages.
Proper Labeling
It is crucial to label and categorize each box during packing meticulously. Proper labeling serves several purposes, including facilitating quick retrieval of items and ensuring that everything has been successfully moved to the new location. Additionally, clear labeling aids both you and your movers in identifying the designated area for each box in your new home. This simple yet effective practice enhances organization and streamlines the unpacking process.
Planning Ahead
Prioritize planning by ensuring you have all the necessary supplies well before the moving day. Avoid a last-minute rush for packing boxes when your belongings are already outside. If you’re opting for moving services, it’s advisable to make your booking in advance, especially before the peak season hits. Additionally, consider early bookings for other essential services such as painters, rental supplies, and cleaners to secure a smooth and well-coordinated moving experience.
Looking for any Leakages and Cracks
Upon moving into a new house, conducting a thorough check for any leakages and cracks is essential. Ensuring everything is in proper working order is crucial to avoid surprises. You wouldn’t want your first bathing experience in your new home to become a disaster due to overlooked issues. Taking the time to inspect for potential problems early on can save you from inconvenient and costly repairs later.
Bottom Line
In conclusion, we understand that moving is a challenging endeavor. To assist you in navigating this process more smoothly, here are crucial money-saving tips that can contribute to a comfortable and hassle-free experience in your new place. By following these recommendations, your next move, whether to a new home or office, can be executed quickly, comfortably, and, most importantly, cost-effectively.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
When we go to a store or search for a service, we usually ask what the value of what we are about to buy is. But do you know that there is a difference between price and value? And as much as we do not always make that distinction when we go shopping, we’d better think about whether we are getting something for value or value when it comes to investments.
Are you confused? What do you think of going deeper into this idea to understand it better? Follow the post we prepared and ask your questions!
How Much Does it Cost to Produce and Distribute Products and Services?
When a company produces a commodity or a service, it calculates the resources needed to deliver the solution to its customers. This calculation includes fixed costs (water, electricity, telephone, internet, rent) and variable costs (inputs, payroll, and distribution). Once you calculate the cost of production, then you will add the taxes due and the profit margin together. At the end of the process, we have the price of the product or service!
What Relevance Does the Consumer Usually Give to Products and Services?
Whoever values an investment is the buyer. So, what is a priority for you may be relevant for another person. For example, it is a case of taking a trip or buying a car. Both options populate the dreams of various consumers. While some want to cruise, others want to buy a new vehicle to make their family more comfortable. And neither of the two profiles is wrong! They are only different points of view, adapted to the reality of each one.
In the End, is it Better to Prioritize Price or Value?
We tend to prioritize lower prices when discussing everyday items such as pens. We can satisfy our needs in the same way as its more expensive counterpart. However, when making investments, you must consider other factors. Here comes the value of a good, which can have an influence overall.
You want to buy a new car because your family is growing. This may seem like an unnecessary luxury. However, this acquisition has excellent value for you, so much so that the price to pay does not equal the benefits you will get once you have your new car in the garage.
For those who dream of traveling the world, the money spent on travel, lodging, food, and other necessities does not compare with the experience of meeting new cultures, experiencing exotic foods, and people of different profiles.
However, you do not have to pay more than the fair price for what you are getting, do you? And this is worth it even if experiences, comfort, and safety have the most incredible value in the world for you! It is the case of buying a property, for example. You have the good at your disposal in less time by opting for financing, but for a higher price than it is worth it. Already choosing a real estate consortium, you can plan yourself more peacefully, paying less, but not for that, letting you see your dream come true!
The same logic holds for other investments. Do you need to travel today, or can you wait? Is the new car urgent, or does it still have time until the children arrive? Think about it: what you save with planning can be used in other investments!
And why are we talking about it? Simple: only end up spending what is necessary. You need to find the balance between price and value, investing wisely!
Conclusion
Distinguishing price from value is crucial for your brand’s success. Value, a magnet for lasting customer loyalty, is exemplified by American brands like Mac and Coke, which are desired by over 90% monthly. Satisfy customers with top-notch quality, and they’ll willingly pay higher prices, ensuring sustained brand reputation and customer satisfaction.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Value investing involves strategically purchasing assets or investments at prices below their intrinsic value. Instead of relying on complex definitions or abstract financial theories, value investing boils down to a straightforward principle: buying something for less than its true worth.
To illustrate this concept, consider the scenario of a store, such as a clothing outlet, undergoing liquidation. During this process, merchandise is often sold at significantly reduced prices. Value investors recognize the opportunity in such situations, as they can acquire items at a favorable cost compared to their regular market value. This principle extends beyond retail scenarios to encompass investments in companies.
Similar to a store in liquidation, there are instances when a company is facing financial distress or undergoing a phase that can be likened to “liquidation” mode. This might be due to factors such as economic downturns, poor management decisions, or industry challenges. In these situations, value investing is a strategic approach to evaluate and capitalize on undervalued opportunities.
Value investors analyze companies experiencing temporary difficulties or market mispricing, allowing them to identify potential bargains that other investors may overlook. By delving into a company’s fundamentals and examining its assets, earnings, and growth potential, value investors aim to uncover discrepancies between the market price and the investment’s intrinsic value.
Value investors gain a distinct advantage through this careful study and understanding of a company’s true worth. While the broader market may be influenced by short-term fluctuations or sentiment, value investing remains rooted in the long-term perspective of identifying and acquiring assets at prices below their intrinsic value, ultimately seeking to benefit from their potential appreciation over time.
Is Value Investing a Fad?
Here is a humble opinion on value investing, and I will also point out what is and what is not. For those who do not know this investment flow, I will start from the beginning:
Value investing was developed as such by Benjamin Graham in the 1928 environment. Its investment philosophy is to buy assets for less than they are worth (intrinsic value) to generate a profit in the subsequent sale.
As you can see, nothing from the other world, buy cheap and sell at its price or more expensive. Sure, before Graham thought about it and carried it out, but Graham was the one who created the school.
Then came other mythical investors such as Warren Buffet, Peter Lynch, Carl Icahn, Seth Klarman, and Jeremy Grantham. It is fashionable because, in an increasingly efficient market, the way to excel is by finding inefficiencies such as those exploited by value investing.
Today, managers are doing things very well by following this philosophy. Therefore, the term and its followers have become popular, but we will study it to avoid mistakes.
Are There Different Types of Value?
Value investing is evolving. People like to make distinctions, although we discuss the same thing.
These subtypes are:
GARP (growth at a reasonable price). We could not consider these companies cheaply concerning the market average, but this is because their development is much higher than the average of companies. For this reason, they do not list multiples such as PER and EV / EBIT, which are as low as those of other value companies.
Deep value investing. It is value investing using elements of the “old school” balance. It is about finding companies looking at the balance. They usually hide jewels that are typically true treasures. For example, the NCAV, Graham & Dodd liquidation value, P / Net cash, and modifications of both.
What is Not Value Investing?
Value investing is NOT buying “apparently” good companies and keeping them forever. As much as they are called Coca-Cola, Santander, or Iberdrola, they are large and good companies because they have worked for years. Buying and maintaining them is not value investing. It will be a buy-and-hold or buy-and-hold strategy, but not value investing. See this continuously.
Investors who invest in Telephone or BBVA for dividends deceive themselves by telling themselves and others that they have made a “Valiu” investment when, in the best case, they will long-term aspire to approach inflation.
How Do You Learn About Value Investing?
There are valuation methods. Suppose you want to learn to detect sound and priced companies to enter the world of value investing. In that case, I leave you the link to the most recommended article in my blog on performing a “Fundamental Analysis for Rookies.” A common mistake is to use the same valuation method for all companies.
Each company is different and is in a different cycle (growing, already mature, expanding). Therefore, the considerations we need to know about each company are additional, and we will weigh variables more than others.
The differences are the most complicated part. Although there is a more rational and logical part, I explain myself. Once we understand the analytical role better or worse, we must see if our assumption is crazy.
Conclusion
As we explore value investing, this article aims to demystify its principles, dispel common misconceptions, and equip readers with the tools to discern true value. In a world where financial landscapes evolve, value investing remains a stalwart philosophy that transcends market trends, offering astute investors a timeless advantage.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Mastering Insurance Contracts: A Guide to Decoding Them
Decoding insurance contracts means breaking down the dense legal language to understand what protection you truly have, which clauses matter most, and precisely what you’re agreeing to when you sign—so you can avoid costly misunderstandings and confirm your coverage fits your real needs.
Over the past 20 years as CEO of Complete Controller, I’ve worked with thousands of business owners across every industry imaginable, and I’ve seen firsthand how a single misunderstood insurance clause can devastate a company’s finances. Consider this: insurance policies are written at a college or graduate school reading level (grades 13-24), while the average American reads at an 8th-grade level—and only 27% of people actually read their complete policy documents. This guide will equip you with practical tools to analyze coverage sections, spot hidden exclusions, compare competing policies, and negotiate better terms, transforming you from a passive policyholder into an informed decision-maker who protects their business and personal assets with confidence.
What soes “Decoding Insurance Contracts” mean, and how do you really do it?
To decode an insurance contract, read beyond the surface to understand coverage, exclusions, conditions, definitions, endorsements, and your obligations as a policyholder
The declaration page summarizes the essentials: who and what is covered, your limits, and policy period
The insuring agreement spells out what the insurer promises to pay for and when
Exclusions and conditions reveal what isn’t covered and what rules must be followed
Reviewing endorsements, policy definitions, and legal implications helps you grasp every commitment—and every gap
The Anatomy of an Insurance Contract: Your Step-by-Step Policy Breakdown
Understanding your insurance contract’s structure gives you the roadmap for systematic policy analysis and interpretation, preventing expensive surprises and creating transparency in your coverage.
Your insurance contract contains five essential sections that work together to define your coverage. The declaration page provides your quick-reference snapshot—listing names, policy period, coverage types, limits, and premium amounts. The insuring agreement forms the heart of your contract, detailing what the insurer promises to pay, which perils are covered, and how claims get processed. Exclusions spell out what your policy won’t cover—often the source of denied claims that catch policyholders off guard. Conditions establish the rules you must follow to keep coverage valid and claims payable, including notification timeframes and documentation requirements. Finally, endorsements or riders modify your standard coverage, and these often contain critical changes that expand or limit your protection.
Insurance policy analysis: Comparing key sections across different policies
Strategic insurance document breakdown involves lining up multiple policies for side-by-side analysis to spot subtle exclusions and create true apples-to-apples coverage comparisons. Start by creating a comparison chart with columns for each policy option and rows for declaration details, coverage types, exclusions, conditions, and endorsements. Pay special attention to differences in definitions—one policy’s “flood” might include sewer backup while another’s doesn’t. Note variations in notification requirements, as missing a 72-hour reporting deadline could void your coverage entirely.
Decoding Insurance Terms and Clauses: The Language That Matters Most
Insurance contracts deliberately use precise legal terminology that creates binding obligations, and understanding these terms empowers you to recognize your rights and responsibilities.
The insurance industry operates with its own vocabulary, and mastering key terms transforms confusing documents into clear agreements. Common insurance contract legal terms include “perils” (the specific risks covered), “occurrence” versus “claims-made” (when coverage triggers), “aggregate limit” (maximum payout for all claims combined), “deductible” (your out-of-pocket before coverage kicks in), “named insured” (who’s specifically covered), “additional insured” (others added to your policy), and “waiver of subrogation” (preventing your insurer from suing third parties).
Insurance terms and conditions: Plain-english definitions
Critical clauses can dramatically shift your coverage without obvious warnings. “Other insurance” clauses determine which policy pays first when you have multiple coverers. “Choice of law” provisions dictate which state’s regulations apply to disputes. “Indemnification” clauses spell out who pays for legal defense costs. Insurance coverage explanations reveal how tiny word choices create major differences—”shall” creates mandatory obligations while “may” grants discretion to the insurer.
Real-World Example: How Decoding Your Policy Can Mean the Difference Between Getting Paid and Denied
A small manufacturing business in Ohio faced potential bankruptcy when their warehouse fire claim was initially denied in 2023. The insurer cited failure to comply with a “condition precedent” requiring loss notification within 72 hours. However, the owner and their Complete Controller bookkeeper had meticulously reviewed the contract together, creating calendar alerts for every compliance requirement. Their documentation proved they’d notified the insurer within 48 hours, including timestamped emails and certified mail receipts. The insurer reversed their denial on appeal, paying the full $1.2 million claim. This case demonstrates why understanding every contract provision matters—hospitals alone spend $19.7 billion annually fighting insurance claim denials, with 54.3% ultimately overturned after expensive appeals processes.
Smart business owners learn from others’ mistakes. Common oversights include assuming generic policy templates fit your specific business, missing exclusions buried in endorsement pages, and neglecting to verify coverage matches current operations. Insurance contract interpretation requires reading between the lines—if your business model changed since your last renewal, your coverage might have gaps you haven’t noticed.
Insurance contract interpretation: Reading beyond the obvious
Professional insurance policy transparency starts with demanding plain-English explanations from your broker for any unclear provisions. Document these clarifications in writing, as verbal assurances won’t help during claim disputes. Create a coverage summary sheet listing what is covered, what isn’t, and what conditions apply. Review this summary with your team quarterly, especially after any business changes.
The Bottom Line: Actionable Steps for How to Decode Insurance Contracts Before You Sign
Master these five steps to decode insurance contracts like a seasoned professional, protecting your assets and avoiding claim denials.
How to decode insurance contracts: A proven checklist
Request the complete policy document in writing, not just quotes or summary pages that omit critical details. Highlight and tab five key sections: declarations, insuring agreement, exclusions, endorsements, and definitions. Create a specific questions list including “What scenarios aren’t covered?”, “What must happen for claims to be paid?”, and “What triggers cancellation or denial?” When comparing policies, build a spreadsheet tracking differences in coverage, exclusions, limits, and conditions. Finally, involve your attorney or trusted advisor for complex policies, documenting every clarification they provide—this paper trail proves invaluable during disputes.
Building Trust: Why Transparency in Insurance Policies Matters
Despite regulatory progress requiring clearer policy language in 47 states, consumer confusion remains widespread—51% of insured adults report difficulty understanding their coverage, including what’s covered (36%) and out-of-pocket costs (30%).
Insurance policy transparency: Your rights as a policyholder
You have the right to demand clarity from brokers and insurers, including plain-language summaries of complex provisions. Recent regulatory protections mandate better accessibility and clearer disclosures, though enforcement varies by state. Shockingly, 60% of insured adults don’t know they have legal appeal rights when claims are denied, and 76% don’t know which government agency handles insurance complaints. Your state insurance department serves as your advocate—file complaints when insurers provide evasive answers or deny legitimate claims. Most states also have insurance ombudsmen who mediate disputes between policyholders and companies.
Final Thoughts: Why I Never Sign Without Reading the Fine Print
As a founder who’s navigated countless insurance renewals and claims, I treat every insurance agreement with the same scrutiny I give financial statements. My process involves three careful reads: first for understanding coverage scope, second for identifying exclusions, and third for imagining worst-case scenarios to test whether they’re covered. This discipline saved Complete Controller multiple times—once catching an exclusion that would have left us exposed during a data breach, another time discovering our business interruption coverage had silently expired through an endorsement change.
The statistics prove why this matters: between 39% and 59% of insurance claim denials get overturned on appeal, yet only 1% of denied claims are ever challenged. Don’t become another statistic. Take control of your insurance contracts today, and if you need expert guidance navigating complex coverage decisions, visit Complete Controller where our team helps businesses decode financial and insurance complexities daily.
Frequently Asked Questions About Decoding Insurance Contracts
What is the main purpose of an insurance contract?
To legally define the obligations, coverage, and limitations between the insurer and insured, creating binding agreements about who pays for what losses under which circumstances.
Which section of an insurance policy lists what is NOT covered?
The Exclusions section details all events and circumstances excluded from coverage, often spanning multiple pages with specific scenarios your policy won’t pay for.
What is an endorsement in insurance policy terms?
An endorsement modifies the original contract terms—either adding, removing, or changing coverage—and these modifications override standard policy language.
Why do insurance policies contain complex terminology?
Insurance contracts are legal documents requiring precise language to define coverage, responsibility, and limits—though this precision often creates confusing jargon that advantages insurers over policyholders.
What should I do if I don’t understand part of my contract?
Ask your broker or agent for a plain-language explanation in writing, and if still unclear, consult an insurance attorney or contact your state insurance regulator for guidance.
Sources
Anderson Kill. (2024). “Understanding ‘Other Insurance’ Clauses in Insurance Policies.” www.andersonkill.com
Carlson Bier. (2024). “Decoding Insurance Policies: A Layman’s Guide.” www.carlsonbier.com
Foundershield. (2023). “The Ultimate Guide to Insurance Requirements in Contracts.” www.foundershield.com
Gilman & Bedigian. (2024). “Half Of Insurance Claim Denials Are Overturned On Appeal.” www.gilmanbedigian.com
Insurance Information Institute. (2024). “What is Insurance?” www.iii.org
Insurance Professionals of Arizona. (2024). “How to Read an Insurance Policy.” www.insuranceproaz.com
International Medical Group. (2023). “How to Read an Insurance Policy.” www.imglobal.com
Kaiser Family Foundation. (2024). “KFF Survey of Consumer Experiences with Health Insurance.” www.kff.org
Lexagle. (2024). “Insurance and Indemnification in Contracts.” www.lexagle.com
Lockton. (2023). “Key Terms and Clauses in Insurance Contracts.” www.lockton.com
OLHI. (2024). “Decoding Life and Health Insurance Policies: A Simple Guide.” www.olhi.ca
Readable.com. (2023). “Have you read the terms and conditions? The Readability of Insurance Policies.” www.readable.com
Restorical. (2024). “Understanding Choice of Law in Insurance Claims.” www.restorical.com
South Carolina Department of Insurance. (2023). “Understanding Your Insurance Policy.” www.doi.sc.gov
The American Hospital Association. (2024). “Payer Denial Tactics — How to Confront a $20 Billion Problem.” www.aha.org
USALearning.gov. (2024). “How to Read — and Understand! — Your Insurance Contracts.” www.usalearning.gov
Zuva. (2024). “What is an Insurance Clause?” www.zuva.ai
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Jennifer BrazerFounder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.
Master Property Purchases: Expert Strategies and Tips
Mastering property purchases comes down to having a clear strategy, a repeatable checklist, and the discipline to apply proven negotiation, financing, and due-diligence tactics so you buy smarter, avoid costly surprises, and secure the right deal every single time. It isn’t luck or finding a magic “steal”—it’s following disciplined property acquisition strategies, understanding your numbers cold, and protecting yourself legally and financially from the first offer to closing day.
In my 20+ years leading Complete Controller, I’ve had the privilege of reviewing financials for thousands of real estate investors, first-time homebuyers, and seasoned portfolio owners across nearly every market in the country. The pattern I see is unmistakable: disciplined, checklist-driven buyers build long-term wealth and protect cash flow, while emotional impulse buyers often end up with surprise repairs, legal headaches, or properties that quietly drain their business and personal finances. In this article, I’ll walk you through the foundations of real estate investment education, the smartest acquisition strategies, financing essentials, a due-diligence system that actually works, negotiation tactics that close deals, and the closing process that protects your investment.
What is mastering property purchases and how do you do it right?
Mastering property purchases means combining education, strategy, financing, negotiation, and rigorous due diligence to consistently buy the right property at the right price with the right protections in place.
It starts with real estate investment education so you understand market cycles, cash flow, and risk before writing any offer.
You define your property acquisition strategy (primary home, buy-and-hold, turnkey, or value-add) and align your budget, criteria, and timeline accordingly.
You secure mortgage pre-approval for property purchases and compare financing options to know what you can truly afford.
You protect yourself with a mastering property purchases checklist covering inspections, due diligence for property acquisition, and understanding property titles and liens.
You apply smart negotiation tactics and run an effective closing process supported by vetted professionals.
The Foundations of Mastering Property Purchases
Before you tour a single property, your education and mindset determine your outcome. The buyers who win consistently are the ones who treat real estate like a business, not a hobby.
Why real estate investment education beats gut feeling
Real estate investment education is structured learning about markets, financing, tax, and risk—through books, mentors, government homebuyer guides, and professional advisors. Uninformed buyers routinely overpay or misjudge risk because they ignore local supply trends or interest-rate movements.
A small rate shift can crush a deal. Freddie Mac data shows the average 30-year fixed mortgage rate climbed from 3.11% in December 2021 to 7.79% in October 2023. That kind of jump can move a property from cash-flow positive to negative overnight if you haven’t stress-tested the payment.
Every buyer should understand:
Cash-on-cash return and basic cap rate
Debt-to-income ratio and loan-to-value
The difference between lifestyle metrics and investment yield
Setting a strategy before you shop
Clarify your “why” first. Are you buying a primary residence, rental income, long-term appreciation, or a short-term flip? Your business cash flow and personal income determine what’s truly affordable—often well below what a lender will approve.
Strategy First: Choosing the Right Property Acquisition Approach
The right strategy depends on your goals, risk tolerance, and how much time you can realistically dedicate.
Strategy
Best For
Risk Level
Involvement
Buy and hold property strategy
Long-term wealth & cash flow
Moderate
Ongoing
Turnkey property investments
Busy professionals, first-timers
Lower
Low, outsourced
Value-add / light rehab
Investors with some experience
Medium-High
Higher
Primary residence
Lifestyle + long-term equity
Moderate
Moderate
Buy and hold property strategy
A buy and hold property strategy focuses on stable neighborhoods, strong rent-to-price ratios, and tenant demand. You’re playing the long game—cash flow plus appreciation, with reserves and professional management protecting you through market cycles.
Turnkey property investments and how to purchase a property successfully
Turnkey property investments are fully renovated, tenant-occupied properties sold to investors. They offer speed and a lower learning curve, but always independently verify the provider’s numbers. To learn how to purchase a property successfully, choose one strategy and stick to it. Mixing “dream home” with “cash cow” is the fastest way to overpay.
Buying property is only half the equation. Managing the finances behind it is what drives long-term success. See how Complete Controller helps investors stay organized, profitable, and growth-focused.
The Money Side: Financing Options for Property Purchases
Money mechanics drive your returns. Knowing your financing options for property purchases before you shop gives you leverage and clarity.
Mortgage pre-approval for property purchases
Getting mortgage pre-approval for property purchases should happen before serious shopping. It strengthens your offers, reveals your real price ceiling, and speeds closing. Have your tax returns, bank statements, and business financials ready. The Consumer Financial Protection Bureau offers a strong starting point for comparing loan types.
Debt structure and risk management
Choose between fixed and variable debt based on your income stability and time horizon. Always maintain reserves covering several months of mortgage plus operating expenses—because rate shocks and vacancies happen.
Due Diligence and Risk Management: Where Deals Are Won or Lost
This is the section most buyers rush. Don’t. Property investment risk management is a system, not a guess.
Risk categories every buyer must assess
Property risk: condition, age, local hazards
Market risk: job growth, supply, population trends
Financial risk: vacancy, repairs, rate changes
Legal risk: title, zoning, unpermitted work
Due diligence for property acquisition: Step-by-step
Skipping inspections is reckless. According to the National Association of REALTORS® 2024 Profile of Home Buyers and Sellers, 91% of buyers had a home inspection done. Make it non-negotiable.
For rentals, also validate the rent roll, lease terms, utility responsibility, and maintenance history.
Understanding property titles and liens
A title search verifies ownership chain, liens, easements, and encumbrances. Get both owner’s and lender’s title insurance. A New York Times investigation found thousands of NYC buyers were billed for unpaid property taxes from before they owned their homes due to errors in the city’s tax-lien sale system. Confirm taxes, liens, and title details before you sign.
Initiate title search and review the preliminary report
Verify HOA rules, zoning, and rental regulations
Before removing contingencies:
Confirm repair costs and negotiate credits
Re-run numbers with new information
Get final written loan approval
Smart Negotiation Tactics for Property Mastery
Strong negotiation tactics start with preparation. Study comparable sales, days on market, and inventory to calibrate your offer. Know your walk-away point before you write anything.
Crafting offers beyond price
Contingencies, closing dates, rent-back arrangements, and inclusions all create flexibility when price is tight. Listen first to understand seller motivations, then tailor terms.
Working with a real estate agent for investment properties
A good real estate agent for investment properties thinks in returns, rents, and exit strategy—not curb appeal. Vet them by asking about their personal investing experience and investor client base. The right agent often surfaces off-market opportunities you’d never find alone. For trusted guidance, REALTOR® Magazine is a solid resource.
From Contract to Keys: Running an Effective Closing Process
An effective closing process for property purchases follows a predictable timeline: offer accepted → earnest money → inspections → appraisal → underwriting → title clearance → signing → funding.
Common pitfalls include missing documents, large credit purchases mid-underwriting, and unresolved repair disputes. A bookkeeping-savvy advisor can help forecast closing costs, reserves, and initial repair budgets so the larger financial plan stays intact.
Case study: Diligence turning risk into reward
A buyer I’m familiar with identified land at what looked like a below-market price. During a structured due-diligence period, surveys and environmental testing revealed wetlands restrictions and zoning limits that severely constrained buildable area. Armed with that data, the buyer renegotiated significantly better terms and added clear contingencies—turning a risky purchase into a smart one. The lesson: contingency periods are active investigation windows, not formalities.
Final Thoughts: Turning One Smart Purchase into a Repeatable System
In my experience, the people who truly succeed at mastering property purchases treat each deal as a disciplined process, not a one-time event. They invest in education, commit to a clear acquisition strategy, secure financing intelligently, follow a consistent checklist for risk management, and track every property like a business unit.
If you apply these frameworks—define your strategy, protect yourself with due diligence, and run your numbers with precision—you won’t just buy your next property more confidently. You’ll build a repeatable system for long-term wealth. When you’re ready to put professional financial structure behind your properties, visit Complete Controller and let my team support your journey.
Frequently Asked Questions About Mastering Property Purchases
What is the best strategy for buying my first investment property?
Start with a conservative buy and hold property strategy in a stable area with strong rental demand. Secure financing with room for reserves and be strict about positive cash flow after all expenses, including vacancy and maintenance.
How much cash should I have before purchasing an investment property?
Beyond down payment and closing costs, plan on several months of mortgage payments plus a repair and vacancy reserve. That cushion keeps a single surprise from forcing a fire sale.
Is it better to buy turnkey property investments or fix-and-flip as a beginner?
For most new investors, vetted turnkey property investments or light value-add deals are safer than full flips. Flips demand construction expertise, tight project management, and higher risk tolerance.
How do I avoid overpaying when the market is hot?
Get pre-approved, know your maximum walk-away price from your analysis, and rely on comparable sales and rent data over emotion. Be patient enough to wait for a property that fits your model.
Do I really need a real estate agent for investment properties?
An investor-savvy agent brings better deal flow, sharper pricing guidance, and stronger negotiation support—especially in unfamiliar markets or with complex property types.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Jennifer BrazerFounder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.
In economics, there are fundamental differences between depression and recession. For example, in the US, the last natural depression was the Great Depression of the 1930s. The US economy has experienced frequent episodes of recession, however.
Depression VS. Recession
Generally, a recession in the economy is much less severe than a depression. A recession decreases a country’s gross domestic product (GDP) for over a quarter of a year. The GDP decrease is smaller than a 10% decrease.
Also, the economic recession tends to be measured in quarters of a year rather than whole years. Depression is a decrease in GDP of 10% or more each year. The fourth drop rate was more than 10%, which you could not describe accurately as a depression unless the same conditions existed for one year.
If economic conditions improve in the fourth quarter of the year, and the decline in GDP becomes an increase, then the year is considered to have been the subject of a recession. However, GDP has declined steadily, and year totals show a reduction of 10% or more in GDP.
Recessions tend to occur more frequently than depressions because a country’s economy is fragile, and slight changes or shocks, such as the dot.com outbreak, produce a decrease in spending that reduces GDP by less than 10%. A diversified economy quickly recovers from this kind of shock because of other ways to spend money.
Thedot.com recession lasted for years. People mistakenly call this a depression. It did not reduce GDP by more than 10%, hence the economy in recession, and it was not depressing.
Economic Dynamics
People tend to produce a term that reflects more than its real meaning. A depressed economy is reminiscent of the type of depression people find when they must do less, spend less, or invest less. A recession seems more neutral or more favorable in comparison.
Sometimes, people deliberately use the terms to give a negative or positive turn to declining economic conditions. A politician who supports a particular monetary policy may refer to depression as a recession to lessen the responsibility of the wrong approach. A politician on the opposite side of economic policy could call a recession a depression to exaggerate how politics affects people.
However, depression and recession can use specific terms, and economists often visibly correct those who misuse words.
Getting a job during both a recession and a depression can be difficult.
In general, depressions cause difficulties for everyone, not just a particular part of the population.
Recessions tend to occur more frequently than excavations do.
Great Depression’s Situation in the United States of America
Depression stayed in the country for 43 months
The crust and trough rate of GDP decline was 26.5 percent
The reduced rate of industrial Production is around 46 percent
There was an 80% decrease in stock share.
A significant drop in the labor force increased unemployment; that percentage was 24.6%
Ways to Overcome Depression and Recession
Governments should take the initiative to arrange different programs to strengthen the clients’ pocketbooks to level up small businesses. It should include enhanced unemployment benefits. There are other ways to overcome the issue of recession or depression.
Throttle Your Expenses
Lockdown mode has made our financialcondition worse. On the one hand, people cannot earn, and on the other hand, there is a complete restriction on extracurricular activities. But there is the best opportunity for saving maximum money. This period also lets us know our rate of prodigality. Track your budget, whatever the situation is. Do not compromise in this regard.
Keep Your Emergency Funds Active
A financial emergency is an exposure that brings you into a state of desperation. In such cases, your only focus is to keep yourself stable financially. At that time, you need extreme demand for an emergency fund to cool down your financial catastrophe. The best way to keep it safe for these is to throttle the amount from your annual or monthly income.
Conclusion
In economics, the distinction between depression and recession holds crucial significance. While recessions are less severe, characterized by a GDP decrease lasting more than a quarter of a year but below 10%, depressions are marked by a 10% or more annual GDP decrease. The dot.com recession is an illustrative example, lasting for years but not meeting the criteria for depression. People’s tendency to use these terms interchangeably, often influenced by political motives, highlights the importance of precision in economicterminology.
Examining the Great Depression’s impact on the United States provides a historical context, emphasizing the challenges faced during that period. Overcoming economic downturns requires proactive governmentinitiatives, such as programs to bolster small businesses and enhanced unemployment benefits. Additionally, individuals can navigate challenging times by managing expenses, tracking budgets, and maintaining active emergency funds to weather financial crises.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
The insurance contract contains two different natures. One refers to the insurance of damages, and the other to the insurance of people, concepts that, although they can resemble in principle, in this article, we will see that they are opposite.
What is Damage Insurance?
Damage insurance will be responsible exclusively for repairing the damages suffered by the insured, there being a direct relationship between the covered warranty and the injuries suffered.
Its nature is compensatory so that the insured can never obtain any benefit. At most, you will restore your situation. You will return to the exact point just before the incident occurred.
It would be best if you did not profit from damage insurance.
The Insurance Contract Law exposes articles that make obtaining any insured benefit with insurance difficult. Let us mention the most prominent:
Insured Interest
The owner of the covered asset receives the compensation. You cannot repair damage to someone who has not suffered it.
Sum Assured
It will be the maximum amount that the insurer will pay to the affected. Two values will determine the amount to be repaid: the damages produced and the sum insured. The total that the insurer will receive will be the smallest amount between those two values.
Underinsurance
Underinsurance is the case that occurs when the sum insured is less than the value of the insured good. If an accident occurs, in this case, the compensation will be the maximum of the sum insured. But if the incident is partial, the thing is complicated since the affected party will only receive an amount in proportion to the capital. How is this figure calculated?
With an established formula, we call the proportional rule:
Insured Sum and Damage Value
Over-insurance
Over-insurance would be the opposite of the previous when the sum insured is greater than the guaranteed substantial value. The insured will only receive the amount of the value of the damage that has occurred, the insured amount. But you will be thinking, would the difference that paid more lose it? No, of course not. The insurer would return that part that was overpaid.
Coinsurance
When we ensure an object by insurers, this procedure is legal and, in principle, does not have to be a problem as long as the total amount insured does not exceed the absolute value of the asset. If this were the case, the procedure followed would be the same as in the previous point.
Subrogation
In this case, we are facing a transfer of rights of the insured to the insurer. This process occurs when there is a third person responsible for the incident. With this, the company manages to claim from the person causing the accident the amount he had previously paid to his insured.
What is personal insurance?
Here, the situation changes completely. There is no longer a relationship between the covered warranty and the damage suffered. As with damage insurance, reversing to the point before the accident is impossible.
In the case of death or amputation of a member, it is impossible to repair the damage caused. In these cases, people insurance gives the affected party or beneficiary an amount previously agreed upon and reflected in the policy.
As it is impossible to calculate the value of human life, here we are not talking about compensation but the nature of savings or capitalization. Capitalization means that the insured will pay fees for what may happen in the future through salvation.
Summary
In summary, damage insurance focuses on compensatory measures to restore the insured’s situation after an incident, ensuring no profit is gained. The intricate nature of insured interest, sum assured, underinsurance, over-insurance, coinsurance, and subrogation form a legal framework that restricts unwarranted benefits. On the contrary, personal insurance diverges by offering predetermined amounts in the face of irreparable damages like death or amputation, emphasizing a form of savings or capitalization rather than mere compensation.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Discover the Best Electronic Billing Provider for Your Business
The best electronic billing provider combines automated invoicing, secure payment processing, and seamless integration capabilities to streamline your financial operations while improving cash flow. Leading providers like QuickBooks Online, Zoho Invoice, and FreshBooks offer scalable solutions ranging from free plans for freelancers to enterprise-grade platforms, with businesses saving an average of $15.16 per invoice through electronic billing adoption.
After guiding thousands of businesses through financial system transformations over my 20 years as CEO of Complete Controller, I’ve witnessed firsthand how the right electronic billing provider can revolutionize a company’s operational efficiency and cash flow management. The US electronic bill presentment and payment market has exploded to $49.8 billion in 2024 and continues growing at 8.9% annually—yet many businesses still struggle to identify which provider will deliver the transformative results they need. This article breaks down the essential features, pricing strategies, and implementation approaches that separate industry-leading electronic billing providers from the rest, giving you the insights needed to make an informed decision that accelerates your business growth.
What is the best electronic billing provider, and how do you choose one?
The best electronic billing providers deliver automated invoicing, multiple payment options, and robust integration capabilities
Top solutions include QuickBooks Online for comprehensive accounting integration, Zoho Invoice for budget-conscious small businesses, and FreshBooks for user-friendly interfaces
Key selection criteria encompass pricing structure, feature sets, integration capabilities, and scalability for future growth
Success depends on matching provider capabilities to your specific industry needs, transaction volume, and existing software ecosystem
Implementation typically delivers ROI within 3-6 months through reduced processing costs and faster payment collection
Understanding Electronic Billing Providers and Their Core Functions
Electronic billing providers serve as the technological backbone for modern business invoicing, transforming traditional paper-based processes into streamlined digital workflows. These platforms automate invoice creation, delivery, and payment processing while maintaining detailed audit trails and financial reporting capabilities.
The evolution from manual billing to electronic systems represents more than simple digitization—it fundamentally changes how businesses manage cash flow and customer relationships. Modern electronic billing software reduces invoice processing costs from $18-26 per paper invoice to just $2.50-$4 per electronic invoice, representing a 559% cost difference that directly impacts your bottom line.
Essential features of modern electronic billing software
The most effective electronic billing platforms integrate invoice automation with payment processing, offering features such as recurring billing schedules, automated payment reminders, and real-time transaction tracking. Advanced systems incorporate artificial intelligence for fraud detection and predictive analytics while maintaining compliance with industry regulations and security standards.
Cloud-based deployment has become the preferred model, providing scalability and accessibility while reducing infrastructure costs. These automated billing systems reduce manual intervention by up to 70% while improving accuracy and consistency across all billing operations.
Industry-specific electronic billing solutions
Different industries require specialized billing approaches, from subscription-based SaaS companies needing recurring payment automation to professional services firms requiring time tracking integration. Healthcare providers operate under HIPAA compliance requirements, while international businesses need multi-currency support and tax compliance features.
Understanding these sector-specific needs helps narrow the selection process significantly. Manufacturing companies might prioritize inventory integration, while consulting firms focus on project-based billing capabilities. The best electronic invoicing service adapts to your industry’s unique requirements rather than forcing you into a one-size-fits-all solution.
Comprehensive Analysis of Top Electronic Billing Providers
The electronic billing market offers solutions ranging from simple invoice generators to comprehensive enterprise resource planning integrations. Leading providers have differentiated themselves through specialized features, pricing models, and target market focus.
QuickBooks Online: The accounting integration leader
QuickBooks Online dominates the small to medium business segment by offering invoicing as part of a complete accounting ecosystem. Starting at $35 monthly for the Simple Start plan, it provides customizable invoice templates, automated payment reminders, and direct bank feed integration.
The platform’s strength lies in its comprehensive financial management approach, automatically syncing invoice data with general ledger accounts and tax reporting systems. QuickBooks processes over 24 billion customer invoices annually, making it one of the most trusted names in business accounting and billing service provider solutions.
Zoho Invoice: The budget-conscious choice
Zoho Invoice stands out by offering a completely free tier supporting up to 500 annual invoices with two users and three projects. This makes it particularly attractive for freelancers and startup businesses operating on tight budgets while still needing professional invoicing capabilities.
The platform includes time tracking, expense management, and customer portal features typically reserved for paid plans, though advanced automation and reporting require upgrading to Zoho’s broader business suite. Over 50,000 businesses globally rely on Zoho’s affordable electronic billing solutions for small businesses.
FreshBooks: User experience excellence
FreshBooks has built its reputation on exceptional user interface design and customer support, making it ideal for non-technical business owners. The platform excels in project-based billing scenarios, offering detailed time tracking and expense categorization that simplifies complex client billing.
Monthly pricing begins around $17, positioning it between free solutions and enterprise platforms while maintaining comprehensive feature sets. FreshBooks users report saving an average of 16 hours per month on billing and administrative tasks, demonstrating the platform’s efficiency focus.
Advanced Features That Separate Leading Providers
Beyond basic invoicing capabilities, top electronic billing providers offer sophisticated automation and integration features that significantly impact business efficiency and cash flow management. These advanced capabilities distinguish professional-grade solutions from basic invoice generators.
Automated billing systems and workflow optimization
The most valuable electronic billing providers incorporate intelligent automation that extends beyond simple recurring invoices. Advanced systems analyze payment patterns to optimize reminder timing, automatically adjust credit limits based on payment history, and integrate with inventory management to trigger billing upon shipment.
These automated billing systems can reduce processing time by over 80%, as demonstrated by REVA’s transformation from 15-20 minutes per invoice to under 3 minutes. Such dramatic efficiencygains translate directly to cost savings and improved cash flow management.
Cloud billing platforms and integration capabilities
Modern cloud billing platforms serve as central hubs connecting various business systems, from customer relationship management to enterprise resource planning. The best solutions offer pre-built integrations with popular accounting software, payment processors, and business management tools.
API availability enables custom integrations for businesses with unique workflow requirements. This connectivity creates seamless data flow across all operational systems, eliminating duplicate entry and reducing errors that cost businesses thousands in reconciliation time.
Strategic Selection Criteria for Electronic Billing Providers
Choosing the optimal electronic billing provider requires a systematic evaluation of both current needs and future growth projections. The decision impacts immediate operational efficiency and long-term scalability potential.
Electronic billing provider pricing structures vary dramatically, from completely free solutions to enterprise platforms costing thousands monthly. Consider total cost of ownership, including implementation time, training requirements, and integration costs when evaluating options.
Scalability and business growth accommodation
The best electronic billing providers accommodate business growth without requiring platform migration. Scalable solutions offer flexible user limits, unlimited invoice processing, and modular feature additions as needs evolve.
Enterprise-grade platforms provide multi-entity management, advanced reporting hierarchies, and customizable approval workflows essential for larger organizations. Consider your five-year growth projections when selecting a provider to avoid costly migrations later.
Implementation and ROI Optimization
Successful electronic billing provider implementation requires careful planning and phased rollout approaches. Organizations implementing electronic billing systems see average ROI within 3-6 months, with some achieving payback in as little as 60 days.
Full e-invoicing adoption could generate $116 billion for the US economy, with individual businesses saving $1.1 million annually in productivity gains. The Second City reduced processing time by half and saved $40,000 annually through their electronic billing transformation.
Migration from legacy systems demands comprehensive data cleanup and customer communication strategies. The most effective implementations establish clear data flow mapping between billing platforms, accounting systems, and customer management tools to maximize efficiency gains.
Final Thoughts
Selecting the best electronic billing provider fundamentally transforms how your business operates, manages cash flow, and serves customers. Through two decades of helping businesses modernize their financial processes at Complete Controller, I’ve seen the dramatic difference between companies that choose wisely and those that settle for inadequate solutions.
The providers analyzed here each serve specific business needs and growth stages. Your success depends on matching provider capabilities with your unique requirements: transaction volume, integration needs, compliance requirements, and budget constraints. The right choice accelerates growth while the wrong decision creates ongoing operational friction.
Electronic billing has evolved from a nice-to-have convenience to a competitive necessity. Take action today to modernize your billing processes and unlock the efficiency gains that drive business growth. Contact the experts at Complete Controller for personalized guidance on implementing the ideal electronic billing solution for your business.
Frequently Asked Questions About the Best Electronic Billing Provider
What is the difference between electronic billing and invoicing software?
Electronic billing providers offer comprehensive payment processing and billing cycle management beyond invoice creation. While invoicing software typically focuses on generating and sending invoices, electronic billing systems include integrated payment gateways, automated collection workflows, and real-time financial reporting capabilities.
How much can businesses save by switching to electronic billing?
Most businesses save 60-80% on per-invoice processing costs, reducing expenses from $18-26 per paper invoice to $2.50-4 per electronic invoice. Additionally, collection periods typically decrease by 20-35%, with total annual savings often exceeding $10,000 for medium-sized businesses processing 200+ invoices monthly.
Which electronic billing provider is best for small businesses?
Zoho Invoice offers exceptional value for small businesses with its free tier supporting 500 annual invoices, while QuickBooks Online provides superior integration for businesses needing comprehensive accounting capabilities. FreshBooks strikes an ideal balance for service-based small businesses requiring time tracking and project management features.
Do electronic billing providers integrate with existing accounting software?
Yes, leading providers offer pre-built integrations with popular platforms like QuickBooks, Xero, NetSuite, and SAP. Most modern providers also offer API access enabling custom integrations with proprietary systems, though integration complexity varies significantly between providers.
How long does it take to implement an electronic billing system?
Implementation typically takes 2-8 weeks depending on system complexity, data migration requirements, and integration needs. Simple setups for small businesses can go live within days, while enterprise implementations with multiple integrations may require several months. Most businesses see positive ROI within 3-6 months regardless of implementation timeline.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Jennifer BrazerFounder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.
Cash flow is the primary function of any business, and it determines whether your financials are running successfully. Positive cash flow means paying off your debts and liabilities and maintaining more equity than liability.
Businesses have often needed help maintaining their cash flow, even those with a profitable financial period. Even if your business is posting a profit, it may still need to do better in terms of liquidity and may face problems covering overhead expenses and payroll.
A business must have a positive cash flow to manage its day-to-day business and have a credible balance sheet.
Here are four ways to improve your business cash flow.
Offer Incentives for Early Payments
Try sending out invoices as soon as you send them out. It helps keep track of everything that’s going out, and the sooner it’s sent out, the sooner means, the sooner you can expect payment. Try to offer discounts to customers who pay on time.
For example, if your terms for payment are net thirty days of invoice submission, try offering incentives where you’ll give them a small discount if they complete the terms within fifteen days instead. This incentive especially helps customers buy bulk orders of your product or services.
The incentive will also help you save on your costs and liabilities, as you can get your cash faster to pay off expenses or invest further. By keeping your business liquid, you’ll be prepared for any sudden changes in the market or economy, and this is something on your balance sheet that shareholders and potential investors will be looking for.
Impose Penalties for Late Payments
Try to set it in your terms and conditions that any payment made after the Net 30 period will be penalized with a late fee. It shows that you’re running a serious business with professionalism and that there can be no compromise regarding payment collection.
It also helps expose you to the market and, through trial and error, can help you learn who to do business with. Any customer who doesn’t honor your net terms and offers late payments is ultimately detrimental to your company’s bottom line, and you would be better off not doing business with those kinds of unprofessional practices.
Keep Track of Your Spending and Remove Unnecessary Expenses
Identify and remove necessary expenses by doing monthly or semiannual expense reports. Try to cut out any unnecessary expenses as much as you can. Research and invest in software that can help your business grow, such as accounting software tools to help you do your bookkeeping more efficiently.
Keep track of your purchases and remove those that don’t show any significant purpose or that be replaced with something more affordable. Try purchasing your supplies in bulk as, just like with your Net Terms with customers; more suppliers will offer discounts if you pay them in time.
If available, take full advantage of these discounts and try paying off your vendors as soon as possible to avoid having cash tangled around in loans and back payments.
Open a High-Interest Savings Account and a Business Credit Card
Try investing in high-interest savings accounts, as it is a safe way to help generate cash and improve your cash flow in the long run. Pay attention to applying for a credit card that has cashback options.
Be sure to use it responsibly, and you’ll be able to enjoy the benefits of receiving cashback on purchases paid on time. It is also one of the best ways to help boost your business’s credit score and help get you approved for future loans and other banking benefits.
Conclusion
Cash flow is about managing expenses and keeping your business flush with cash. The more liquid your business is, the better equipped it will be to anticipate unforeseen circumstances.
It is vital for future investments, expense budgets, and the daily welfare of the organization. Regardless of the profitability of your business, it will be less successful than a company that may project fewer profits but with a much stronger cash flow statement in the same period.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Customer Experience Management is the discipline of designing, monitoring, and improving every interaction across the customer journey so you can deliver seamless, personalized experiences that increase satisfaction, deepen trust, and drive long-term loyalty. It spans every touchpoint—from the first ad a prospect sees to the renewal email they receive three years later—and uses feedback, analytics, and cross-team collaboration to turn ordinary transactions into reasons customers stay.
Here’s a stat that stopped me in my tracks: 86% of buyers say they’ll pay more for a better customer experience, with U.S. consumers willing to pay an average of 17% more, according to Harvard Business Review. After 20+ years leading Complete Controller and partnering with thousands of businesses across nearly every industry imaginable, I can tell you with certainty: loyalty isn’t bought with discounts—it’s earned through experience. In this article, I’ll walk you through how to build a CXM system that strengthens retention, sharpens your competitive edge, and turns happy clients into your loudest advocates—even if you don’t have an enterprise budget.
What is customer experience management and how does it boost customer loyalty?
Customer Experience Management is the practice of intentionally designing, measuring, and improving every customer interaction to grow satisfaction, trust, and loyalty across the full journey.
It covers every touchpoint—digital, human, and product-based—so the experience feels consistent no matter where customers engage.
Strong CXM reduces friction and emotional drop-offs, which directly fuels repeat purchases and referrals.
It relies on feedback loops, experience analytics, and journey mapping to uncover and fix pain points before they cause churn.
Done well, CXM lifts customer lifetime value (CLV), lowers acquisition costs, and creates a moat competitors can’t easily cross.
What Is Customer Experience Management (CXM)?
Customer Experience Management is a company-wide strategy for planning, delivering, and refining every interaction a customer has with your brand. It’s less about a single department and more about a shared mindset: every team—from marketing to accounting services to support—plays a role in how customers feel about doing business with you.
The companies that win at CXM treat experience as a discipline, not an afterthought. They map it, measure it, and improve it the same way they manage cash flow or inventory.
Core components of effective customer experience management
A strong CXM foundation includes four building blocks that work together:
Customer-centric strategy & culture — Leadership, hiring, and incentives all point toward delivering great experiences, not just hitting quotas.
Customer feedback management & VoC programs — Structured systems for collecting reviews, survey data, and support insights.
Experience analytics & CX metrics — CSAT, NPS, CES, churn, and CLV that tie experience to revenue.
Cross-functional collaboration — Sales, service, ops, and finance share one view of the customer.
Disney offers one of the clearest examples of CXM culture in action. Employees use “onstage” and “backstage” language—staying fully in character with guests onstage while handling logistics and problems backstage. The Disney Institute built an entire training philosophy around this idea, and it’s why a trip to Disney feels effortless even when the operational machinery behind it is enormous.
How Customer Experience Management Drives Loyalty, Retention, and Growth
Customer Experience Management directly strengthens loyalty by reducing friction, adding value, and building emotional trust at the moments that matter most. Research published in the Journal of Asian Business and Economic Studiesconfirms a strong positive link between CXM practices and customer loyalty behaviors—meaning the better your experience, the longer your customers stay.
And it’s not just about retention. Remember that HBR data point? Customers will pay 17% more for a better experience. That means CXM isn’t a cost center—it’s a margin booster.
The loyalty engine: From satisfaction to advocacy
Loyal customers don’t just renew. They:
Buy more often and across more product lines
Tolerate occasional missteps because trust is established
Refer new business at a rate paid acquisition can’t match
Provide candid feedback that fuels continuous improvement
Proactive customer success management—guiding customers toward outcomes rather than waiting for complaints—is one of the strongest loyalty levers I’ve seen in subscription and service businesses.
Measuring loyalty: NPS, CSAT, and CES
You can’t improve what you don’t measure. The three metrics I recommend every small business track:
NPS surveys measure willingness to recommend (the closest proxy for loyalty)
CSAT tracking captures satisfaction right after specific interactions
CES (Customer Effort Score) reveals how easy you are to do business with—often the strongest predictor of churn
Great customer experiences don’t happen by accident. See how Complete Controller helps businesses build systems that keep customers coming back.
Customer journey optimization means mapping every step a customer takes with you, then deliberately removing the friction. It’s the difference between hoping the experience is good and engineering it to be.
When I look back at our own growth at Complete Controller, the biggest loyalty gains came not from new features, but from removing small frustrations clients didn’t even realize were grinding on them.
Touchpoints — every channel and interaction at each stage
Emotions — what customers feel and where they get stuck
Moments of truth — the high-stakes interactions that make or break loyalty
Turning journey insights into action
Once you’ve mapped the journey, prioritize ruthlessly. Score each opportunity by loyalty impact and feasibility, then build a focused 90-day roadmap. Strengthen incident and issue resolution first—because nothing kills loyalty faster than a problem handled poorly. Predictive churn modeling, which combines behavioral signals with CX metrics, helps you reach at-risk customers before they walk.
Omnichannel Experience Management: Consistency Across Every Touchpoint
Omnichannel experience management makes sure customers get a seamless, consistent experience across web, mobile, phone, email, and in-person channels—without repeating themselves. The difference between multichannel and omnichannel is context: in true omnichannel, the conversation continues wherever the customer goes.
Building omnichannel support that feels effortless
Speed matters more than most leaders realize. Microsoft’s Global State of Customer Service found that 90% of consumers consider an immediate response important when they have a service question—and 60% define “immediate” as 10 minutes or less.
To deliver that kind of responsiveness without burning out your team:
Match staffing and tools to the channels your customers actually prefer
Blend self-service (knowledge bases, chatbots) with human support for high-emotion issues
Standardize tone, response times, and resolution processes across every channel
Using Customer Feedback and Experience Analytics to Continuously Improve
Customer feedback management and experience analytics give you real-time insight into how customers feel—before loyalty quietly erodes. A solid VoC (Voice of Customer) program blends surveys, interviews, social listening, and support transcripts to capture both numbers and nuance.
The most underrated step? Closing the loop. When you respond to feedback, explain the fix, and tell customers what changed, you transform a survey into a trust-building moment.
Experience analytics for smarter decisions
Blend CSAT, NPS, CES, and behavioral data into segment-level views so you can spot which experiences drive retention and which quietly drive customers away. Build a simple executive dashboard, then commit to a monthly CX review where leadership actually makes decisions based on it. For more on weaving analytics into your operating rhythm, see our guide to financial reporting and business analytics.
A Practical CXM Playbook for Small and Mid-Sized Businesses
You don’t need an enterprise budget to deliver standout experiences. Here’s a 90-day plan I’ve recommended to dozens of SMB clients:
Days 1–30: Listen and map. Interview 10–15 customers, sketch journey maps for your top segments, and launch basic NPS and CSAT surveys.
Days 31–60: Fix the top three friction points. Think clearer invoices, faster email turnaround, simpler onboarding.
Days 61–90: Standardize and measure. Document SOPs, formalize your VoC program, and start a monthly CX review meeting.
A lean CX stack—CRM with support module, a survey tool, shared knowledge base, and a simple dashboard—will get you 80% of the value the enterprise systems deliver.
Final Thoughts: Make CXM Your Most Reliable Loyalty Strategy
After two decades of watching businesses rise, plateau, and reinvent themselves, I can tell you the ones that endure share a common trait: they treat customer experience as seriously as they treat their financials. Better journeys, faster support, and earned trust outlast every price war and feature race.
Start small. Map one journey. Launch one survey. Fix one high-impact friction point in the next 30 days. Then do it again. That’s how loyalty compounds.
If you’d like help building the systems—financial, operational, and experiential—that keep clients coming back, visit Complete Controller and let’s talk. My team and I would love to help you build something customers won’t want to leave.
Frequently Asked Questions About Customer Experience Management
What is customer experience management (CXM)?
Customer Experience Management is the practice of intentionally designing, measuring, and improving all interactions a customer has with your company to grow satisfaction, loyalty, and advocacy across the full journey.
What is the role of customer experience management?
CXM’s role is to align people, processes, technology, and data around delivering consistent, positive experiences that differentiate your brand, reduce churn, and drive sustainable revenue growth.
What are the 3 main components of customer experience?
The three core components are the customer journey and touchpoints, the emotional and functional experience at each step, and the organizational systems (people, processes, tech) that enable or hinder that experience.
What are the types of customer experience?
The main types include digital experience (web, mobile, apps), human-assisted experience (phone, chat, in-person), and product or service experience (using the product and achieving outcomes). Together they shape overall brand perception.
Why is customer experience management so important for businesses today?
Because customers have more choices and lower switching costs than ever, CXM is critical for retention, lifetime value, and building a competitive advantage rooted in trust and ease—not just price.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Jennifer BrazerFounder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.
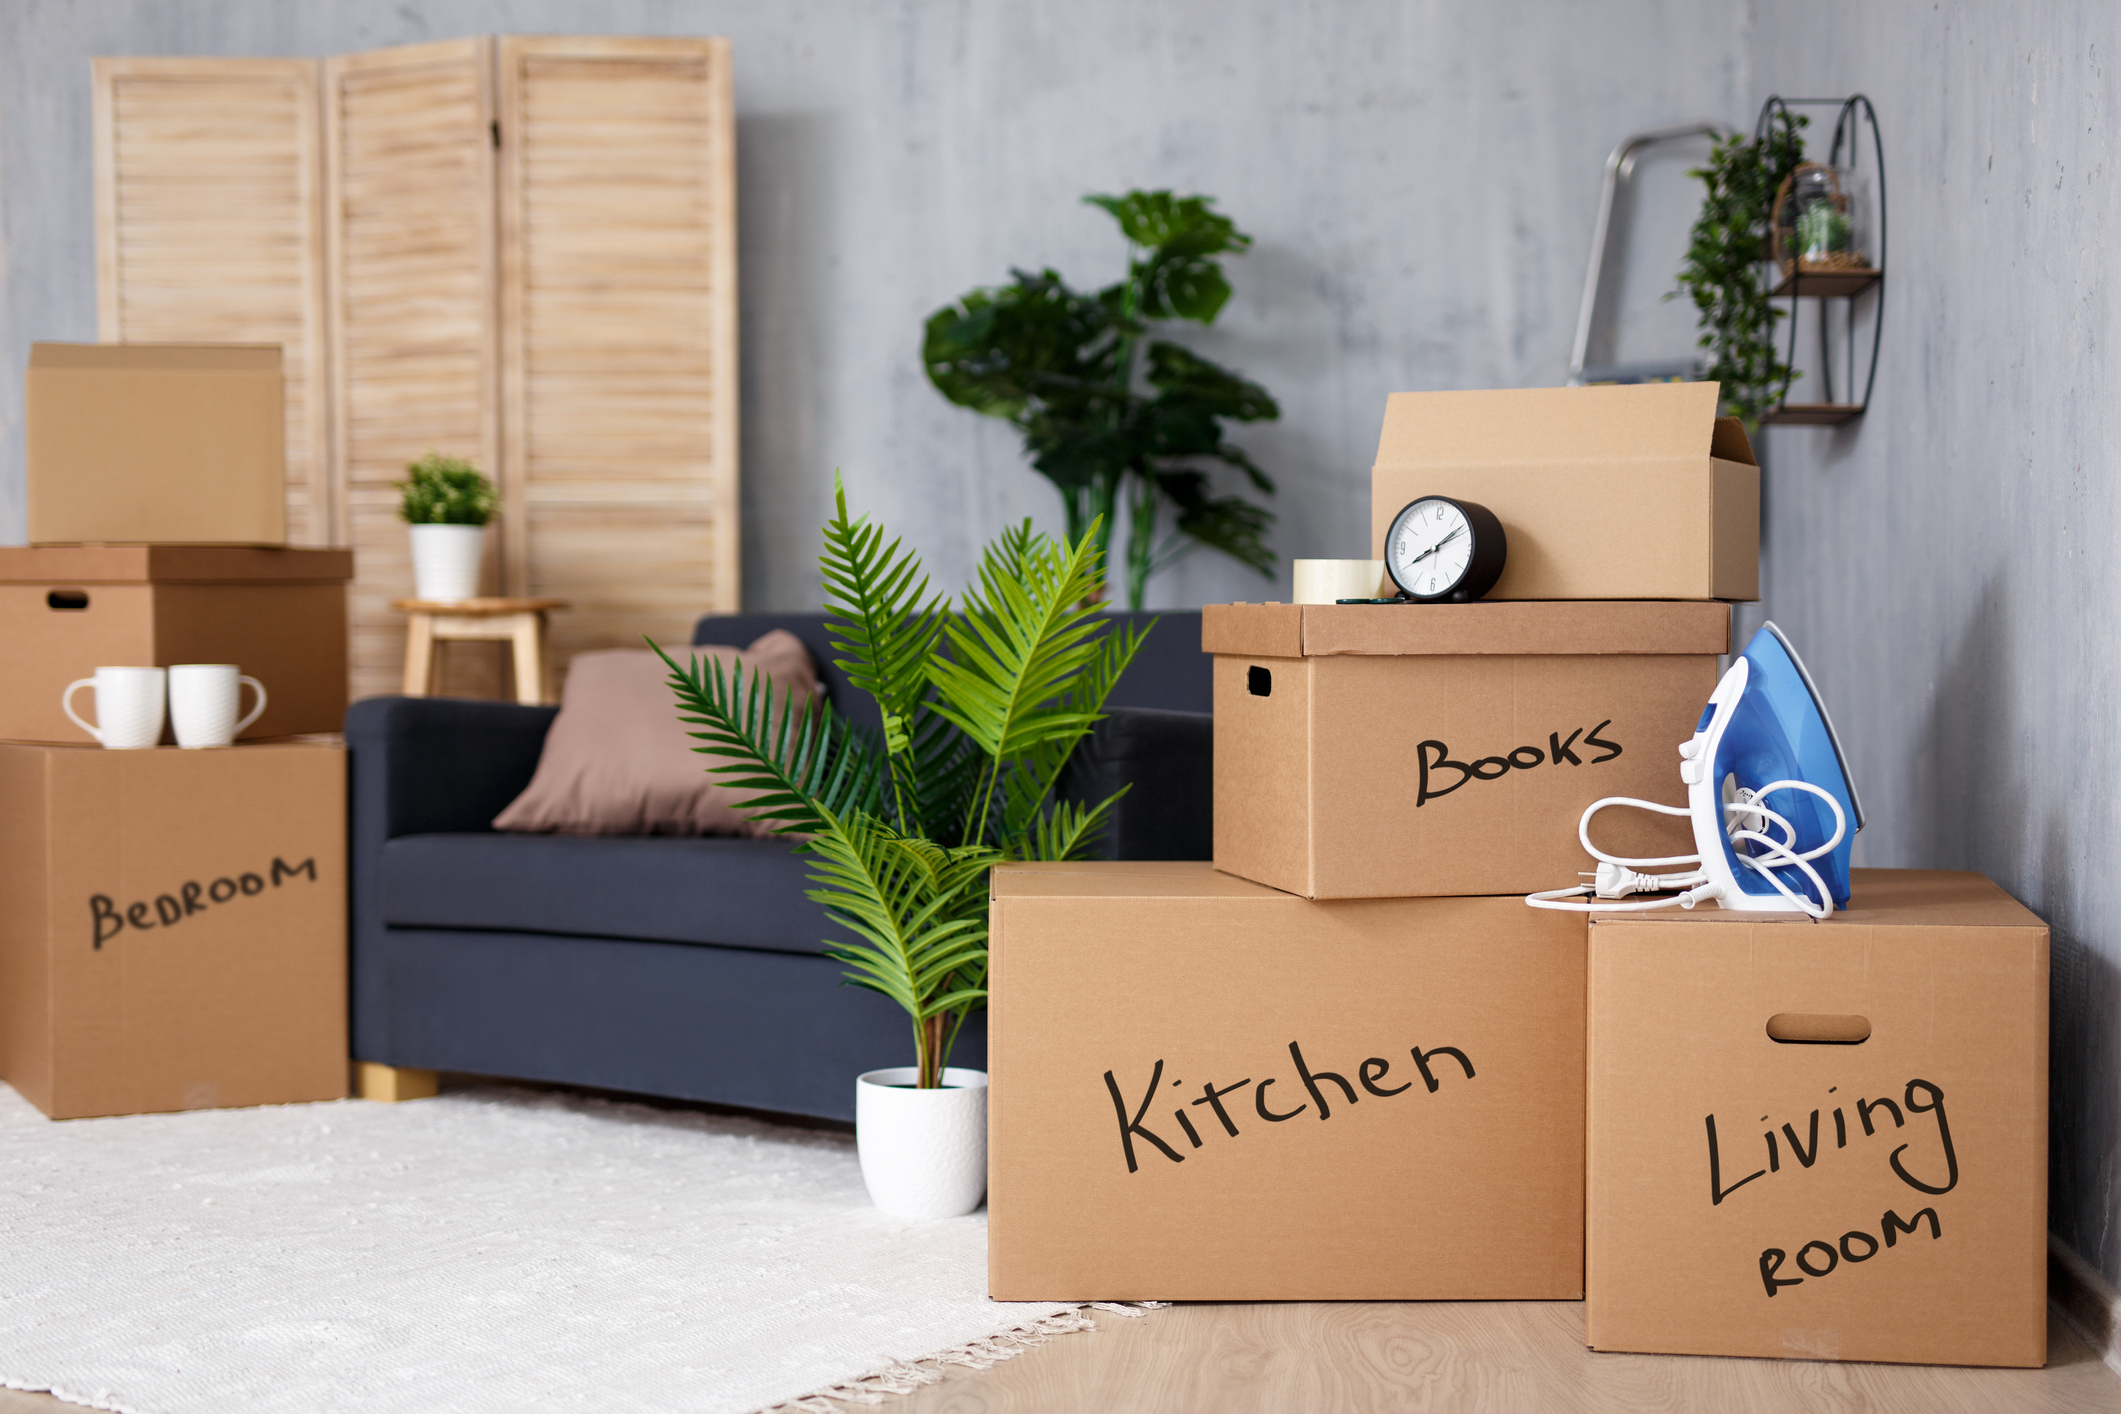
 Unnecessary Items
 Hiring Professional Movers
 About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.