Time is money. This statement is what every successful business owner and professional knows and practices to make the most of their time. For start-up entrepreneurs, “Time Management” is how you choose to use your time to maximize your productivity in achieving your specific business start-up goals.
Just as bookkeeping is mandatory in making and maintaining financial records, effective time management is also crucial for entrepreneurs to achieve their business goals. They are ultimately responsible for every aspect of their company. They have to allocate the right amount of time to the right business tasks to keep their organization running smoothly. Here are fifteen excellent time management tips for start-up entrepreneurs.
Set Goals the Right Way
Begin with verifying your start-up goals and set them the right way. Setting your goals in the right way will help you stay focused on them and eliminate hindrances as much as possible. On the contrary, goal setting in the wrong way will lack the proper targets, eventually forcing you to fall off the track. Make the most of the SMART goal setting method. SMART is an acronym for S-Specific, M-Measurable, A-Attainable, R-Relevant, T-Time Bound. Make sure your goals are powerful and meaningful enough to push you to achieve them.
Prioritize and Delegate
Prioritizing your personal and professional goals and delegating your routine activities to a reliable and capable person is among the most important of all time management tips. This also ensures reduced stress and outstanding productivity.
Find a Great Time Management System
Depending on your choice, organizational culture, and start-up goals, find a sound time management system that you can accomplish most effectively. Many entrepreneurial enthusiasts find that Covey’s quadrant time-management system is the most suitable and sufficient. This identifies your goals into urgent, non-urgent, important, and not important categories.
Audit your Time for a Week Straight
Spend an entire week consistently straight, to assess how you use your time that you have right now. Monitor your activities, record them in a journal or on your cellphone app, split up the activities’ duration into blocks of one or half an hour, and analyze how you worked, used your time, and wasted time. At the end of your seventh day, tally up all the numbers. Thereby, you will know areas for improvement.
Work on MITs in the Morning
Always focus on your start-up goals and begin your day by working on your most importanttasks (MITs). Achieving them will render you the most significant motivation and momentum to stick with your work.
Follow the 80-20 Rule
The 80-20 rule is another essential time management tip that states that 80% of your efforts come from 20% of your results. When working on your sales start-up goals, it means that 80% of your sales come from 20% of your clients. Consequently, identifying that 20 % of your efforts will generate 80% of the results. With accurate tracking and analysis, you can scale that out to work smartly.
Adopt Good Habits
All good habits, such as self-discipline, self-initiative, efficiency, accuracy, teamwork, and office etiquette, serve as excellent time management tips to manifest your start-up goals. Thus, practice them and continuously improve on your areas of weakness.
Eliminate Bad Habits
Our bad habits are our biggest time-wasters. They can include procrastination, lying, negativity, tardiness, poor communication, social media addiction, bad body language, inattentiveness, inefficiency, and temper tantrums. Thus, try eliminating them as much as you can.
Take Frequent Breaks
Breaks are essential to relax your body and recharge your mind. Keeping your physical, mental, and emotional state at peak levels by taking at least 10 minutes of a break in an hour is essential for management tips.
Exercise and Meditate
Daily meditation and physical exercise are a great way to maintain a physical and mental balance that render efficient performance. Thus, practice them in the morning or evening at your convenience.
Make To-Do Lists
Making a to-do list every evening for the next day is an excellent way to stay effective and efficient throughout the day. Also, it helps you stay consistent and closer to your start-up goal realization.
Seek Mentorship for Guidance
Find a mentor who has excellent expertise in time management tips, have been through a similar wringer you are in, and help you fulfill your start-up goals. Good mentorship enables you to stay on track with your time and goals.
Cut Down on Distractions
Clutter and disorder in your office or workplace will distract you, making you lose your time by focusing on unproductive activities. Thus, reduce such distractions by making things neat, clean, and organized. Also, avoid checking your social media accounts during the workday. That can wait.
Turn Off Unimportant Alerts
Promotional emails, subscription updates, and app alerts distract you. Therefore, turn off social media app alerts and hire an assistant, if you can, to manage your emails and other less critical tasks. They can also update you about important emails that come through while you are working.
Trust Yourself
By the day’s end, time management tips are not things that will be mastered overnight. You have to persevere. Also, be confident about yourself. With consistent practice and patience, you will learn how to manage your time effectively and achieve your start-up goals.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Cloud’s Role in Economic Growth: Key Insights & Benefits
Economic growth through cloud computing enables businesses to scale efficiently, reduce costs, and accelerate innovation across all sectors of the economy. Cloud technologies serve as a powerful economic multiplier by democratizing access to enterprise-level tools and infrastructure that previously required massive capital investments.
I’ve witnessed firsthand how cloud adoption transforms financial outcomes for businesses of all sizes. After 20+ years guiding Complete Controller clients through digital transformation, I’ve seen cloud solutions cut operational costs by up to 50% while simultaneously boosting productivity and market reach. Throughout this article, I’ll share practical insights to help you leverage cloud technologies for measurable economic gains—whether you’re a solopreneur or scaling a mid-market company.
What is cloud computing’s role in economic growth, and how does it benefit businesses?
Cloud computing drives economic growth by reducing IT costs, enabling rapid scaling, and creating new business models and revenue streams
Cloud infrastructure eliminates capital expenditures on hardware and maintenance, converting fixed costs to variable expenses
Pay-as-you-go models allow businesses to align technology spending with actual usage, improving cash flow management
Cloud platforms enable businesses to deploy global services instantly, reaching international markets without physical expansion costs
Advanced capabilities like AI and machine learning become accessible to organizations of all sizes, democratizing innovation
How Cloud Computing Fuels Economic Growth
Cloud computing has evolved from a tech industry curiosity into a fundamental economic driver across all sectors. The macroeconomic impact is staggering—cloud adoption is projected to generate $12 trillion in global GDP by 2030, with $2.7 trillion from APAC regions alone and $216.8 billion specifically from energy productivity gains.
This explosive growth stems from the cloud’s ability to dramatically lower barriers to market entry. Small businesses can now access computing resources previously reserved for enterprises with deep pockets, creating a more dynamic and competitive business environment that stimulates broader economic expansion.
Market expansion & global reach
Cloud providers like AWS, Microsoft Azure, and Google Cloud now command 94% of the $94 billion quarterly cloud infrastructure market. This massive spending fuels job creation not just in tech hubs but across regions where data centers, AI research facilities, and cybersecurity operations are established.
The economic ripple effects extend far beyond the tech sector itself. Traditional industries from manufacturing to agriculture now leverage cloud infrastructure to optimize operations, reach global customers, and develop new digital products and services.
Financial impact on organizations
Companies that migrate at least 60% of their workloads to the cloud consistently report measurable financial benefits:
The U.S. cloud economy has demonstrated remarkable long-term growth, tripling from 2002–2017 and adding $214 billion to GDP in 2017 compared to just $78.1 billion fifteen years earlier. This trajectory illustrates how cloud technologies act as factors influencing economic growth far beyond the technology sector itself.
Economic Benefits of Cloud Adoption
Cloud adoption delivers both immediate cost savings and long-term revenue benefits that compound over time. Organizations that strategically embrace cloud technologies experience fundamental shifts in their business economics.
Revenue generation & margin improvement
SaaS spending is projected to hit $300 billion in 2025, driving entirely new service models and revenue streams that weren’t possible with traditional software. Dell reports that cloud-adopting firms experience 53% faster revenue growth compared to competitors still relying on legacy systems.
A manufacturing client of Complete Controller reduced their monthly accounting cycles by 40% after moving to cloud-based financial tools. This freed valuable resources for product innovation and market expansion initiatives that generated $1.2 million in new annual revenue. The economic benefits of cloud adoption extend far beyond operational efficiencies into fundamentalgross domestic product and economic development improvements.
Cost efficiency & resource optimization
Netflix’s migration to AWS stands as a landmark case study in cloud economics. Between 2010 and 2021, the company reduced streaming infrastructure costs by 50% while simultaneously improving global service reliability and scaling to support hundreds of millions of subscribers.
The cloud’s pay-as-you-go model eliminates upfront IT capital expenditures, a critical advantage for:
Startups needing enterprise-grade infrastructure without massive investment
Seasonal businesses with fluctuating computing demands
Companies seeking to shift from CapEx to OpEx models for improved cash flow
Cloud providers achieve economies of scale impossible for individual businesses, passing these savings on through increasingly competitive pricing models.
Cloud adoption boosts productivity. 👉 At Complete Controller, we help convert it into measurable financial gains.
Emerging Trends Driving Economic Transformation
The cloud’s economic impact continues to evolve as new technologies merge with and build upon cloud infrastructure. These emerging trends represent the next wave of cloud-driven economic growth.
AI-driven growth & innovation
AI services grew an astonishing 140-160% year-over-year in 2025, with 81% of U.S. businesses using AI/machine learning relying on cloud infrastructure. This convergence of cloud and AI is expected to drive 21% projected GDP growth from artificial intelligence by 2030.
This trend accelerates economic transformation through:
GenAI deployment – Enabling companies to automate content creation, product design, and customer interactions
Real-time data processing – Creating predictive models that optimize everything from inventory management to financial forecasting
Hyperautomation – Combining AI, ML and RPA to automate complex business processes end-to-end
For businesses, these capabilities translate into productivity gains, cost reductions, and entirely new revenue models based on insights extracted from vast amounts of data.
Sustainability & global market penetration
Cloud adoption supports sustainable economic growth through multiple mechanisms:
Energy-efficient data centers operated at scale by major providers
Reduced need for on-premises servers and associated cooling systems
Remote work enablement, cutting commuting emissions and office space requirements
Additionally, cloud platforms democratize global market access. Companies of all sizes can now establish international operations and customer relationships without the traditional costs of physical expansion, creating more resilient and diversified revenue streams.
Strategic Implementation for SMBs
Small and mid-sized businesses stand to gain disproportionately from cloud adoption, but implementation requires a strategic approach tailored to their unique constraints.
Roadmap for cloud transition
The most successful SMB cloud transitions follow a structured approach:
Assess Workload Capacity → Measure current infrastructure needs and identify priority migration candidates
Prioritize SaaS Tools → Adopt cloud-native applications for immediate ROI in finance, CRM, and operations
Monitor Costs → Implement usage analytics to optimize spend and prevent unexpected scaling expenses
Develop Talent → Train existing staff or hire specialized skills to maximize cloud platform benefits
Implement Smart Investment Strategies → Reinvest savings from operational efficiencies into growth initiatives
Indian SMBs using cloud services have demonstrated the economic potential of this approach, seeing 308% higher cash flow and triple the profitability improvements within just two years of adoption. These remarkable outcomes underscore why 80% of small businesses report that cloud technologies directly help them grow their business.
Industry-specific implementation approaches
Different industries benefit from tailored cloud adoption strategies:
Retail: Focus on customer data platforms and inventory management
Healthcare: Prioritize secure patient data storage and telehealth capabilities
Manufacturing: Implement IoT connectivity and predictive maintenance
Professional Services: Deploy collaboration tools and client portals
At Complete Controller, we guide clients to start with scalable cloud bookkeeping and financial management tools before expanding to full infrastructure migration. This approach delivers quick wins while building confidence for broader transformation.
Balancing Growth with Sustainability
The cloud’s economic benefits must be balanced against important sustainability considerations. This tension creates both challenges and opportunities for businesses.
Environmental & economic tradeoffs
While cloud adoption reduces physical server costs and individual company carbon footprints, rising data center demand (growing 10% year-over-year) creates significant energy challenges at a macro level. Organizations must carefully consider the relationship between economic growth vs. environmental sustainability when developing their cloud strategies.
The economics of this balance include:
Scalability benefits vs. carbon footprint concerns
Cost savings vs. infrastructure investments
Operational flexibility vs. data sovereignty requirements
These tradeoffs inform critical business decisions around public vs. private cloud deployment, data center locations, and economic policies that shape regulatory environments.
Future-proofing cloud investments
To maximize long-term economic returns, organizations must future-proof their cloud investments by:
Selecting providers with clear sustainability roadmaps
Building flexibility into architecture to avoid vendor lock-in
Developing governance frameworks that balance innovation with compliance
Continuously measuring ROI against business objectives
This approach ensures that cloud investments continue delivering economic benefits while adapting to evolving environmental, regulatory, and competitive landscapes.
Final Thoughts: Harnessing Cloud Economics for Your Business
Cloud computing isn’t just changing how we use technology—it’s fundamentally reshaping economic possibilities for businesses of all sizes. The data is clear: organizations that strategically adopt cloud technologies grow faster, operate more efficiently, and adapt more successfully to market changes.
I’ve guided hundreds of businesses through this transformation at Complete Controller, and the pattern is consistent. The companies that thrive recognize that cloud adoption isn’t simply an IT decision but a strategic economic investment that impacts every aspect of their business model.
Ready to accelerate your economic growth through optimized cloud adoption? Contact our team at Complete Controller for a personalized assessment of how cloud financial services can transform your business economics and position you for sustainable growth.
FAQ
How much can cloud computing actually reduce operational costs?
Most businesses see 20-30% operational cost reductions after comprehensive cloud migration. These savings come from eliminated hardware maintenance (8-12%), reduced IT staffing needs (10-15%), and improved energy efficiency (5-8%). Companies with seasonal demand patterns often report even higher savings, sometimes exceeding 40% annually.
What industries benefit most economically from cloud adoption?
Technology, retail, and financial services typically see the highest economic returns. Tech companies leverage cloud for rapid product development and scaling; retailers benefit from improved inventory management and customer data analytics; financial firms gain from enhanced security and compliance capabilities while reducing infrastructure costs.
How does cloud computing specifically contribute to GDP growth?
Cloud computing contributes to GDP through multiple mechanisms: creating high-wage tech jobs, enabling business formation with lower capital requirements, accelerating innovation cycles, improving workforce productivity, and generating entirely new digital service markets. Studies show that each dollar spent on cloud services generates approximately $3-5 in broader economic activity.
What’s the ROI timeline for small businesses investing in cloud migration?
Small businesses typically see positive ROI within 6-18 months of cloud migration. SaaS applications generally deliver returns within 3-6 months, while infrastructure migrations may take 12-18 months to reach breakeven. The fastest returns come from reduced hardware costs and improved workforce productivity, while longer-term benefits include new revenue opportunities and market expansion.
How can businesses measure the economic impact of their cloud investments?
Businesses should track multiple metrics: direct cost savings (infrastructure, energy, staffing), revenue growth tied to cloud capabilities, time-to-market improvements, customer acquisition costs, employee productivity gains, and reduction in system downtime. The most comprehensive approach combines these metrics into a cloud economic value assessment updated quarterly.
Sources
AWS Public First Report. (2021). “U.S. Cloud Economy Impact Analysis.” Public First. https://awsus.publicfirst.co
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Jennifer BrazerFounder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.
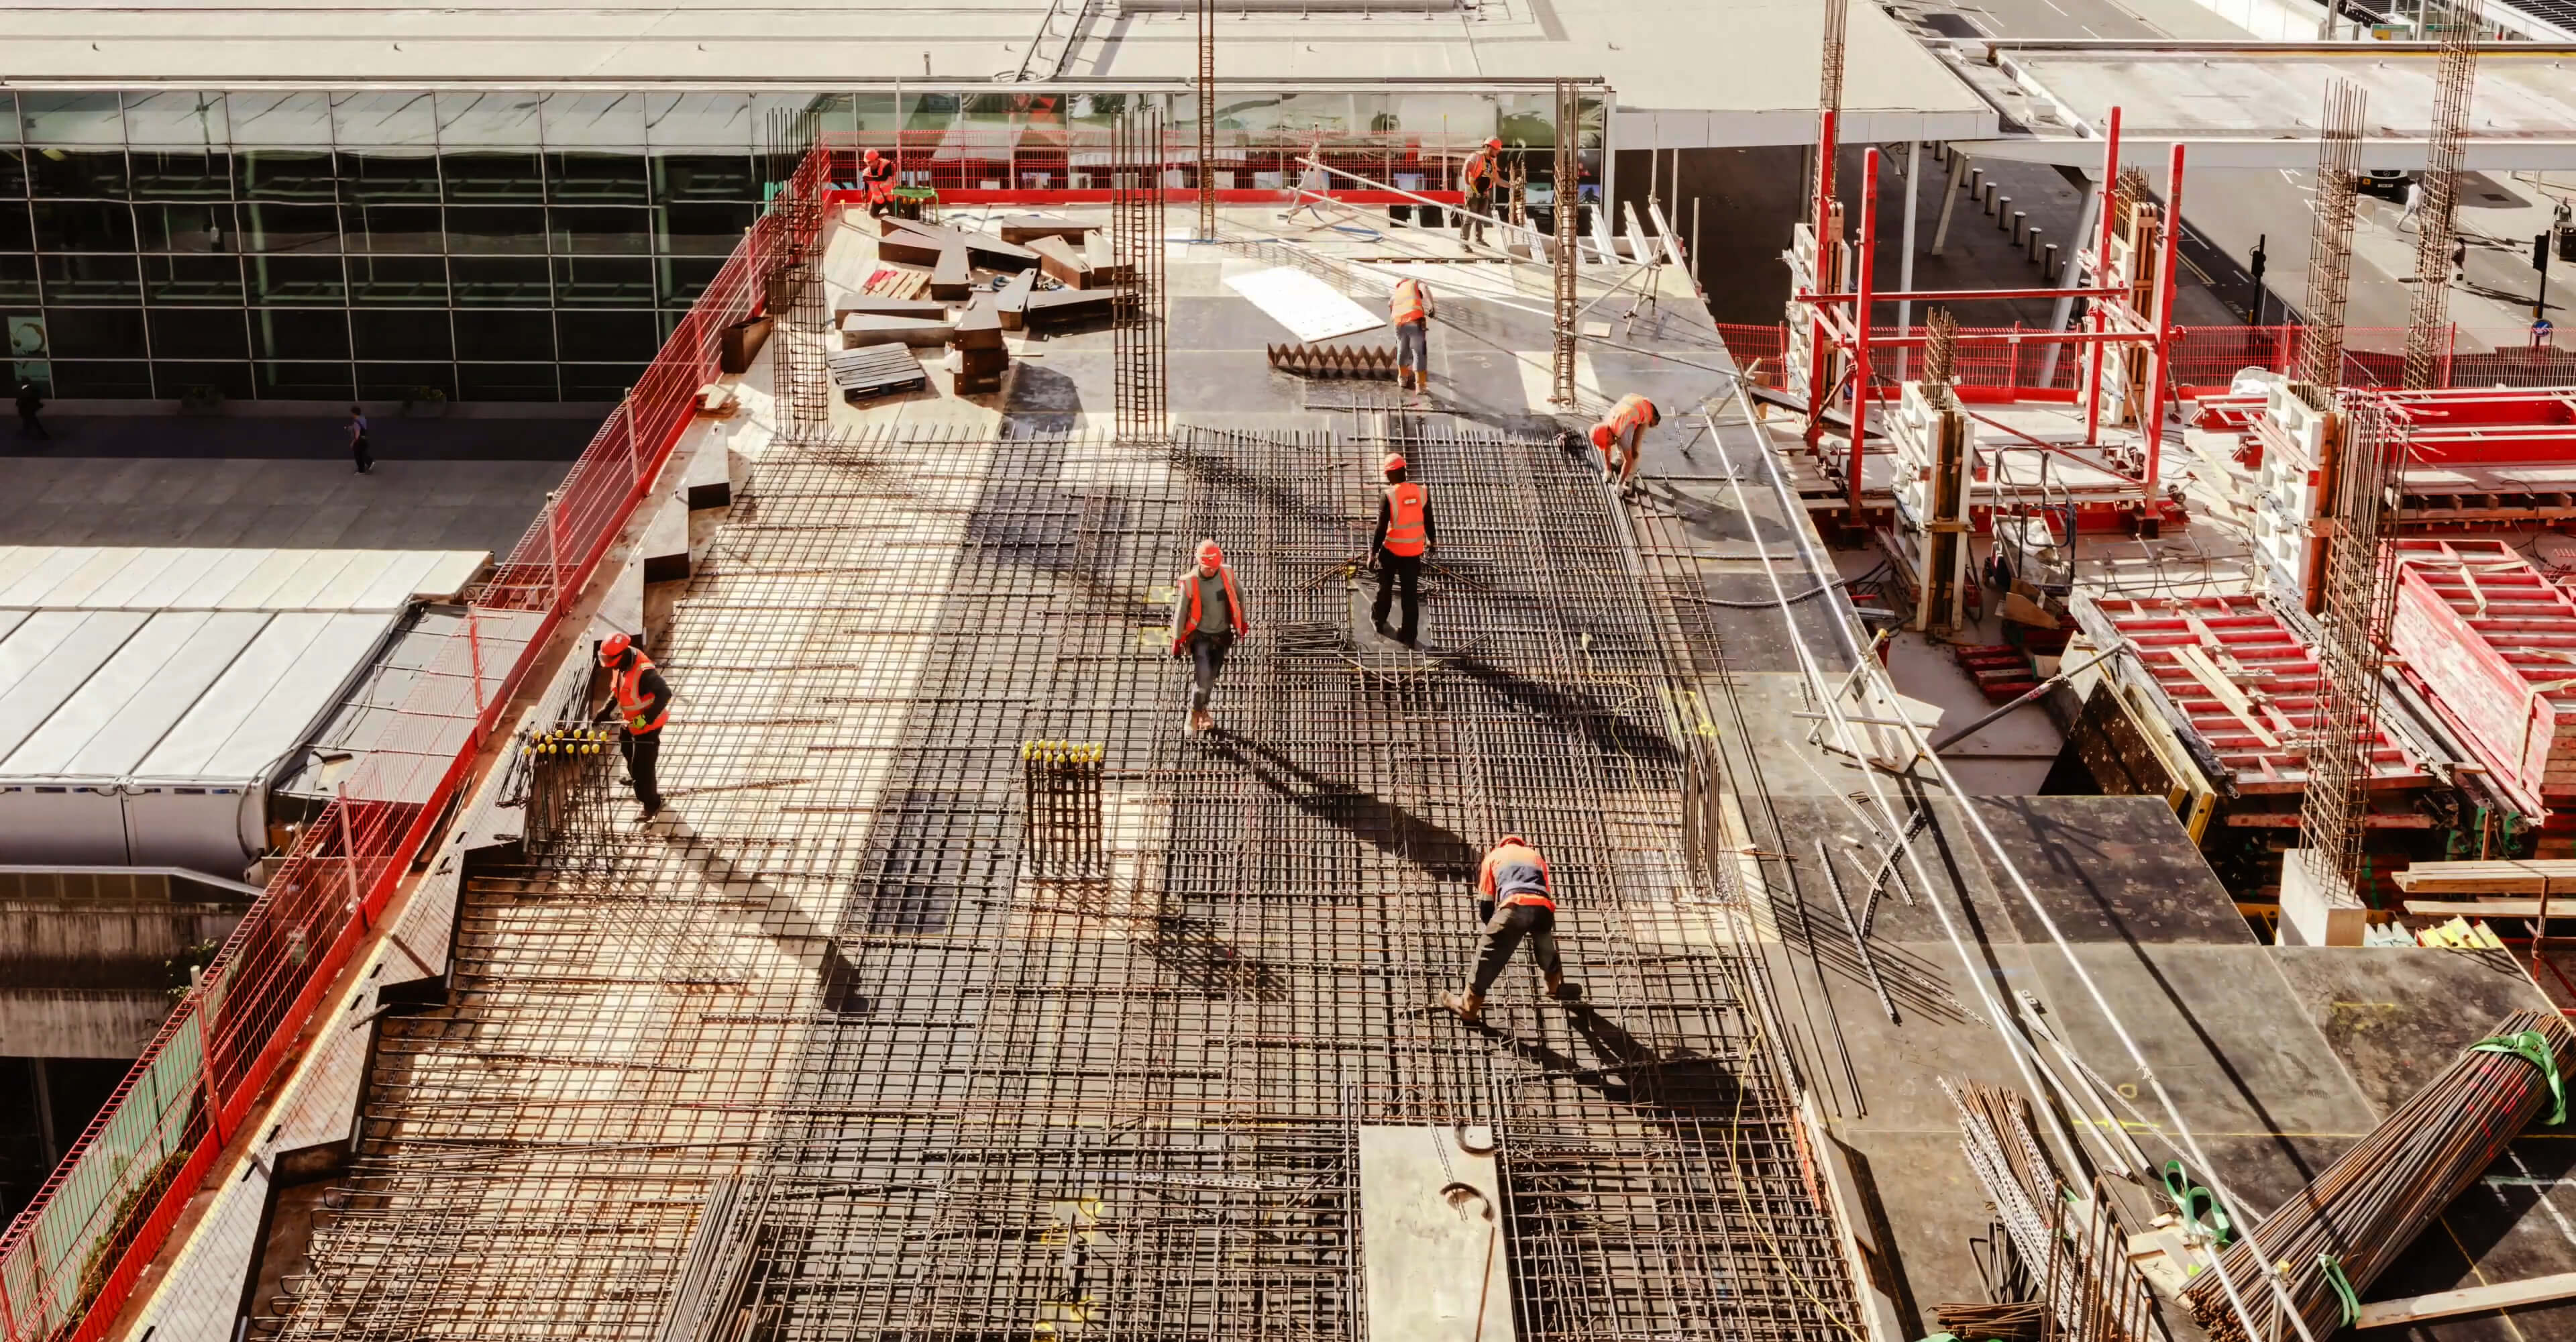
Businesses operate in a complex and ever-changing industry. Commercial properties are mushrooming in every corner of every city. Unfortunately, not many people are aware of what goes on behind the scenes of a construction company.
Those working for a construction company are aware of the challenges they face daily during their routine jobs. It’s a significant challenge for any construction company to complete a structurally sound commercial building on the designated time and budget. Here are the top five challenges that a construction company faces regularly.
Government Regulations
Construction companies are one of the most regulated ventures. The government keeps these companies under intense scrutiny. Building codes are restrictive, and licensing and permit requirements are challenging to achieve. Companies must adhere to many different regulations, as unsafe buildings constitute a significant security risk for every city. However, it’s hard to meet the local and federal government’s strict regulations and safety standards.
Social and Political Pressures
Social and political pressures pose a challenge to construction companies so much that projects are held in progress for years. Pressure from the local community could delay or cancel a construction project that could be devastating for a construction company with losses in millions. The political and societal challenges can be overcome by holding meetings with local communities and concerned parties.
Health and Safety Concerns
Commercial construction is one industry that suffers accidents causing fatal injuries. Every day, thousands of companies with millions of employees are working round the clock to meet deadlines. Workers are exposed to different hazards from machinery during their work, falling debris, malfunctioning equipment, electrical shocks, falls, trench, and scaffold collapses.
Apart from the human suffering, financial constraints hit commercial construction companies very hard. Some losses from accidents can cost a company millions in compensation to the worker and loss of equipment. Many of these losses can make a significant impact on proper bookkeeping within a construction company.
Construction companies can take different measures to eliminate or reduce accidents by meeting health and safety concerns. Fatal human loss and financial crisis can be overcome by maintaining high safety standards.
Shortage of Skilled Labor
The biggest asset of any company is its human resource; commercial construction companies are no different in this regard. They must have competent, trained, and highly skilled human capital to keep everything in its correct order.
The shortage of labor is a primary concern for commercial construction companies. To overcome this challenge, the construction company must take steps to work towards employee retention. Employee retention is necessary for construction companies because not many people are willing to get into the construction business as the construction work is physically demanding, challenging, and sometimes very dangerous. Paying better wages could help the company keep its employees for a more extended period.
Time Management
Construction is considered one of the most challenging industries because the biggest challenge is effective time management to meet deadlines. Simple time management becomes a significant task in construction. A natural weather calamity can rip the project off the ground causing substantial delays in meeting deadlines. Every day a construction site is closed due to bad weather or any other issue. Each day costs the commercial construction company to suffer significant financial losses recorded in bookkeeping.
This is a major challenge particular to the construction business, and seasonal changes affect it. Access issues, accidents, machinery malfunction, or breakdown can cause massive delays. Companies can improve their time management by checking the weather forecast and managing the delivery dates for necessary raw materials.
Running a commercial construction company is not easy. It is challenging and complicated. Overcoming the challenges is vital for a company to maintain its operations while managing to complete its due date.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
In the healthcare industry, it is not easy to provide a quick and smooth service while also maintaining the privacy of a patient’s information according to HIPAA requirements. Leading healthcare organizations address these demands in collaboration with Google’s cloud and make it easier for their patients to access their information under one roof.
Secure Access to Information
Google’s cloud ensures information security that HIPAA requires, allowing limited logins to health officials and patients to avoid any data theft. There is software that will enable you to identify how many times the document or information has been viewed. If the system becomes corrupted or hacked, you know that your information is securely placed in the cloud. You can apply device encryption and then share the file; authorized people can access patient data from any managed device. As a healthcare professional, it is your responsibility to ensure the security of your patients’ information.
Provide Faster Service to Patients
Many websites connect patients with healthcare physicians across the United States. They allow patients to review inputs before they even see a doctor. When a patient arrives at the clinic or hospital, they can fill out an online form that doctors, administration, and nurses can access. This way, you will already have your patient’s information and can follow-up with them immediately. Patients can even fill out a feedback survey that will help improve customer service.
Access to Important Updates and Documents
Google Cloud makes it simple to create a streamlined information center. All you have to do is move all essential data, policies, announcements, calendars, training, and resources to Google Drive and link it to the Google website. For example, a patient is visiting a general physician, cardiologist, and cardiac surgeon simultaneously. Instead of faxing or emailing information to each other, the patient’s lab reports and follow-up information should be stored on the cloud. This way, all three doctors will have access to the patient’s data from anywhere. If there is an emergency, the doctor can access the patient’s medical history right away from their device.
Healthcare practitioners can also view previous clinical follow-ups. CT scans, X-rays, and audio or video messages can be uploaded to the cloud. Patients can view their medical history as well as their financial transactions. Let’s say the patient does not have medical insurance and pays out of pocket. Instead of visiting the account’s department, they can view all payment history on the cloud. Even the accounts department can perform their bookkeeping on the cloud and go paperless.
Ensure Consistency
One of the best examples is a leading pharmaceutical company that provides patients with lifesaving medications worldwide. This company started using apps. However, not all apps can collaborate, so they moved to the cloud. Today, more than 90,000 employees of this company are using Gmail, calendar, and multiple tools to work simultaneously from 140 countries.
Google cloud is easy to use. If you hire a new employee, you can add them to the Google cloud from your admin control, and they have access to it; you do not have to wait to hear back from your IT department. For example, there is a new doctor on board, and you have to provide them with a patient’s medical history, all you have to do is add them to the cloud and have access to all of the information. Depending on the IT department can create a hindrance at times.
Mobile Healthcare
Some medically complex patients have difficulty visiting hospitals or clinics, especially kids. That is when home services are provided. For example, a speech therapist visits a child’s home for speech therapy. After the session, the therapist can directly input their device on the Google cloud and update the charts, reports, and medication list from the patient’s home. All other practitioners can view updated information right away.
If your hospitals or clinics are providing in-home services, Google cloud makes that easier. You can track or update a patient’s information on the cloud, and all other healthcare practitioners can view that information immediately.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Credit scores and credit reports reflect how well or poorly you have managed your finances. If your credit report shows negative information, it becomes critical for you to get rid of any unpaid debt. Otherwise, you may be charged with an exuberant amount of interest. If your credit report shows bad reviews of your financial behavior, it will be difficult for you to obtain credit from other creditors. You may still get some credit if and only if you collateralize it with a property or an asset. But, if you do not own any valuable assets to use as collateral, you will not be eligible to get any form of credit, leading to a worse financial situation.
The only option you are left with is rebuilding your credit to get rid of bad credit scores. Improving your credit score will help you get approved for loans or credit cards, and, as a result, you will be rewarded with better interest rates. A bad credit score is equal to or below 619 per the FICO score. Follow the mentioned steps below to get your credit score back on track.
Review your Credit Report
Make sure to review your credit file so that you know your financial position. By doing so, you will get a better idea of what points need improvement. Do you have late or missing payments? Is your credit file showing that you have a higher rate of debt utilization? Reviewing such information will help you formulate a plan on where to start to improve your credit score.
You also need to check your scores to know whether there are any errors or inaccurate payment details that are present without your knowledge. If yes, then dispute the problem and get those debts removed, which will automatically improve your score. FTC offers some great rewards in case of any dispute, which will help you rebuild your credit score.
Catch your Payments
Your payment history has a major effect on your credit report. If you fail to meet your payment deadlines, it will not improve your credit score. You will only be making it much worse. If you find it difficult to make your payments on time, you should contact your creditors to get a more suitable payment plan. Make sure to be up-front when contacting your creditors and explain your whole scenario. Let them know that you still want to pay for your responsibilities. You can also ask for services from a credit counseling agency to make a proper payment plan.
Pay your Bills on Time
You can slowly rebuild your credit by paying your bills on time. This also includes paying non-credit card bills such as utility, phone, internet, etc. Late rent and missed utility payments are reported directly to credit bureaus. Payment history helps you to establish a reliable pattern to improve your score. Make sure that you are not falling into the bad habit of making late payments. If you can make automatic payments from your bank account, utilize this not to miss any more future payments.
Avoid Closing Credit Card Accounts
Try to avoid closing your credit card accounts, whether you use them or not. The longer the history of your credit, the better it is for your score. However, if you are far behind on your payment deadlines, the only option you are left with is to get a payment plan. A payment plan is required to cancel your credit card account. But make sure to track the history of your credit score to rebuild it.
Pay Down Debt
Credit utilization is another factor to consider to improve your credit score. Credit utilization is a way to measure how much debt you have, and it is expressed as a fraction of the available credit that you use. For instance, you have an available credit of $10,000, and you only use $7,500; the amount of your credit utilization is 75%. It would be best if you planned to pay off your debt more rapidly by using the approach of credit utilization. Reducing your debt will help you to improve your credit score.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Cloud accounting technology is a new player in the economic landscape. Cloud accounting is similar to traditional accounting, and bookkeeping procedures are done on accounting software. Cloud accounting software is hosted on remote servers, similar to the SaaS (Software as a Service) business model. Data is sent to the server into a ‘cloud’ where it is processed and sent back to the user.
All application functions are done off-site, into the cloud, not on the desktop. The accounting functions are done online and not on desktop software. The internet or other network are used for the process. Users access to cloud accounting software through a cloud application service provider. The software has not to be installed on a computer. It can be accessed from any place globally, provided the cloud applications service provider is present. Features of accounting software must include:
Inventory management
Sales tracking
Contacts management and contact history tracking
Account to accept credit card payments
Generating Invoices
Financial statements, cash flow statements, and balance sheet
Budget planning
Payrolls
Taxation matters
Benefits of Cloud Accounting for Small Business
Cloud accounting technology is a new player in the economic landscape. Why? We’ve listed the reasons below.
1. Access to accounting and bookkeeping data anywhere and anytime in the world. You can spend time on other activities related to business operations or spend your quality time with family. You can go online to access cloud accounting software while sitting at home and keep yourself updated with the accounting and bookkeeping functions in your business. You always have an up-to-date view of the business’s financialstatus to make the right decisions at the right time.
2. Go paperless in accounting and bookkeeping. This step is Eco-friendly, too. Paperwork takes a lot of time for accountants and business owners. Small business owners need time to interpret accounting information. Accounting software makes it easy to interpret accountinginformation.
3. Cloud accounting software has multi-user access.
4. Cloud accounting software is automatically updated.
5. Cloud accounting reduces upfront business costs. You do not face regular maintenance and fees for upgrading the system.
A Few Cloud Accounting Software and their benefits
You can access FreshBooks from a desktop computer and mobile phone. It has many features used to simplify accounting processes. It makes it easy to track expenses, make online payments, generate customized invoices, generate reminders of late payments, purchase history with time-tracking, client records, and manage differentprojects with different rates.
Thirty days free subscription of FreshBooks is available for a new user. After that, it costs $19.95 a month.
QuickBooks is the primary bookkeeping and cloud accounting tool for small businesses and handles accounting operations. QuickBooks is developed and marketed by Intuit. QuickBooks is used to:
Generate invoices with the logo of your company and with all details required by the customers.
Process payrolls according to HR policies
Manage all business transactions, including bills from suppliers and vendors
Outright is an online cloud accounting system for small businesses and is used for trackingexpenses, profit, sales, and customers. Bank accounts and other services such as PayPal, eBay, FreshBooks, and web stores can be connected to Outright, and data can be easily exported from one app to another.
Dashboard with bank balances, expenses, and invoices
Customized reports required by the small business
Tracking cash flow in real-time
Graphical presentation of data
Data can be shared and accessible to accountant and others
Generating customizedreports and reminders to customers
Scheduling of Payments and returns
Apple, Blackberry, and Android applications are available. Many add-ons like CRM, invoicing, inventory management packages are also available on demand.
Conclusion
Cloud-based accounting technology is changing the landscape by providing its customers the services which were not available a few years ago. One can access their company’s data from anywhere in the world by logging into the account. Small business owners must avail of this technology as the costs are affordable, and benefits are more abundant than ever.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Understanding accounting, the language of finance and business, is crucial knowledge for all business owners and entrepreneurs. When starting a business, learning how to read financial statements is as important as managing other business tasks. It is more critical to understand statements rather than to continue investing money blindly.
Over time the business will expand, and transactions with other businesses, tax authorities, and people will have to be made. Business bookkeeping needs to be counted and rechecked. These transactions of business and records are maintained using various financial statements and accounting terms.
First of all, the following three are the most important financial statements in business bookkeeping.
Income Statement
The Income statement is divided into Sales and Expenses and includes the following:
Sales include: The selling of goods and services to the customers and getting monetary payments in return.
Expenses include: The purchases made on behalf of the business, employee salaries, bank loans that were received for investment or other purposes, and tax expenses that were paid as income taxes, etc.
Balance Sheet
A balance sheet is a collective form of the statement made based on all past transactions. It categorizes assets and liabilities.
Assets can be fixed assets as well as cash in the bank. It also includes the raw materials, work in progress that will yield profit, finished goods, and value-added tax. Value-added tax is the amount of money that a IRS owes you.
Liabilities comprise the payments that have to be paid by the company/business. It includes the gross amount of money that has to be paid to suppliers. Value-added tax liability is money paid to tax authorities for the sales that were done. Debt is the amount of money that has to be paid by the company to banks or other sources.
A balance sheet needs a balance.
Cash Flow Statement
A cash flow statement shows the cash (money) that flows in and the money that flows out.
A cash flow sheet includes the investing and the financing cash flow. Investing cash flow is the invested cash in the fixed assets in the business. The Financing cash flow describes the money in cash from the investors received from the investors or paid to the investors.
A third but significant form of cash flow is “Operating cash flow.” It explains the money flowed-in and flowed-out to the running business.
These three cash flows are added, and it shows the change in the amount of cash.
Conclusion
The above three financial statements are interrelated. As the incomes and expenses statement increases, the assets and liabilities on the balance sheet will increase. The assets and liabilities will decrease as per the cash flows from the cash flow statement.
Knowledge regarding financial statements interpretation is essential for entrepreneurs. Entrepreneurs need to know critical information in the credit analysis of their business. Investors and entrepreneurs must understand how accounting is done in businesses. Accounting is the language of business. But, learning the meaning of a few terms used in accounting is not enough. Entrepreneurs must understand the parts of the above described financial statements. This will help the entrepreneurs determine the values of assets. They will be able to calculate profitability and also estimate the risks of the assets of the company. They can understand the company’s financing sources. Entrepreneurs must understand the investment, credit analysis, and profitability.
Business owners/entrepreneurs can determine debt and equity with accounting knowledge in business financing. The ability of entrepreneurs to identify debt and equity shows insight into the value of a company. Understanding and accounting statement is vital for running a successful business.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
The following are the five best time management techniques to lead your business down a successful path.
Make Lists
Business owners and entrepreneurs have to do various tasks and many assignments. They have to handle many tasks. Bookkeeping and accounting are cumbersome jobs they must handle, along with a long list of other things. The best way to manage all of this is to make lists of all tasks and items you have to handle. Making lists is a huge part of all time management techniques. Lists can be memorized and used according to priority if you have an outstanding memory. The best time management solution is to enlist and write down all tasks, make lists, and pending assignments.
Four basic principles can be used for making lists:
Annual schedule: Prepare the schedule for one year. This schedule is based on daily activities.
Things to do list: Make a list of things to do daily, weekly, and monthly. All things to do tasks should be prioritized according to urgency.
People to call list: List all phone numbers you have to make phone calls to. This is an alphabetically prioritized list. Alphabetical priority means that you allocate an alphabet to each number you have to call according to priority.
Plan for the conference: Planning the meetings and conversations you need to have frequently should be enlisted according to priority. This way, you won’t ever forget an important call or meeting.
An easy and well-organized system for making lists regularly should be adopted. The habit of making lists is worth using for business success.
Tickler Files
A tickler file system is used to manage daily files and activities in an organized manner. It serves as a booster for automatic memory and lessens the mess of daily files, workload, and activities.
A tickler file is also known as a 43 folder system. It is a system in which files are arranged date wise so that on the specific date, that file will automatically be highlighted.
A tickler file is a straightforward and friendly system. Suppose you have 90 files of three colors, 30 for each month. You number them 1-30 for each month and allocate them in three different colors, i.e., blue for the current month, red for the next month, and green for the month after that. Now, you have a task that you need to perform on the 22nd of the following month. You put the note and other details on the 22nd number red file. On the 22nd of the next month, that file will automaticallyremind you of that task by pop up. This is an automatic reminder system. By using these tickler files, none of your tasks are missed or forgotten. A lot of time is saved, and timely reminders lead to business success.
In cell phones and computers, this pop-up reminder system can also be used.
Fewer Meetings
Lengthy meetings can be a waste of time. The frequency and duration of meetings should be shortened to have better time management. Meetings should be focused, and something valuable should be accomplished in each meeting. Before you call a meeting, ask yourself if it will be productive and if it is needed.
Minimizing the number of meetings you have is a good time management technique.
Block Time
Most of your time in the year should be pre-assigned and blocked to get maximum advantages out of it. Assign your time to important tasks like bookkeeping, audit, payrolls, training, etc. To succeed in the business, focus on what is essential, and use your time well.
Profit from “Odd Lot Time.”
The time you get while waiting for something is valuable. Spend that time reading, thinking, and listening. Responding to missed calls and messages during this time is not a good idea because you cannot concentrate and, most of the time, do it in a hurry.
Conclusion
The key to success in business is disciplined time management. With these five techniques, you can be a pro in handling your time.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Every girl dreams of her “big day.” Wearing the white dress, walking down the aisle, marrying the love of her life. These are all things that little girls dream about when they think of their future weddings. Now, paying for that big dream is a whole different ball game. A wedding typically costs an average American couple about $35,426, excluding the honeymoon expenses. Yes, you read that correctly. This is the maximum reported average cost since 2006.
However, you are not legally obligated to spend such a huge price tag to give your relationship a new shape and commit to living together forever. Most couples do not want to spend that much. We asked money experts and wedding specialists how to set a reasonable budget and cut costs on some of the significant expensive elements of a wedding. Here are eight great insights that you can apply to save money on your wedding day.
Be Realistic
Most couples do not see how much their wedding will cost them. They usually end up missing the mark and even setting a budget that is too low, thus far over exceeding their plan. Such a situation can push them under a heavy burden of debts. Starting a marriage in debt is certainly not as ideal as the marital relationship’s beauty and happiness are lost in paying off debt for months and months. Consequently, begin with setting realistic spending limits considering every aspect of your wedding to save money. If you suspect overspending in one area, attempt cutting back on another. It is just like doing bookkeeping when preparing a budget for your marriage. If you start by being money conscious and budget appropriate with your wedding, it will set you up for this pattern further down the line.
Use your Credit Card Wisely
It is okay to use a credit card for purchases related to your wedding as far as you are charging only the amount of money you can conveniently afford to pay off. Make the most of your accumulated credit card points towards your honeymoon, especially when you possess a card with great travel rewards.
Book a Sunday
Although Saturday is the most popular day for weddings, it is usually the most expensive day to have your ceremony. You are likely to get a venue at a lower price when choosing a Sunday or a weeknight for your wedding. While it may not be the most convenient for your guests, it will certainly save you quite a bit of money.
Choose a Religious Day
Consider having your wedding on or near a major holiday when the church is already decorated for religious marriages. This can enable you to save money on flowers and other decorations. While on other days, go for simplicity. A candlelit ceremony can be inexpensive, gorgeous, and romantic. Furthermore, a Christmas wedding is always beautiful.
Trim your Guest List
Every time you add a guest’s name to your invitation list, you are increasing the wedding budget significantly. Besides catering costs, these additional guests also require extra centerpieces, rentals, favors, etc. Although you may ruffle a few feathers, avoid inviting any person you have not communicated with for the past five years. There is no reason to feel pressured or obligated to invite each of your work colleagues. Consider making your wedding an “adult-only” occasion. This way, you won’t be stuck paying for everyone’s children as it will get pricey. You can also save a lot of money by choosing to eliminate categories like ‘friends from volunteer work’ or ‘relatives other than first cousins.’ Yes, we know that “Aunt Sue” may be briefly upset that you aren’t inviting her third cousin from Australia, but she’s not the one footing the bill when it’s all said and done.
Save Postage on your Invitations
Choose simple, sleek cards for your wedding invitations in standard envelopes. Instead of having a reply card, ask your guests to reply by telephone or online. There are so many websites out there that offer an RSVP option these days. This will not only save money from bulky, expensive cards but also cut your postage costs in half.
Look for Reasonable Food and Drink Options
A couple should always be honest with their caterer about their necessity to save money. Ask them for the least expensive entrees and whether or not a buffet will be a cheaper option than a seated dinner. Figure out whether they will allow you to bring your liquor or if serving just beer and wine will be much less expensive than a complete bar. Better yet, consider serving tea and water instead of expensive alcoholic drinks. If not, it is a good idea to have the bar open only during the cocktail hour and then serve only wine with dinner.
Take Advantage of eBay
eBay is an excellent source for everything for your wedding, from second-hand clothes to marriage favors, ring pillows, cake toppers, and more. Show patience for the auction to end as well as for shipping. Find a reliableseller whose product reviews demonstrate that the sale is of the same quality of what they claim.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
A lot of hand wringing over such an undemanding proposition: When a financial expert gives you guidance regarding your retirement account’s life savings, that person must act in your top interest.
It took quite a few years for this so-called fiduciary rule to achieve consent. And then, we have seen President Trump telling the Labor Department to revise this uncontroversial proposition, which he desires to turn over. A few days later came to a massive failure for industry players who challenged the legitimacy of Texas’s rule, where a centralized judge ruled against them.
The most proper technique to understand what the fiduciary debate is about is to sight this debate through the lens of fees. Every time you do business with people in the financial services industry, ask them this: How much money are you making and the different ways you are making it?
The most nuancedclarification we have seen what a fiduciary is and does come from a video called Hightower Advisors posted on YouTube in 2012. There, they contrast butchers and nutritionists. Butchers provide meat, possibly the best meat they have. Nutritionists, on the other hand, tell you what is best to eat. When searching for advice on your life savings, you probably desire to speak to the nutritionists and not the butchers. However, the butchers of the financial world are in a pretty good spot right now. After all, we have just seen eight years of stock market gains. You will see this pitch soon enough and, when you do, there is an extensive list of questions you need to ask. Any time anyone is trying to sell you an actively managed mutual fund, a real estate investment trust, or REIT and you don’t understand, hit them with every one of the following questions.
Questions You Need To Ask About Investment Fees
How much money will you individually make now in cash commission if we select this product? And, how much will you make later in any ongoing or trailing commission?
Is there a bonus you are qualified for which comes from your employment to this firm? Is it in danger if you do not make this sale?
Are you earning more from advertising this product than you might from putting me in a similar product from a diverse company? Are you earning more than you might if you put me in a different vehicle from the same company?
Is your company or the company that shaped this product running any contests that may lead to you getting a free trip or incentive to buy this product?
Do you get to eat lots of free food?
Then, there is some nitty-gritty. You will be offered all sorts of product features and extras, and you will need to ask the following questions:
How much more will I pay in fees if I choose to receive a sign-up bonus on my allowance? Will I get a definite minimum income or benefit if I elect to receive my money in monthly payments starting later? What if I want a death profit for my heirs? Are there precise charges for the insurance component of the product? Are there any penalties for pulling my money out before time?
As for any sub-accounts in my pension, are there expenditure ratios or fees for the money?
Does your firm stand to collect any costs that you will not split as part of your payment because they have favored one product or another or restricted their platform to specific products and locked out others?
Conclusion
However, whatever happens, so much will hinge on squishy terms like suitability, best interests, and the reasonableness of fees, legal exceptions to any standards, and whoever is adjudicating any disputes. Rather than getting caught up in all of that, it’s probably best to defend yourself from the outset. In an industry that makes a game of hiding lots and lots of fees every which way, the best possible response is to ask lots and lots of questions.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.



 About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.