All employees have the right to a safe workplace. Therefore, almost all workers are covered by compensation. Workers’ compensation can be considered as insurance paid by the employer that covers financial benefits and medical treatment for employees who get injured or suffer from: an illness as a result of their work. When an employee is injured while working, he or she has the right to request the benefits that his employer owes him by law.
Sometimes, an employee can receive retribution even if his injury was caused by his own negligence. The only circumstances that disqualify an employee are if they were intoxicated at the time of the accident or if the injury was the result of their intentional misconduct.
The coverage available to employees varies by state and occupation. Despite this, there are some things that one should do immediately after injuring oneself at work to protect their right to compensation.
1. Get medical treatment
If it is an emergency, call 911 or go to the emergency room at once. Tell the medical staff that you hurt yourself at work. If possible, contact your employer for instructions. If your injury does not need urgent treatment, you should ask your employer which doctor you need to go to be covered by your insurance. If you go to the doctor your employer has indicated and you are not satisfied, you should consider going to another doctor of your choice. Even if the workers’ compensation does not pay for a second medical visit, it may be worth it for you to pay it and have a second opinion in case you have a problem with the compensation or do not give enough to compensate the consequences of the injury. If you have health insurance, you may have a second visit.
2. Complete a report about the accident
If you were injured in an accident at work, inform your supervisor or your employer at once. In most of the United States, you only have 30 days to file a claim, and it is always best to do so as soon as possible so that your benefits do not dilate and so as not to lose the possibility of claiming your benefits. Even if you are not injured, your employer can take action to prevent accidents in the future if you report an incident. If possible, you should take notes about the event to remember all the details below. Write down any unsafe risk or condition, defective product, or action neglected by colleagues. Take into account if a colleague was present in case their testimonies are needed later to check responsibility and report all this information to your company and your union.
3. Report the injury or illness
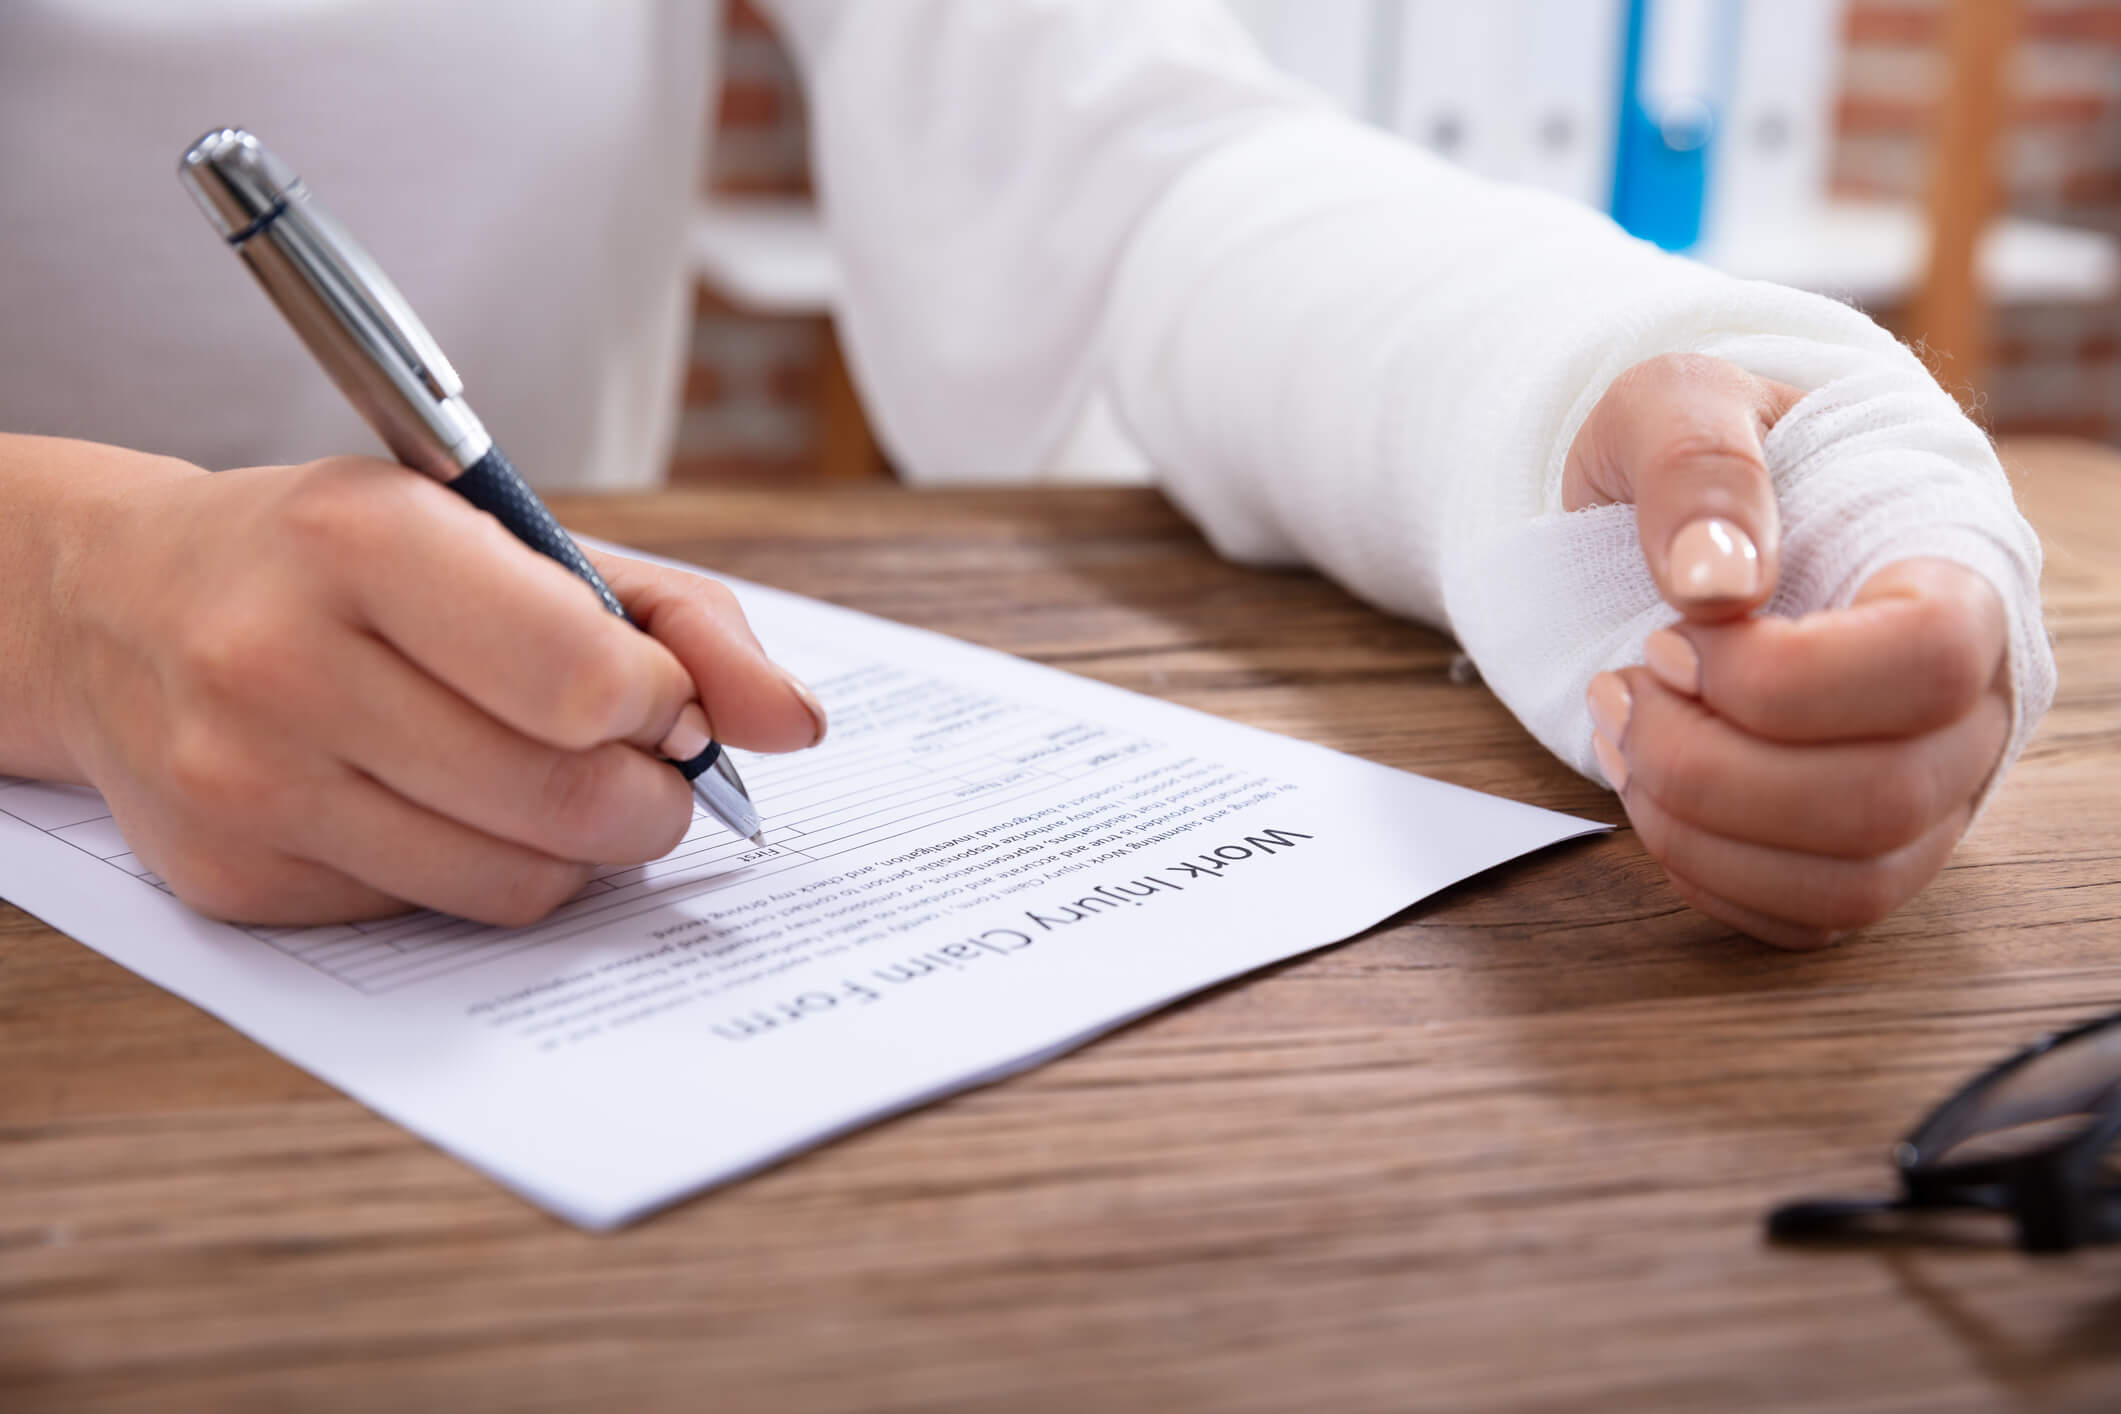
If your injury or illness developed gradually, report the condition as soon as you realize it is related to your employment. You must fill out a claim form for workers’ compensation immediately, because your employer is not obligated to give you benefits until you do so. You must keep a copy of the form. When your employer receives the form he or she is responsible for notifying your insurance company and taking care of your medical treatment. Follow up to ensure that your boss completes the claim for compensation.
4. Talk to a lawyer
An employee’s claim is only paid when the employer or their insurance company agrees that the injury or illness is a result of the work. If they dispute the claim, you do not receive benefits until a judge makes a decision. If you have any difficulties, or questions about your case, consult a lawyer immediately to make sure that you and your family do not go to work after a work-related accident.
Other things to keep in mind:
One does not have to be a legal resident of the country to receive the majority of workers’ compensation benefits
Your employer has to pay for your medical treatment
If your work injury was the fault of the negligence of a third party, such as a defective product or the driver of a truck, you may be able to file a “third party” lawsuit against the manufacturer of the product or company. transport. This is an independent process of labor compensation, which means that through a lawsuit you can receive compensation for “non-economic” damages, such as pain and suffering, which cannot be done through a claim of labor compensation.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing services to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks file, critical financial documents and back office tools in an efficient and secure environment. Complete Controller’s team of US based accounting professionals are certified QuickBooks™️ ProAdvisor’s providing bookkeeping, record storage, performance reporting and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay services. With flat rate service plans, Complete Controller is the most cost effective expert accounting solution for business, family office, trusts, and households of any size or complexity.
Essential Tips to Manage Household Finances Effectively
To manage household finances effectively, start by building a practical budget, tracking your expenses consistently, and making simple cuts to boost savings—all while aligning your spending with family goals and prioritizing peace of mind. The foundation of financial success lies in choosing a budgeting method that fits your lifestyle, whether that’s the 50/30/20 rule, envelope system, or zero-based budgeting approach.
As founder and CEO of Complete Controller for over 20 years, I’ve guided thousands of business owners and families through their financial journeys, watching them transform from stressed and overwhelmed to confident and in control. The stark reality is that Americans today save just 4.6% of their income compared to 10-13% in the 1980s, while 24% have zero emergency savings according to Bankrate’s 2025 report. In this guide, I’ll share the exact strategies our most successful clients use to reverse these trends, including how one couple eliminated $113,000 in debt in just 28 months, and how families are finding hundreds in hidden savings through simple expense audits.
How can you manage household finances effectively?
Build a tailored budget, track your spending, establish clear savings goals, engage the whole family, and review regularly
Choose a budget method that matches your habits: 50/30/20 for simplicity, envelope for cash control, or zero-based for maximum precision
Track every expense to expose the average $127 annually that households waste on unused subscriptions alone
Make finances a family affair with regular money talks and shared goals that keep everyone motivated
Schedule monthly reviews to catch problems early and adjust for life changes before they derail your progress
Choose Your Best Household Budgeting Method
The foundation of managing household finances starts with selecting a system that matches your lifestyle and natural habits. After two decades of helping families find financial freedom, I’ve seen that the best budget is the one you’ll actually stick with, not the most complicated spreadsheet.
Each budgeting method serves different personalities and situations. The 50/30/20 rule works brilliantly for busy families who need simplicity—allocate 50% of after-tax income to needs like housing and groceries, 30% to wants like entertainment, and 20% to savings or debt payoff. The envelope method physically separates cash into spending categories, making it impossible to overspend since you stop when the envelope is empty. Zero-based budgeting assigns every dollar a job before the month begins, with income minus expenses equaling exactly zero. Pay-yourself-first automation moves savings out immediately after each paycheck, treating it like a non-negotiable bill. Values-driven budgeting aligns spending with what matters most to your family, whether that’s education, travel, or health.
Setting up your chosen system requires four straightforward steps that form the backbone of household budgeting success:
Calculate your household’s net income after taxes and deductions
List every expense, both fixed and variable, for a complete picture
Implement your chosen budgeting framework using apps, spreadsheets, or paper
Review and adjust monthly to stay on track with expense tracking
Track Every Expense—And Uncover Surprising Savings
Knowing exactly where your money goes transforms vague financial anxiety into concrete opportunities for improvement. The Federal Reserve’s 2025 report shows that 37% of adults saw spending increase while only 32% saw income rise, making expense tracking more critical than ever for personal finance management.
Start by choosing a tracking method that fits seamlessly into your daily routine. Mobile apps like YNAB or Mint automate categorization, while spreadsheet enthusiasts can customize their own systems. Even a simple notebook works if you commit to recording every purchase. The key is consistency—track daily rather than trying to reconstruct a month’s spending from memory.
Categorize your spending into clear buckets: housing, transportation, food, utilities, subscriptions, entertainment, and miscellaneous. This breakdown reveals surprising patterns, like the fact that American households maintain an average of 2.8 paid subscriptions with 54.9% paying for at least one unused service monthly. That’s $10.57 per month or $127 annually literally wasted on forgotten streaming services, apps, or memberships.
Consider the Grant family’s transformation through diligent expense tracking. They discovered $150 monthly in unused gym memberships, streaming services, and app subscriptions, plus $120 in excessive dining out they hadn’t realized. By cutting these expenses and redirecting the $270 monthly into savings, they accumulated $3,240 in just one year—enough for a solid emergency fund starter. Their success came from simply writing down every expense for 30 days, then reviewing the list together to identify cuts that wouldn’t impact their quality of life.
Set Realistic Savings Goals—And Hit Them
Financial goal setting for families transforms wishful thinking into achieved milestones through structure and automation. The shocking reality that Americans save less than half what previous generations did makes intentional saving strategies essential for building security.
Short-term goals (3-12 months): Emergency fund starter, holiday spending, minor home repairs
Medium-term goals (1-5 years): Down payment, car replacement, major vacation
Apply SMART principles to each goal: Specific amounts, Measurable progress, Achievable targets based on income, Relevant to family values, and Time-bound deadlines. A goal to “save more” becomes “save $3,000 for emergency fund by December 31st through $250 monthly automatic transfers.”
Automation removes willpower from the equation. Set up automatic transfers from checking to savings the day after each paycheck arrives. Start with just $25 weekly if needed—that builds $1,300 annually without feeling the pinch. Gradually increase the amount every few months as you adjust to living on less.
Money management strategies for accelerating savings include the “pay raise trick” where you automatically save 50% of any income increase before lifestyle inflation kicks in. Also try the “52-week challenge” modified for your budget—save $1 the first week, $2 the second, building to $52 by year’s end for $1,378 total. These psychological tricks make saving feel like a game rather than deprivation, essential for tips for saving money at home.
Engage Your Whole Family for Lasting Results
Managing family expenses efficiently requires every household member to understand and participate in the financial plan. When families work together, they achieve goals faster while teaching children valuable money skills that last a lifetime.
Begin with age-appropriate involvement. Young children can help compare grocery prices and learn needs versus wants. Teenagers can manage a clothing budget or contribute to their car insurance through part-time work. Spouses must communicate openly about financial fears, goals, and spending triggers that derail budgets.
Regular family money meetings transform financial planning from a burden into shared responsibility. Schedule these monthly, keeping them brief and focused. Use visual aids like charts showing progress toward vacation savings or debt paydown. Celebrate wins together—when you hit a savings milestone, mark it with a special but budget-friendly family activity. This positive reinforcement makes everyone want to contribute more.
Create your household budget plan using tools the whole family can access and understand. A kitchen whiteboard showing weekly spending limits for groceries, gas, and entertainment keeps everyone aware. Shared apps let older kids see how their requests impact the family budget. Some families use colored envelopes or jars for different savings goals, making progress tangible and exciting. The key is transparency—when everyone sees the full picture, they make better individual choices that support family financial goals.
Combat Financial Surprises with Emergency Planning
Even meticulously planned budgets crumble without emergency reserves. The data is sobering: nearly one in four Americans have zero emergency savings, while only 46% could cover three months of expenses according to Bankrate’s 2025 survey. This leaves millions vulnerable to a single car repair or medical bill spiraling into debt.
Building an emergency fund starts with a achievable target. Aim for one month of essential expenses first—typically $2,000-3,000 for most families. Once achieved, expand to three months, then ultimately six months for solid protection. Calculate your target by adding only true necessities: housing, utilities, food, transportation, insurance, and minimum debt payments.
Make emergency savings non-negotiable by treating it like a bill. Set up an automatic transfer of even $10 weekly—that’s $520 annually toward security. Keep these funds in a separate high-yield savings account, reducing temptation while earning interest. Label the account “Emergency Fund” as a psychological barrier against raiding it for non-emergencies.
Over my 20 years running Complete Controller, I’ve weathered multiple recessions, family medical crises, and business challenges. Having that emergency cushion transformed each potential disaster into a manageable inconvenience. The peace of mind alone is worth every sacrifice to build these reserves. When clients tell me their emergency fund helped them leave a toxic job or handle unexpected medical bills without credit cards, I’m reminded why this unglamorous savings category matters most.
Advanced Money Management: Smart Tools and Habit Stacking
Technology and psychology combine to make good financial habits automatic rather than relying on daily willpower. The right tools paired with behavioral strategies create lasting change in personal finance management.
Modern expense tracking apps like YNAB (You Need A Budget) or Mint connect directly to bank accounts, categorizing spending automatically. Set up alerts for unusual charges or when spending approaches preset limits. Use calendar reminders for annual expenses like insurance or property taxes that derail budgets when forgotten. Enable automatic bill pay for fixed expenses, freeing mental energy for variable spending decisions.
Habit stacking leverages existing routines to build new financial behaviors:
Check bank balances while drinking morning coffee
Review weekly spending during Sunday meal prep
Update budget categories while watching evening TV
Discuss money goals during regular date nights
The key is linking new financial habits to established routines until they become automatic. Start with one simple stack, master it for 30 days, then add another. Within six months, comprehensive money management strategies become second nature rather than stressful obligations.
Track your credit score monthly through free services, celebrating improvements as a family achievement. Rising scores mean better loan rates, lower insurance costs, and increased financial opportunities. Make it visual—create a chart showing score progress to maintain momentum toward financial planning tips that truly transform family futures.
Where Most Budgets Fail—And How to Fix It Fast
Most budgets collapse not from lack of knowledge but from unrealistic expectations and unaddressed emotional triggers. Understanding common failure points helps you build a sustainable system.
Perfectionism kills more budgets than overspending. Expecting to follow a restrictive budget perfectly from day one sets you up for failure. Instead, aim for 80% compliance initially, improving gradually. When you overspend in one category, adjust others rather than abandoning the entire plan.
Serena and Jim’s story illustrates the power of persistence over perfection. Facing $55,000 in consumer debt with minimum payments barely covering interest, they felt hopeless. Working with a financial advisor, they increased income through side businesses and job changes while living on just $2,000-2,500 monthly. They used every tool available—balance transfers to 0% cards, strategic refinancing, even accepting family help. In 28 months, they paid off $113,000 total, with their income ranging from $68,000-98,000. Jim credits the process with saving their marriage, proving that financial transformation goes beyond numbers.
Address emotional spending by identifying triggers. Stress, boredom, social pressure, or childhood money messages often drive overspending. Keep a feelings journal alongside expense tracking to spot patterns. Replace retail therapy with free alternatives like walks, library visits, or calling friends. Build small rewards into your budget for meeting goals—sustainable plans include joy, not just restriction.
Final Thoughts: Move from Stress to Security—One Step at a Time
I’ve spent two decades watching families transform their financial futures through simple, consistent actions. You now have the exact blueprint our most successful clients use: choose a budgeting method, track expenses religiously, set automated savings goals, involve your whole family, build emergency reserves, and leverage tools that make good habits automatic.
Start today with just one step. Calculate your net income. Download an expense tracking app. Schedule your first family money meeting. Open that emergency fund savings account. Small actions compound into life-changing results when you maintain consistency over perfection.
Financial freedom isn’t about earning more—it’s about managing what you have with intention and wisdom. Every dollar you track, every subscription you cancel, every family member you involve moves you closer to the security and choices you deserve. Ready to accelerate your journey with expert guidance? Contact the Complete Controller team at Complete Controller for personalized strategies that fit your unique situation. Your future self will thank you for starting today.
Frequently Asked Questions About Managing Household Finances
How do I manage household finances when living paycheck to paycheck?
Start by tracking every expense for one month to identify any reducible spending, then build a micro-emergency fund of just $500 through small automatic transfers of $10-25 weekly, and use the envelope method for variable expenses to prevent overspending.
What’s the best app for managing household finances as a beginner?
Mint offers free automated expense tracking and budgeting, perfect for beginners, while YNAB (You Need A Budget) provides more detailed control with its zero-based budgeting approach, though it requires a subscription after the free trial.
How do I manage household finances with an irregular income?
Base your budget on your lowest typical monthly income, save surplus from higher-earning months in a separate account, prioritize essential expenses first, and maintain a larger emergency fund of 6-9 months versus the standard 3-6 months.
Should I pay off debt or save money first when managing household finances?
Build a starter emergency fund of $1,000 first to avoid new debt from surprises, then aggressively pay high-interest debt while making minimum payments on the rest, before returning to build your full 3-6 month emergency fund.
How can I manage household finances when my partner won’t participate?
Start by managing your personal spending and any accounts you control individually, share positive results without criticism to inspire interest, suggest starting with just one monthly 15-minute money check-in, and consider couples financial counseling if resistance continues.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Jennifer BrazerFounder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.
Why Hiring A Freelance Bookkeeper Boosts Your Business Success
A freelance bookkeeper handles your financial records, compliance, and cash flow management on a flexible, cost-effective basis, freeing you to focus on revenue-generating activities while gaining accurate insights for smarter business decisions. This professional partnership typically saves small business owners 10-15 hours monthly and delivers returns exceeding three times the service cost within the first year.
As CEO of Complete Controller for over two decades, I’ve watched countless entrepreneurs transform their businesses simply by stepping away from their QuickBooks screens. My team and I have guided thousands of SMEs through financial chaos, and here’s what I’ve learned: the difference between struggling businesses and scaling ones often comes down to who’s managing the books. Smart owners delegate numbers to focus on growth—and the data backs this up. With 1.57 billion freelancers now working globally and the freelance market projected to reach $16.89 billion by 2029, the professional bookkeeping talent available today can revolutionize how you run your business.
What does hiring a freelance bookkeeper actually do for your business?
A freelance bookkeeper manages your financial records, tax compliance, and cash flow on a flexible schedule that fits your budget and needs
They provide expert transaction categorization, bank reconciliation, and invoice management using professional tools like QuickBooks
Professional bookkeepers create accurate financial reports and forecasts that guide strategic decisions
They maximize tax deductions and prevent costly IRS penalties through meticulous record-keeping
Freelance services scale with your business growth without the overhead of full-time employment
Time Liberation: How Professional Bookkeeping Returns Your Most Valuable Asset
Small business owners typically invest 8-12 hours monthly on basic bookkeeping tasks, with complex businesses requiring up to 20 hours—that’s nearly a full work week every month spent on financial administration instead of business development. This time drain represents more than lost productivity; it’s a direct hit to your bottom line.
The real cost of DIY financial management
When you calculate the opportunity cost of handling your own books, the numbers become stark. A business owner earning $75 per hour who spends 15 hours monthly on bookkeeping sacrifices $13,500 annually in potential revenue-generating time. That calculation doesn’t include the stress of working evenings and weekends to catch up on reconciliations or the mental fatigue that comes from switching between strategic thinking and data entry.
The hidden time costs multiply when you factor in:
Learning and troubleshooting accounting software updates
Researching tax law changes and compliance requirements
Correcting errors that compound over multiple months
Preparing documentation for tax filing or financial reviews
Technology can’t replace professional judgment
Modern accounting platforms like QuickBooks Online and Xero have streamlined many bookkeeping processes, but automation has limits. Complex transactions still require human expertise—from allocating prepaid expenses to managing accrual adjustments. Even with sophisticated software, manual oversight consumes hours monthly for review, reconciliation of discrepancies, and exception handling.
Pro insight from my Complete Controller experience: One retail client discovered their “time-saving” accounting app had miscategorized $40,000 in inventory purchases as office supplies over six months. The cleanup took 30 hours and nearly triggered an audit. A professional bookkeeper would have caught this error immediately.
Financial Precision: The Foundation of Business Confidence
A freelance bookkeeper brings specialized expertise that prevents the costly mistakes plaguing 40% of small businesses that receive IRS penalties annually. Professional accuracy goes beyond avoiding fines—it creates the financial clarity needed for confident decision-making and sustainable growth.
Compliance without complications
Tax regulations change constantly, and missing updates can trigger significant penalties. The IRS can impose 20% accuracy-related penalties on businesses that underpay due to poor record-keeping. On a $20,000 understatement, that’s a $4,000 penalty plus interest—far exceeding annual bookkeeping costs.
Professional bookkeepers maintain:
Audit-ready documentation organized to IRS standards
Timely filing calendars that prevent late penalties
Expert bookkeepers don’t just record transactions—they identify opportunities. Through proper timing of expenses and comprehensive deduction tracking, professionals frequently save clients thousands during tax season. One study found businesses recover an average of $6,000 annually just by fixing common categorization errors and implementing proper systems.
Cash Flow Mastery: From Survival to Strategic Growth
Cash flow problems kill more businesses than lack of profitability, yet most entrepreneurs only discover shortfalls when it’s too late. A freelance bookkeeper monitors your financial pulse continuously, creating forecasts and budgets that prevent liquidity crises before they threaten operations.
Proactive financial monitoring
Professional bookkeepers track:
Accounts receivable aging to accelerate collections
Payment cycles optimizing vendor relationships
Seasonal fluctuations requiring cash reserves
Growth indicators signaling expansion readiness
Case Study Impact: A boutique retailer partnering with outsourced bookkeeping services improved cash visibility and reduced shortages by 40% within six months. The key? Weekly cash position reports that highlighted slow-moving inventory and collection opportunities the owner had missed while juggling daily operations.
Looking for bookkeeping support you can rely on? Explore Complete Controller.
Cost Efficiency: The Mathematics of Smart Outsourcing
Hiring a freelance bookkeeper costs 30-50% less than full-time employment while delivering superior expertise and flexibility. The financial comparison reveals overwhelming advantages for businesses seeking professional financial management without fixed overhead.
Breaking down the numbers
Cost Factor
Freelance Bookkeeper
Full-Time Employee
Annual Cost
$9,600-$14,400 (20 hrs/mo)
$60,000-$90,000+
Benefits & Taxes
None
$15,000-$25,000
Software & Equipment
Included
$2,000-$5,000
Training & Management
None
40-60 hours annually
Scalability
Instant adjustment
Hiring/firing complexity
Hidden savings multiply returns
Beyond direct cost comparisons, freelance bookkeeping eliminates:
Recruitment and onboarding expenses
Technology infrastructure investments
Management time for employee oversight
Costs of errors requiring professional cleanup
Research indicates businesses achieve 3x return on bookkeeping investment within twelve months through combined savings and recovered opportunity costs.
Scalability and Strategic Insights: Growing Without Growing Pains
As your business expands, a freelance bookkeeper adapts services instantly—from basic transaction recording to complex financial analysis. This flexibility proves invaluable for startups and growing firms facing unpredictable needs.
Customized solutions for every stage
Freelance bookkeepers offer:
Hourly arrangements for minimal needs
Monthly retainers providing predictable costs
Specialized expertise added as complexity grows
Seamless transition to larger firms when needed
From my Complete Controller portfolio: We helped a software startup scale from $200K to $1M revenue by identifying pricing inefficiencies and cash flow patterns invisible to the founder. The bookkeeper’s fresh perspective uncovered margin improvements worth $75,000 annually—paying for services many times over.
Selecting Your Ideal Freelance Bookkeeper: A Strategic Approach
Finding the right bookkeeping partner requires evaluating expertise, technology proficiency, and industry experience. Most top search results skip this critical implementation guidance, leaving business owners uncertain about the selection process.
Essential evaluation criteria
Prioritize candidates demonstrating:
Current certifications in QuickBooks or similar platforms
Specific experience in your industry vertical
Clear communication protocols and response times
References from businesses of similar size
Data security measures protecting sensitive information
Quick-start onboarding process
Share read-only access to existing financial accounts
Establish weekly check-ins for the first month
Define key performance indicators like monthly reporting dates
Review progress at 30 days and adjust scope as needed
Gradually expand responsibilities as trust builds
Conclusion
Hiring a freelance bookkeeper transforms your business through recovered time, enhanced accuracy, improved cash flow, cost efficiency, and scalable expertise that grows with your ambitions. After twenty years leading Complete Controller, I’ve witnessed this transformation countless times—business owners finally focusing on what they do best while professionals handle the numbers that make growth possible.
The data speaks clearly: professional bookkeeping delivers returns exceeding 300% while freeing up to 20 hours monthly for revenue generation. Your competitors who’ve already made this shift aren’t spending weekends reconciling accounts—they’re planning their next market move. Ready to join them? Visit Complete Controller to connect with our expert team and discover how professional freelance bookkeeping can accelerate your business success.
Frequently Asked Questions About Freelance Bookkeepers
What exactly does a freelance bookkeeper do for my business?
Freelance bookkeepers manage transaction recording, bank reconciliations, invoice processing, financial reporting, tax preparation support, and cash flow monitoring—all remotely using cloud-based tools, providing the same services as in-house staff at a fraction of the cost.
How much should I expect to pay a freelance bookkeeper?
Freelance bookkeepers typically charge $25-$50 hourly or $300-$900 monthly for retainer arrangements, depending on transaction volume and complexity—significantly less than the $60,000-$90,000 total cost of full-time employment.
Is a freelance bookkeeper better than hiring full-time for my small business?
For most small businesses, freelance bookkeepers offer superior value through cost savings of 50-70%, instant scalability, specialized expertise, and elimination of employment overhead while providing the same quality of service.
Will a freelance bookkeeper really save me time as a business owner?
Yes—business owners typically reclaim 10-15 hours monthly by outsourcing bookkeeping, time worth $6,000-$18,000 annually in opportunity costs that can be redirected toward growth activities and revenue generation.
How do I find a trustworthy freelance bookkeeper for my business?
Look for certified professionals with strong references, industry-specific experience, secure technology practices, and clear communication protocols—platforms like Upwork or specialized firms like Complete Controller pre-vet qualified candidates to simplify your search.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Jennifer BrazerFounder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.
When you have a better credit score, you are able to obtain loans with better terms and lower interest rate. You need a good credit score, it is necessary to borrow money for some personal reasons includes a car loan, credit card and a home loan etc. You can also purchase inventories and get the facility for the startup and growth of the business. Repairing a credit score is the major problem for the improvement of professional work. It only depends on the situation. However, if you do not have a good credit score, it is important to settle some of your debts to improve your credit score.
Here are four important steps that repair your credit score.
1. Review your credit report
You should review your credit reports. There are so many credit bureaus that are required to review your credit report. They can provide you a copy without any charges once a year. These credit bureaus include Experian, Equifax and TransUnion.
There is another way to check and review your credit report, Credit Karma. It is the free services that provide an accurate credit report. Only you have to sign up and make an account on that site. And then you can easily see your credit score and view all the information that is contained on your report. Somehow your entries might be same but not always. A credit report is rarely identical across all credit bureaus.
2. Pay your bills on time
Another way to repair your credit scores, to pay your bills on time. Moreover thirty-five percent of total credit scores are based on the payment history. The payment history shows your ability to make your payments on time. You will receive a payment notification on time once you paid your bills. In case, you receive late payment notification and potential insufficient funds (NFS) fees insufficient money in your account. Then your credit score will be affected adversely. So, it is important to pay your bills on time. You can also pay your bills in advance.
3. Lower your credit utilization ratio
The credit utilization ratio is considering thirty percent of your credit score. Credit utilization ratio is one of the most visualize financial term. It shows the revolving debt and availability of revolving credit. You can also calculate your total revolving debt by dividing your total available revolving debt. Many lenders borrow less than thirty percent of credit that is less risky. However, a credit utilization ratio of fifty percent is the lower threshold of the credit score. Hence, to work with forty-nine percent maximum credit utilization ratios repairs the credit score. It is mainly closer to thirty percent where you can get better control over credit score.
4. Close all your new credit cards
The last step to repair your credit score to close all your new credit cards. If you have a low credit utilization ratio than you can easily repair your credit score. If you have few credit cards then you can easily get a good credit score.
In this way, close your all new credit cards and keep your old cards. If you close your previous cards then you will definitely lose your payment history. You could also increase the limit on your credit cards. There are two important mechanisms in this step. The first one is to transfer all your account balance to the card with the longest payment history and the second is to avoid the temptation of shopping on credit.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing services to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks file, critical financial documents and back office tools in an efficient and secure environment. Complete Controller’s team of US based accounting professionals are certified QuickBooks™️ ProAdvisor’s providing bookkeeping, record storage, performance reporting and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay services. With flat rate service plans, Complete Controller is the most cost effective expert accounting solution for business, family office, trusts, and households of any size or complexity.
Unlocking Creative Management Benefits for Innovative Success
Creative management benefits include increased efficiency, adaptability, brand strength, employee satisfaction, and operational agility that drive measurable business growth and sustainable competitive advantage. These benefits transform organizations by streamlining workflows, reducing administrative burden on creative teams by up to 35%, and delivering tangible ROI through improved project execution and resource optimization.
Leading Complete Controller for over two decades has taught me that businesses either innovate or stagnate—there’s rarely middle ground. I’ve watched countless companies struggle with creative bottlenecks, burned-out teams, and missed opportunities while their competitors soared past them. The difference? Strategic creative management that balances innovation with operational excellence. This article reveals the five core benefits of creative management, practical implementation strategies that actually work, and real-world examples of companies achieving 10X growth through structured creative frameworks. You’ll discover how to reclaim your team’s creative time, boost engagement by 23%, and build a culture where innovation thrives alongside profitability.
What are creative management benefits and how do they unlock innovative success?
Creative management benefits include increased efficiency, adaptability, brand strength, employee satisfaction, and operational agility
Efficiency gains manifest through streamlined workflows that eliminate bottlenecks and reduce non-creative tasks by 35%
Adaptability improvements help organizations pivot quickly during market changes and technological disruptions
Brand strength develops through consistent messaging and unified creative vision across all channels
Employee satisfaction increases through recognition programs, flexible work arrangements, and creative autonomy
The Core Creative Management Benefits Every Business Needs
Creative management transforms chaotic creative processes into strategic business assets that consistently deliver results. According to Monotype’s 2025 research, 57% of creative teams waste more than a quarter of their time on non-creative administrative tasks—a staggering productivity drain that creative management directly addresses.
The most successful organizations implement structured frameworks that balance creative freedom with operational discipline. These frameworks create clear pathways for ideas to move from concept to execution while maintaining quality standards and brand consistency. Companies with dedicated creative operations roles rate themselves as 88% effective at balancing creativity with business needs, compared to just 45% for those without structured approaches.
Key efficiency improvements include:
Automated workflow systems that reduce project turnaround times by 40%
Centralized asset management that eliminates version control issues
Standardized approval processes that cut review cycles from weeks to days
Resource allocation tools that match talent to projects strategically
Performance dashboards that track ROI on creative investments
Cross-department collaboration accelerates when creative management breaks down traditional silos. Marketing, sales, product development, and customer service teams align around shared creative assets and messaging, multiplying the impact of every creative initiative. This integrated approach produces campaigns that resonate across touchpoints and drive consistent brand experiences.
Building Sustainable Competitive Advantage Through Creative Excellence
Organizations that master creative management build moats their competitors struggle to cross. Strong brand identity emerges naturally when creative teams have clear guidelines, adequate resources, and strategic direction. Customers recognize and trust brands that communicate consistently, whether through social media, packaging, or customer service interactions.
Employee engagement skyrockets when creative professionals feel valued and empowered. Gallup’s analysis of 2.7 million employees found that highly engaged teams drive 23% higher profitability and experience 43% lower turnover in low-turnover organizations. Creative management directly impacts these metrics by providing clear career paths, recognition for innovative work, and tools that eliminate frustrating bottlenecks.
Innovation cycles compress dramatically under effective creative management. Instead of months-long development processes plagued by miscommunication and rework, teams launch new concepts in weeks. This speed advantage proves crucial in fast-moving markets where first-movers capture disproportionate market share. Companies leveraging agile creative methodologies report 30% increased efficiency and 65% improved financial performance according to McKinsey research.
Real-World Impact: Strategic Creative Management at Scale
Imperfect Foods faced a critical challenge in 2021: their small internal creative team couldn’t match the content velocity needed for explosive growth. Partnering with Superside’s creative operations platform transformed their capabilities overnight. The company submitted 168 creative projects that year, primarily motion graphics their internal team lacked bandwidth to produce.
By implementing templating strategies and structured workflows, Imperfect Foods increased design capacity by 10X while saving $250,000 in production costs. Their TikTok campaigns achieved remarkable results: 25% lower customer acquisition costs compared to other channels, 47% stronger click-through rates, and 50% improved conversion rates when paired with strategic partnerships. This case study demonstrates how creative management multiplies both output and outcomes.
Building Creative Culture That Drives Results
Leadership commitment forms the foundation of successful creative management. Leaders who champion experimentation, celebrate calculated risks, and invest in creative infrastructure see returns that extend far beyond individual projects. These leaders understand that creativity requires both structure and freedom—seemingly opposite forces that creative management reconciles.
Diverse teams produce stronger creative outcomes by bringing varied perspectives to every challenge. Cross-functional collaboration becomes natural when creative management systems facilitate easy communication and resource sharing. Marketing insights inform product design, customer feedback shapes messaging, and operational constraints inspire innovative solutions.
Modern creative management relies on technology platforms that unify teams, projects, and resources. These tools eliminate the friction that kills creativity: lost files, unclear feedback, missed deadlines, and resource conflicts. The right technology stack transforms creative chaos into orchestrated innovation.
Essential creative management tools include:
Project management platforms with creative-specific features
Digital asset management systems with intelligent tagging
Collaborative review and approval workflows
Resource planning and capacity management tools
Analytics dashboards that connect creative work to business outcomes
The Human Side of Creative Management Excellence
Burnout devastates creative teams, yet many organizations ignore warning signs until top talent leaves. Research shows burnout symptoms are 15% lower among hybrid workers, with 82% reporting greater happiness and motivation with flexible arrangements. Creative management must prioritize human sustainability alongside business outcomes.
Smart organizations implement flexible working options that respect creative rhythms. Some people produce their best work at dawn, others at midnight. Some need silence, others thrive in collaboration. Creative management accommodates these differences through policies that value outcomes over hours logged.
Recognition programs specifically designed for creative contributions dramatically impact retention. Well-recognized employees are 45% less likely to leave after two years, and companies with strong recognition programs see 31% lower overall turnover. Creative management builds recognition into daily operations, not just annual reviews.
Effective wellbeing initiatives include:
Flexible hours that accommodate creative workflows
Mental health resources specifically for creative professionals
Sabbatical programs for long-term creative renewal
Learning budgets for skill development and inspiration
Collaborative spaces designed for both focus and interaction
Your Blueprint for Creative Management Success
Start by auditing your current creative workflows to identify friction points. Map how ideas move from concept to completion, noting every handoff, approval, and revision cycle. This baseline assessment reveals opportunities for immediate improvement and helps prioritize technology investments.
Invest strategically in technology that addresses your specific bottlenecks. Generic project management tools rarely serve creative teams well—look for platforms designed specifically for creative workflows. The right tools pay for themselves through time savings and improved output quality within months.
Launch recognition programs that celebrate both creative excellence and operational efficiency. Creative management succeeds when teams understand that innovation and execution deserve equal praise. Public recognition, career advancement opportunities, and performance bonuses aligned with creative metrics drive sustained engagement.
Foster diverse team cultures through intentional hiring and development practices. Creative management thrives when different perspectives collide productively. Build teams that balance creative visionaries with operational experts, risk-takers with quality guardians, and specialists with generalists.
Measure outcomes consistently using metrics that matter. Track project velocity, resource utilization, employee satisfaction, and creative ROI. Regular measurement reveals what works, what doesn’t, and where to focus improvement efforts. Successful creative management evolves based on data, not assumptions.
Final Thoughts
Two decades building Complete Controller taught me that creative management separates thriving businesses from those merely surviving. The data proves what I’ve witnessed firsthand: structured creative management delivers 35% time savings, 23% profitability increases, and dramatic improvements in employee satisfaction and retention.
Your creative team holds untapped potential that proper management unlocks. By implementing the strategies outlined here—from workflow optimization to wellbeing initiatives—you’ll build an organization where innovation becomes predictable, not accidental. The companies winning tomorrow are investing in creative management today. Don’t let your competition get there first. Connect with our team at Complete Controller to discover how expert financial and operational guidance can amplify your creative management success.
Frequently Asked Questions About Creative Management Benefits
What specific metrics should I track to measure creative management ROI?
Track project completion times, resource utilization rates, employee satisfaction scores, creative asset reuse percentages, and revenue attributed to creative campaigns. Leading organizations also measure time saved on administrative tasks and client satisfaction ratings.
How long does it take to see results from implementing creative management systems?
Initial improvements in workflow efficiency typically appear within 30-60 days. Significant cultural shifts and measurable ROI generally emerge after 3-6 months of consistent implementation. Full transformation often requires 12-18 months.
What’s the difference between creative management and project management?
Creative management specifically addresses the unique challenges of creative work: subjective feedback, iterative processes, inspiration timing, and portfolio diversity. While project management focuses on timelines and deliverables, creative management balances artistic excellence with business objectives.
How can small businesses implement creative management without large budgets?
Start with free or low-cost tools, focus on process documentation, establish clear creative briefs, and implement simple recognition programs. Many creative management principles cost nothing to implement—they simply require commitment and consistency.
What are the biggest mistakes companies make when implementing creative management?
Over-controlling creative processes, ignoring team feedback, choosing generic tools over creative-specific solutions, measuring only efficiency without quality, and expecting overnight transformation instead of gradual improvement.
StreamWork. “What Is Creative Process Management?” 2024.
Superside. “9 Benefits to Expect From a Creative Services Partner.” 2024.
Superside. “How Imperfect Foods Fuels Growth With a Dedicated Creative Team.” Case Study.
TikTok for Business. “Imperfect Foods Case Study: Optimizing New Customer Signups With an Evergreen Strategy.”
Yarooms. “41% of Employees Would Quit Without Hybrid Work: A Retention Crisis.” 2024.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Jennifer BrazerFounder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.
Sustainability is becoming an integral part of any organization’s success. The business environment and industry trends are changing more and more rapidly. Industries are getting more volatile, complex and unpredictable. The business environment has had to evolve in order to deal with these complexities and rapidity of change. The North American market in particular is moving towards environmentally friendly or green activities to appeal to the more informed customer base. However, this trend is not only noticeable here in North America but has spread out to other regions around the world such as Europe, Japan and Australia. The subject of the environment and our global ecosystem has been a topic of hot debate for a few decades and the green initiative is a result of these ongoing concerns that are yet to be regulated and or corrected. This article looks at the advantages of using a green model for upcoming and established businesses and the associated political and economic issues.
The green initiative therefore has taken off but interestingly the most successful businesses adopting this green model have not found success through simply advertising themselves as a greener alternative to existing products. Rather these businesses have come up with innovative solutions to be either cheaper, more efficient or produce better quality products while at the same time being more environmentally friendly. Only a small percentage of consumers are likely to pay a higher price for a product that is better for the environment than one which is not. However, a larger proportion of consumers are likely to purchase a product that provides them with greater performance while being of comparable value and at the same time have positive environmental factors associated with it.
There are several advantages for companies adopting a green model for their business practices, a trend that has been increasingly growing in recent years. There are several legal and tax advantages for using equipment that produce low emissions especially in states such as California. Businesses using renewable forms of energy generation are given subsidiary grants as well as tax credits which help reduce overall cost of operations. Adopting a green model can lead to greater efficiency and less waste of resources. It also helps improve the work environment as only using organic and scent free products help employees who suffer from respiratory and other health related conditions. A company associating itself with green practices also generally has a much better public response which adds to the sustainability and credibility of the business.
The introduction of the triple bottom line to public sector full cost accounting has also brought about a different outlook to whether businesses are indeed socially beneficial. A business may be profitable but if it is causing considerable social and environmental damage it would reflect a different bottom line. Profitability is no longer the only measure of a business’s success. Most investors and business owners realize the importance of having a positive public image. Manufacturing and selling products that are less harmful to the environment shows that a business cares about more than just profitability. This is a growing market trend and many stakeholders today agree that the value of a business lies in three core factors; profitability, society and environment. Thus, a true measure of a business’s success depends upon a positive profitable outlook along with positive social and environmental benefits.
The economy and market trends in North America are currently leading towards sustainable business. This is encouraging as knowledge becomes more readily available such ideologies can be studied and implemented in other countries around the world. With depleting resources and an even increasing population it is important that we conserve our planet’s resources and ecosystem for our future generations. Without sustainable business this cannot be achieved. The North American economy is on the right track but still a lot of work is to be done to repair the damage that has already been caused to the environment due to humanities negligence. The term “going green” is already becoming saturated because of so many companies claiming to be more environmentally proactive in different areas of business. However, this is a good trend but needs to be regulated to ensure that these corrective practices are in fact taking place and the positive measurable outcome is favorable to all stakeholders.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing services to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks file, critical financial documents and back office tools in an efficient and secure environment. Complete Controller’s team of US based accounting professionals are certified QuickBooks™️ ProAdvisor’s providing bookkeeping, record storage, performance reporting and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay services. With flat rate service plans, Complete Controller is the most cost effective expert accounting solution for business, family office, trusts, and households of any size or complexity.
Everyone wishes to have a decent job that helps pay the expenses and manage a decent life without having to worry. People spent years wondering and exploring the right profession for themselves; one that helps bring in the bacon and is of interest to them. Who doesn’t love a stable job? After all, half our lifetime is spent studying, whining for grades, and competing with millions of others in the job market, and demands a result in the form of a stable job. Let’s explore the advantages of a stable job!
Management of Expenses
People are always worried about payments and expenses! Some people work two shifts to provide for their families and some are still unable to even though they work tirelessly. A stable job means that one has a clear idea of the monthly earning; therefore, knows the resources available for the month. The employee knows how much can be spent, how much needs to be saved for the next month, how to manage the year-end payments, and more. There is a constant pattern of earnings which allows one to manage the expenses accordingly. If savings and expenses are balanced well, one can effortlessly deal with unexpected situations such as a sudden party!
Lesser Stress, More Fun!
Having a stable job means that one is doing well in fulfilling the basic needs of life, providing for the family, and is satisfied with the work. On the contrary, an unstable job lays pressure on the employee to vigorously look for another job, adds to the frustration, and deteriorates the health of the employee. Several studies have proven that financial constraints lead to anxiety and depression while work stress is known to be the major reason for depression. A stable job allows one to enjoy life, spend time with his family and friends, experience adventures, and live life to the utmost, without worrying about money.
More Employee Benefits
People who add value add to the company with their skills, hard work, and enthusiasm; their worth in the organizations grows exponentially. Employees who enjoy stability in their job are the ones who have positively contributed towards the profitability of the company and are valued in the organization. Such employees are likely to receive more benefits like paid holidays, salary increments, annual bonuses and appraisals at their jobs. Since they have developed a credibility in the organization, they are not micro-managed. The company is lenient towards them just in case they get late to work or don’t show up on one of the days.
Opportunity to Take Investment Risks
A person is able to take risks and explore different opportunities when he is sufficiently meeting the basic needs of life. A stable job interprets that one is doing well with the expenses and needs of life, and is most likely to have some money in the form of savings. Such individuals are able to invest in different short-term and long-term projects to increase the sources of earnings. Some investment opportunities include starting a business of interest like a small café, buying stocks, investing in an on-going project or more. However, one must take calculated risks and carefully invest the hard-earned money!
Opportunities for Professional Growth
Stability in a job is achieved through professional excellence. Employees are stable in a job when they have performed well, have tirelessly worked to deliver their best performance and have added value to the company. Such employees have a competitive edge over others and have more opportunities for professional growth within and outside the company. Their current employer wouldn’t want to let them go while other employers would like to welcome them into their company. This gives employees a leverage to choose from a range of opportunities and diversify their skills by exploring new roles.
A stable job offers peace of mind and provides a stress-free life in terms of finances. It allows one to experiment with different things, take calculated risks, and enjoy life to the utmost without any pressure!
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing services to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks file, critical financial documents and back office tools in an efficient and secure environment. Complete Controller’s team of US based accounting professionals are certified QuickBooks™️ ProAdvisor’s providing bookkeeping, record storage, performance reporting and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay services. With flat rate service plans, Complete Controller is the most cost effective expert accounting solution for business, family office, trusts, and households of any size or complexity.
Controlling the stock of your restaurant today is a must if you do not want to lose money. Can you imagine a textile business that does not know how many garments it has sold? Or what is worse, that not knowing how much it cost them to make them, do they sell them too cheap?
It is unthinkable that these companies work without knowing the manufacturing cost and the value of the products; however, in a restaurant quite often the control of food and beverages does not follow any order.
If you invest too much money but this is not reflected in your profits, you have customers but the accounts still do not leave, you spend more and more time but it seems to be not enough … it’s time to think if you are managing correctly.
I invite you to ask yourself these questions:
Do you know exactly what products are in your restaurant?
Is there someone in charge of making and reviewing the inventory?
Do you control the costs of your restaurant?
Are there specific dates assigned to take inventory?
Do you check one by one the products you receive from your suppliers?
Do you know what your best selling products are? And the least sold?
Do you know the system “first in first out” (the first to enter is the first to leave)?
Do you always have the necessary products, preventing them from running out?
If in any of these questions your answer has been NO, you have to know that you must improve in the control of food and beverages.
What is stock control and why is it going to help you not lose money in your restaurant? Stock control consists of knowing what foods and beverages we have in our restaurant at a certain time.
To carry out a correct management, we will do what is known as inventory; a detailed list where we will write:
Items that we have in stock.
Quantity of each of them.
Provider
Detailed description.
The purchase of food and beverages is one of the most important expenses for restaurants, so you must have inventory control policies: specific dates to do so, periodic reviews and why not, surprise inventories to avoid theft.
How stock control will reduce your expenses in your restaurant.
You can make smarter decisions to reduce costs .
Your profitability will increase , since you will avoid losing money.
You will know what your sales have been and you can create strategies to increase them.
You will save time that you can invest in other aspects of your restaurant.
You will decide what and how much to order without accumulating and losing money.
You will know which are the most profitable items to design the menu that includes them.
You will know which genre is going to expire soon and you should use it.
You will see the evolution of prices of products and you can decide on your suppliers.
You will improve the way you order products.
You will avoid theft or loss of raw materials due to lack of control.
You will always have a minimum and a maximum so that nothing runs out.
You can reduce the level of waste.
And of course, you will save a large amount of money.
As you see, just a tool like inventory can save you money and resources, which are sure to be welcome to favor other areas of your business.
If you have decided to improve the management of your restaurant and want to continue increasing your profits. I invite you to review our Restaurant Management Course, because we teach you everything you need to know to make your business profitable, through videos and success stories.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing services to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks file, critical financial documents and back office tools in an efficient and secure environment. Complete Controller’s team of US based accounting professionals are certified QuickBooks™️ ProAdvisor’s providing bookkeeping, record storage, performance reporting and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay services. With flat rate service plans, Complete Controller is the most cost effective expert accounting solution for business, family office, trusts, and households of any size or complexity.
If you have time in the market and you still cannot get your business to achieve the success you’ve always dreamed of, it may be because you’re not using the right finance strategies.
There are many factors that can positively or negatively influence this. One of them is the ability to manage money in the right way, getting to be economically independent, but without bankrupting everything that you have fought so hard for.
If you find you have financial issues and you do not know which the best option, stay here and keep reading this post, we will show you some little used but very useful strategies to have the best support of all in your venture.
What are the best finance strategies for your venture?
These strategies that we are going to show you below are not used because only companies of great size and status use them, they tend to go unnoticed since there are others that are much easier to carry out. But today we are going to teach you how to execute them so that you can take them your venture to the top.
1. Analyze the needs of the company to draw up an action plan
Many of the big players in the market believe that this step is the first and most important in any functional financial strategy, regardless of the time that has been stipulated to achieve them.
Plan step by step everything that must be done to reach a specific goal requires time, knowledge and a lot of patience, these plans must be organized and very well detailed in a personalized way, where you can clarify how to meet the needs and objectives of your enterprise.
2. Design the strategies according to the term in which you want to reach a goal
The time frame is one of the main keys in a strategy to make it work, especially if you plan to opt for long-term goals, which are the most recommended because they are the most durable, but for this it is necessary to take into account 3 aspects of importance:
The Investment: must be oriented to increase the value of your company, the tactics can be defensive, offensive, reoriented or survival. Depending on the plans you have made, you can choose between these two types of growth:
Internal growth: that is to expand the business because the demands have increased by a considerable percentage, and the offers are no longer enough to cover them.
External growth: a clear example of this type of growth is to eliminate competitors through various mergers.
Regarding disinvestment, it does not affect, since this strategy is applied only when your objectives are focused on getting ahead.
3. Short-term functional strategies
Surely after all the information we gave you before you have doubts about whether it is possible or not to create a short-term financial strategy, and the truth is that if possible, as long as these are focused on the following points:
Work Capital: One of your priorities is to find a stable relationship between risk and performance. For this you must adjust to some kind of strategy, be it conservative, aggressive or intermediate.
Circulating Liability: this is a common financing of any company, large or small, the ideal is to take advantage of the discounts for prompt payment instead of going to financial institutions to make a credit application.
Efficient Cash: a good way to increase the liquidity of your venture is to reduce inventory, delay payments in case of commission and resignation, and seek to make the collections as soon as possible.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing services to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks file, critical financial documents and back office tools in an efficient and secure environment. Complete Controller’s team of US based accounting professionals are certified QuickBooks™️ ProAdvisor’s providing bookkeeping, record storage, performance reporting and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay services. With flat rate service plans, Complete Controller is the most cost effective expert accounting solution for business, family office, trusts, and households of any size or complexity.
Before starting a project, the entrepreneur must make a business plan. But what is the best way to do this, especially for those who do not have experience?
The first step is to understand that there are no magic formulas. Employers with little experience should have a business plan as a priority.
Making a simple business plan is ideal
To reduce the chances of errors when it comes to making a business plan, according to the specialist, it is necessary to start with a simple, clear and easy to implement plan. Later on, you will have time and find you have the need to perfect it, especially at the beginning you must go out to sell, sell and sell some more.
Minimize mistakes, especially for less experienced entrepreneurs, is the goal. One of these, quite common, is to build the business plan based on assumptions or information only from the environment that surrounds them. Overestimating their own abilities is also a very common mistake, and entrepreneurs must be careful not to fall into that trap.
Learn 3 tips to build the business plan
To avoid making mistakes when making a business plan, it is worth paying attention to some points. Learn below three tips to consider and avoid future headaches.
Be realistic
Especially if you have experience as an employee in a large company, you can have the expectation that things happen fast.
It is necessary to have peace of mind and patience, especially in what can be done with the available finances.
Investigate the market in its entirety
References such as the size of the market, the expectation of growth of the sector, how to gain space in that market, among others, should be in the plan. Therefore, the entrepreneur has to investigate everything about the sector he intends to enter. Other external factors, such as the place of installation and acceptance rate among the public in the region, also need to be considered.
Prepare to take risks
No matter how bright an idea or more promising the market is, every entrepreneur will take risks when starting a venture, because there is no guarantee that future achievements will compensate the expenses, money and time invested.
Therefore, the business plan should not avoid them, but consider the best way to handle them.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing services to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks file, critical financial documents and back office tools in an efficient and secure environment. Complete Controller’s team of US based accounting professionals are certified QuickBooks™️ ProAdvisor’s providing bookkeeping, record storage, performance reporting and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay services. With flat rate service plans, Complete Controller is the most cost effective expert accounting solution for business, family office, trusts, and households of any size or complexity.