Every sector in this world is under the strong influence of technology. The tech-boom has made things easy and convenient for all, specifically for aspiring entrepreneurs. The advent of eCommerce led to an increase in the number of online businesses, which are much easier to manage than traditional brick-and-mortar stores. Not just for aspiring business owners, but technological innovations also make things easy for already existing businesses.
Setting up a business has become less stressful than it used to be, but even managing the operations ofa business is less of a challenge. Advances in mobile technology have brought us some amazing applications which make running a business simple and easy. Here are the top four business management apps that will help you take your company to the top.
Google Analytics App – Keeping Track of Digital Success
The era that we live in is powered by technology. We are now in the middle of a transition to a digital world. The transition has made it mandatory for all businesses to establish a powerful digital presence. Being new in the digital world, not many entrepreneurs know how to manage things. This instance is where the Google Analytics App comes into play.
It is one of the most effective ways to track the performance of a business website. It is available for both iOS and Android smartphones. It lets the users track the most important factors that are critical for a website’s digital success. It offers real-time data acquisition and lets business owners understand customer behavior through conversion rates.
It lets you manage the digital performance of your website without the need to possess expertise in the field.
Voice Text – Managing Tasks and Ideas
The next app that is helping business owners like you efficiently manage their setups is Voice Text. Running a business is not easy, and many tasks need to be handled all at once, making it difficult to keep track of all the tasks at hand and the ideas that need implementation. It becomes even more of a challenge when you are always traveling.
An app coming to the rescue is Voice Text. It lets you manage the tasks at hand with ease, that too remotely. It converts speech into text, which saves time and makes it simple to keep track of all the ideas that come to mind when away from their workstation.
It is a smart app and can automatically correct grammar, enhancing precision with time. Whether it’s an idea or a long email, you do not need a notepad to write it down or type. You have to dictate it to the app, and the rest is handled.
Asana – The Perfect Project Management Tool
There is a multitude of tasks that need to be handled when it comes to managing projects. Business owners hire professional project managers, which is sometimes not an affordable solution. Addressing this issue, specifically for small businesses, is Asana. The app is available for iOS, Android, and desktop devices.
Making this app a part of your business management strategy can help you save money and even keep the entire team organized while keeping all their tasks manageable. It lets users create new projects with dates (starting and due dates), sub-tasks, along with a notification and email functionality. It keeps a manager or an entrepreneur well-informed about the progress of the project.
WebEx – Staying Connected with Remote Employees
The concept of remote employees has made its way into the corporate sector. The outbreak of COVID-19 has pushed many companies to adopt this practice. The concept of remote working is beneficial for small businesses and for those who are operating virtual setups. While remote working does have a bright side, it sometimes makes it difficult to hold meetings and manage teams.
WebEx is an app that is dedicated to this purpose. It solves the team management issues for companies. You can keep your entire team connected through this efficient video conferencing app. It will also help you share files and send messages to keep all the members in a manageable network.
These are the top four apps that entrepreneurs frequently choose as these make the management of business-related tasks manageable. With these platforms, a business owner can work on its growth strategy as these business management apps help in reducing the stress involved in managing the teams and all the tasks.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Many families do not know that, through the lease, they could acquire their housing project. Learn how this system works. Buying a home is a dream for most people, but sometimes that dream ends up being a nightmare when you do not have enough resources. How long do you think it would take you to buy the house of your dreams?
Finances and the household economy are fundamental issues in Colombian families
We are always reviewing possibilities to make our salary more flexible, lasting, and profitable. Between paying for services, the market, the children’s school, and the lease, the possibility of thinking about buying a home as we imagine it vanishes.
But there is an alternative that will allow you to access this great dream: buy a home and pay it with the money that goes to the lease. This type of investment takes more and more strength as it is the best option to finance a project and optimize the family’s finances.
How to pay with the rent money?
The National Savings Fund (FNA) has the Save your lease program for people affiliated with layoffs * with incomes from 2 to 6 SMMLV (Legal Minimum Monthly Salary Effective), and even a program option for income over 6 SMMLV.
There are two ways to access this program: you are affiliated to the FNA under the modality of unemployment or voluntary savings. If you do not have your severance payments in the FNA, you can request the transfer to take advantage of all the benefits) or that you have or create a Contractual Voluntary Savings (AVC) account in said
That way, you can buy social interest housing, new or used, and finance it for up to 20 years. You do not need an initial fee because the objective is to convert tenants into owners, providing all facilities.
It is important to know that the beneficiaries are people affiliated with the fund either through the deposit of severance payments or the opening of a Contractual Voluntary Savings (AVC) account. Both are equally important and must be done at the same time.
To access the program, you must meet the following requirements:
According to your monthly income, the FNA has arranged three lines: people who earn up to 2 SMMLV, between 2 and 6 or more than 6 SMMLV. Find out which of these three groups you are in to know what type of home you can access: new, used, social interest, or priority social interest. Remember that you must be affiliated with the National Savings Fund under the modality of unemployment or voluntary savings.
Collect the documents according to your profile: employee, pensioner, independent, etc.
Fill out the application form and go to one of the 77 points of attention of the FNA to file your application.
In addition to the FNA, you can also find housing leasing programs in financial institutions, which will help you access your own home.
How to finance a rental property investment
When you decide to invest in rental property, the first question that comes to your mind is which one investment should be the best. These three options can help you in maximizing rental property investment.
Usual house mortgage
Typically, people prefer this way of finance for rental property investment. You will start it with a secured mortgage through the rental property’s equity that you are purchase. It will be the mortgage that you have to purchase a house in which you are living. You may have to pay a higher amount for rental property investment, need greater down payments, and multiple approval requirements. That payment will be greater than the property that the owners had purchased.
HomePath financing property investment
We can avail of this option of HomePath financing property investment for Fannie Mae-owned properties. For this, you will need hardly 5% of down payment, expanded seller contributions, lack of mortgage insurance, and higher financing to repair the damage. Investors may receive investment property finance for up to 20 properties for Fannie-owned properties. Each borrower can get loans for only four financed properties.
Line of credit for a home equity
You can take a loan for a rental property investment if you are using your home. If you are new in this field of investment, you can use your existing house as a down payment with the help of a secured line of credit for the first or second investment property. Now, the question is, what is a secured line of credit or HELOC? The equity in the house you are living in secure your line of credit, and HELOC is a Home Equity Line Of Credit.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Personal Finance Basics: Everything You Need To Know
Personal finance basics are the essential money skills—budgeting, saving, managing debt, building credit, and basic investing—that help you cover today’s needs while steadily building wealth for tomorrow. When you understand these fundamentals and apply them with consistency, you can sidestep high-interest debt, weather emergencies without panic, grow your net worth, and make smart money choices at every season of life.
Here’s something that stops me in my tracks every time I think about it: roughly 36% of U.S. adults said they couldn’t cover a $400 emergency with cash or savings, according to the Federal Reserve’s 2024 report. After more than 20 years leadingComplete Controller and partnering with thousands of households and small business owners across nearly every industry you can name, I can tell you the fix isn’t complicated—it’s a clear order of operations. In this guide, I’ll walk you through the same framework I use with my own family and our clients, so you can stop feeling behind, build real confidence, and design a money system that actually works on your busiest days.
What are personal finance basics and how do you get them right?
Personal finance basics are the habits of budgeting, saving, managing debt, building credit, protecting against emergencies, and investing in a simple, step-by-step order.
Start with financial goal setting and a clear picture of your income, expenses, debts, and assets.
Build a budget and cash flow management plan—often the 50/30/20 rule—so you consistently spend less than you earn.
Prioritize an emergency fund, high-interest debt payoff, and retirement contributions before advanced investing.
Protect your progress by building a strong credit score, avoiding unnecessary debt, and automating savings.
The Foundation of Personal Finance Basics: Know Where You Stand
Personal finance starts with knowing your snapshot—your income, expenses, assets, debts, and goals—before you optimize anything. You can’t steer a ship if you don’t know where it’s docked, and the same is true with money. Most people skip this step and wonder why their budget keeps falling apart.
Financial goal setting: From vague wishes to concrete targets
Clear goals (like “save $10,000 for a down payment in 3 years”) give your money a job and shape every budgeting decision you make.
Short-term: emergency fund, paying off a credit card
Medium-term: car replacement, small business launch
Long-term: retirement, college savings, mortgage payoff
Real control comes from aligning your money with what matters most—security, flexibility, family, freedom—not chasing arbitrary numbers.
The four pillars of your personal balance sheet
Everyone’s finances rest on four pillars: assets, debts, income, and expenses. Compare them, and you get net worth and cash flow health. Net worth (total assets minus liabilities) is your true financial scoreboard, and tracking it monthly shows whether your decisions build or erode wealth. For a deeper dive into staying ahead of cash flow, our team shares practical tips in 5 Money Management Tips to Help Avoid a Deficit.
Budgeting Basics: Turning Your Paycheck Into a Plan
Budgeting is the heartbeat of personal finance basics because every other decision—saving, debt payoff, investing—depends on intentional control over your cash. Most budgets fail because they’re too rigid, too detailed, and ignore real life. The goal isn’t perfection; it’s a plan you’ll actually stick with.
The 50/30/20 budgeting rule for beginners
The 50/30/20 rule is the cleanest framework I recommend for beginners:
If you’re in a high cost-of-living area, start with 60/20/20 and shift toward 50/30/20 as your income grows.
Cash flow management and automation
Automation is the secret weapon. Behavioral economists Richard Thaler and Shlomo Benartzi found that in their famous “Save More Tomorrow” study, participants’ savings rates climbed from 3.5% to 13.6% over 40 months simply by automating future increases. Set up automatic transfers on payday, run a 10-minute weekly check-in, and build sinking funds for non-monthly costs like car repairs or insurance premiums.
Ready for more control over your money? See how Complete Controller helps turn financial goals into actionable plans.
How to Build an Emergency Fund Step by Step
An emergency fund is the buffer that keeps life’s surprises from becoming credit card debt. With 36% of Americans unable to cover a $400 emergency, this single habit can be the difference between stability and a financial spiral.
Emergency fund: Why 3–6 months of expenses matters
Aim for 3–6 months of essential living costs:
3 months: stable job, dual high incomes
6+ months: self-employed, single income, or volatile industry
If you’re tackling high-interest debt, save a $1,000 starter fund first, then attack the debt aggressively before fully funding 3–6 months. The Consumer Financial Protection Bureauoffers excellent free tools to help you map this out.
Step-by-step setup
Define your target — multiply bare-bones monthly essentials by 3–6.
Open a separate high-yield savings account — easy to access, slightly out of sight.
Automate contributions — even $25–$100 per paycheck builds the habit.
Refill after use — treat any withdrawal like a mini loan from yourself.
Credit & Debt: Use Borrowed Money Without Letting It Use You
Managing credit and debt is central to personal finance basics, and it’s where most households quietly leak wealth. The average credit card interest rate on accounts carrying a balance hit 22.76% in May 2024, according to the Federal Reserve Bank of St. Louis. At those rates, minimum payments can stretch payoff for decades.
Understanding credit scores and credit utilization
Your credit score is a three-digit number predicting how likely you are to repay borrowed money. The biggest levers:
Payment history — on-time vs. late
Credit utilization — keep below 30%; under 10% is even stronger
Length of credit history
New credit and credit mix
Debt payoff strategies: Snowball vs. avalanche
Both methods work; the best one is the one you’ll finish.
Debt snowball method: Attack the smallest balance first for quick wins and motivation.
Debt avalanche method: Attack the highest-interest debt first to save the most money.
To speed things up, automate fixed extra payments, throw windfalls at balances, and consider 0% balance transfers only with a strict payoff plan. For students managing loans alongside credit cards, our guide on Student Debt Management Tips offers practical strategies you can apply today.
Basic Investing Fundamentals: Put Your Money to Work
Once your budget is stable, your emergency fund is started, and high-interest debt is shrinking, you’re ready for investing. The good news? It doesn’t have to be complicated.
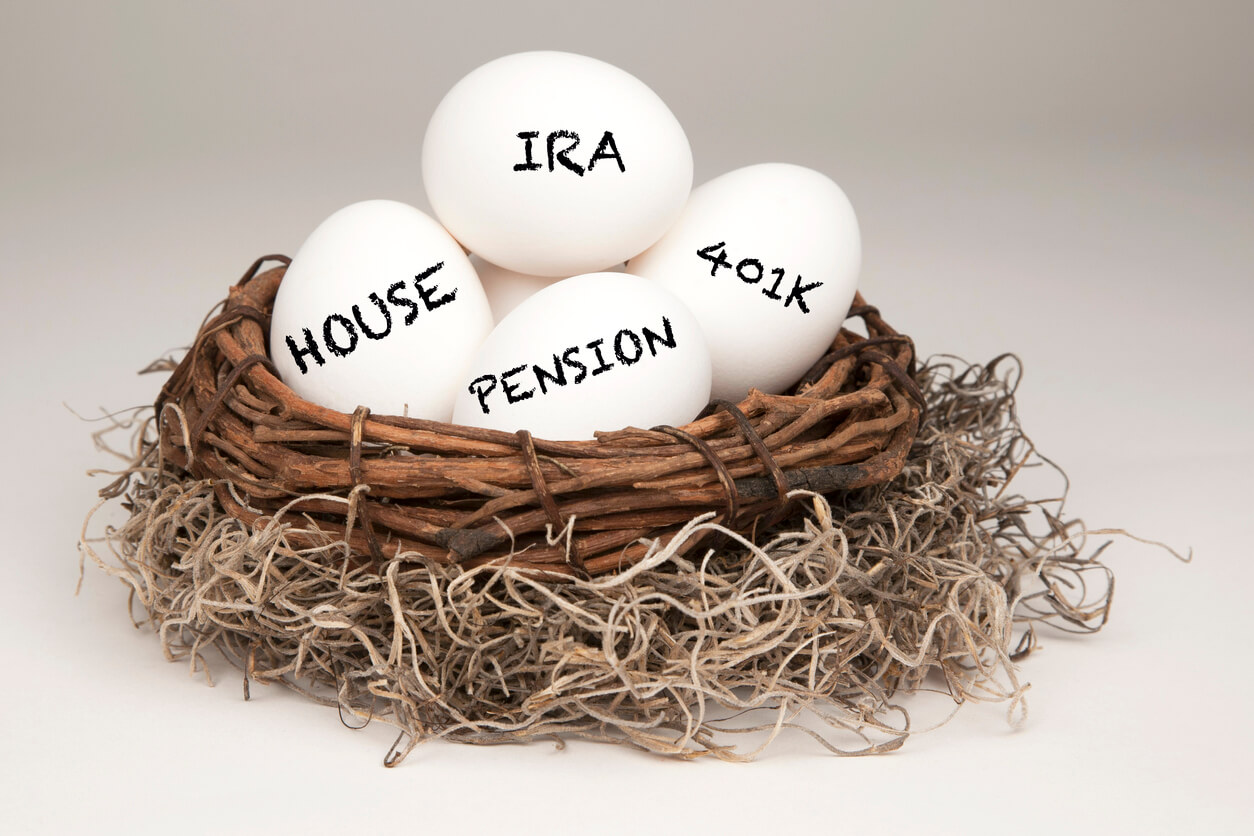
Compound interest basics and retirement planning
Compound interest is interest earned on your contributions plus previous interest—growth on top of growth. At a 7% average return, money roughly doubles every 10 years (the Rule of 72). The SEC’s Investor.gov has a free calculator that makes this strikingly clear.
401(k) vs IRA comparison
Feature
401(k)
IRA
Where offered
Through employer
Opened individually
Contribution limits
Higher
Lower
Employer match
Often available
Not applicable
Investment control
Limited menu
Wider choices
A simple retirement order of operations:
Capture the full 401(k) employer match
Fund a Roth or Traditional IRA
Increase 401(k) contributions or open a taxable brokerage account
Stick with diversified, low-cost index funds or target-date funds, match risk to your time horizon, and avoid emotional decisions during market dips.
Conclusion: Your Next Best Step Starts Today
You don’t need a finance degree to master personal finance basics—you need a clear order of operations, a few guardrails, and the willingness to begin where you are. Budgeting, building an emergency fund, managing credit and debt, and steadily investing are the same steps I’ve watched hundreds of clients use to move from financial chaos to calm. The turning point is rarely a windfall; it’s the decision to stop avoiding your numbers and build a system you actually follow.
Start small today: pull last month’s bank statement, sketch a 50/30/20 budget, or open a separate savings account with a $50 automatic transfer. When you’re ready for expert guidance tailored to your household or business, visit Complete Controller and let our team help you build the financial clarity you deserve.
Frequently Asked Questions About Personal Finance Basics
What are the basics of personal finance?
The basics include budgeting, saving, managing debt, building credit, planning for emergencies, and investing for long-term goals like retirement.
How do I start learning about personal finance?
Begin by tracking income and expenses, creating a simple 50/30/20 budget, building a small emergency fund, and learning how credit scores and interest rates work. Then progress into retirement accounts and basic investing.
How much should I have in an emergency fund?
Aim for 3–6 months of essential living expenses. Start with a $1,000 starter fund while paying off high-interest debt, then build to the full 3–6 months.
What’s the difference between the debt snowball and debt avalanche methods?
The snowball pays off the smallest balance first for quick motivational wins. The avalanche targets the highest-interest debt first to save the most money over time. Both work—pick the one you’ll stick with.
Should I invest or pay off debt first?
Always capture your employer’s full 401(k) match first—it’s free money. Then aggressively pay off high-interest debt (over ~7% APR) before increasing investments beyond the match.
Federal Reserve Bank of St. Louis (FRED). (Updated May 2024). Commercial Bank Interest Rate on Credit Card Plans, All Accounts (TERMCBCCALLNS). https://fred.stlouisfed.org/series/TERMCBCCALLNS
Thaler, Richard H., and Shlomo Benartzi. (October 2004). Save More Tomorrow™: Using Behavioral Economics to Increase Employee Saving. Journal of Political Economy. https://www.journals.uchicago.edu/doi/10.1086/380085
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Jennifer BrazerFounder/CEO
Jennifer is the author of From Cubicle to Cloud and Founder/CEO of Complete Controller, a pioneering financial services firm that helps entrepreneurs break free of traditional constraints and scale their businesses to new heights.
Brittany McMillen is a seasoned Marketing Manager with a sharp eye for strategy and storytelling. With a background in digital marketing, brand development, and customer engagement, she brings a results-driven mindset to every project. Brittany specializes in crafting compelling content and optimizing user experiences that convert. When she’s not reviewing content, she’s exploring the latest marketing trends or championing small business success.
Life insurance every person should have. It has many commonly known benefits, and some you may not be aware that life insurance has. If you consider carrying life insurance, you should know the benefits and the types of issues it covers, along with other advantages having a good life insurance policy can provide you. Here are seven benefits you can receive if you carry life insurance that everyone should know.
Disability Benefits
Although the term disability is related to Medical Assistance Insurance, Life Insurance may also benefit from the economic loss caused by this fact. One of the most common are:
Exemption from Payment of Premiums for Disability.
Through this, the insurer is given protection from everyday charges. Exemption from premium payment for the employer this benefit obliges the insurer to renounce to continue charging the premiums when the policy owner has died or has suffered a total disability. This benefit is granted in the policies paid by the parents on the life of their children.
Benefit for Accidental Dismemberment
Life has a knack for coming at us when we least expect it. From accidents to contingent events, sometimes life takes us to our bed, and even walking becomes a hurdle, let alone earning a living. Insurance in such a situation comes with a benefit for accidental dismemberment.
This benefit gives the insured a payout if the dismemberment is due to an accident. If the policyholder suffers the loss of one of their limbs, the vision of one or both eyes, and the hearing loss of one or both ears, this would be the benefit used.
Benefits for Accelerated Death
In the case of benefits for an accelerated death, a few pre-requisites are essential. The insured is given the right to receive a part of the death benefit before it occurs if certain conditions are established. If the contract conditions have been met and the person is going through a terminal illness, this benefit can be collected by the policyholder or beneficiary.
Benefit for Serious or Catastrophic Illness.
The life insurance policy can give the insured a part of the death benefit before it occurs if they from an illness specified in the policy’s general conditions.
Generally, the insurers that provide this benefit contemplate the following diseases:
Invasive cancer
AIDS
Myocardial infarction
Cerebrovascular accident
Coronary Bypass Surgery
Alzheimer’s
Transplantation of vital organs.
The Benefits of Long-Term Health Care
For people going through a chronic illness that may cause them significant expenses, the insurance policy can come across as a savior in such a situation. Various insurance policies follow this norm, from providing a monthly rent to the person who needs permanent medical attention due to his health condition to any expensive aid. The insurer, however, will have to specify the types of medical care covered by the policy in this case.
Insurance for Spouse and Children
Insurance policies are best for people who fear the security of their children and spouses. If it so happens that you wonder about what will happen to your spouse and children, chances are an insurance policy can help you a great deal. It will provide both your children and spouse both, depending on the policies maintained during the time it was signed.
Security for Children
Another additional benefit of an insurance policy is that some policies provide specifically to children, too. If both parents die and children do not have anyone to look after their needs, through the additional benefits of an insurance policy, they will get to live through life without any problem.
Conclusion
Insurance comes with many benefits. It provides security to the family of the deceased to help people in their worst time. Consequently, individual life insurance policies come with tax-deferred savings and estate savings, making life easier in more ways than ever.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Millennials are known as a carefree generation who worships the YOLO (You Only Live Once) attitude. Not worrying about the future, investing their time, energy, and even their money in the present is generally how this generation approaches all aspects of life.
What this generation does not understand that time is their most valuable asset. It is something they will not get when they need it. Therefore, the sooner the millennials begin their financial planning, the better it will be for them. Rather than earning and spending it all on the present, the millennials must consider planning for their future or retirement plans.
The benefit of time can help millennials design an extensive financial plan that will serve as excellent support for them in the future. Here are five financial planning tips for Millennials or any generation.
Use the Time
Time is the most significant advantage millennials have! Instead of waiting till their 40s or 50s, the millennials can start saving from today. Rather than spending every penny earned, they should take out small portions of their earnings. Soon saving will become a habit, and they will save a considerable amount at the time of their retirement. Many experts stress that time is something not many people have, but these young souls can start saving today for a better future!
Money Management Strategies
Another tip that can help millennials in their financial planning is to cultivate proper money management habits. A balance sheet is a wise approach, as it will provide a financial summary, helping an individual keep track of all the money earned and spent. These balance sheets can help millennials prepare to reduce some luxuries and cut down on unnecessary expenditures.
Setting Financial Goals
Setting up financial goals is an excellent way of planning for the future. The people of Gen Y have big plans when it comes to their lifestyle. Therefore, it is best to set their goal for retirement at an early age to have a fair amount to spend a lifestyle just as they dreamed of with their young minds. Not only for retirement but also a goal of buying a house or even a car can be set, giving these young minds a direction to work.
Thinking Wisely About Debts
The debt which a massive number of millennials get themselves into is a study loan. Of course, it is a step taken towards a prosperous future. But when taking a loan, millennials must plan how they will be paying off the debt.
Using credit cards is all fun until one gets into credit card debt. Considerable interest is imposed after delaying the payment of these credit cards. Not paying the credit card bill every month may lead to a massive debt, which one will have to keep paying throughout the lifetime; therefore, if one uses a credit card, it should be paid for every month.
Health Insurance
It is a smart move to think about the possibilities of the future. Opting for health insurance makes sure that the health of one is covered if they fall seriously ill. Before one goes for this plan, it is best to calculate and analyses whether the premium payments are affordable or not.
Conclusion
Today’s Millennials are smarter and are exposed to the perks of technology, enjoying a life full of convenience. They live on the concept of earning in the present and spending in the present. A financial plan is something that they need to work on because they have the element of time in their favor today, and they must make the best use of it! By planning financially, they can promise themselves a life full of comfort at an older age!
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
One of the responsible challenges for a person is to manage expenses, utility bills, and savings that aren’t easy. But it would be best if you weren’t anxious for it as millions of tips regarding investment or protection available online. Also, if we seek to grow our heritage, the most direct way is obviously to save. But this is not easy; the phrase “I cannot save” is one of the most widespread.
Everyone can save and increase their assets. We give you five tips that will help you get it and prevent you from entering the vicious circle of credit, something essential to growing wealth.
Know our finances.
If you don’t know where you are, you will hardly know which way to go. The first thing we should do is understand how we are financially speaking. We need to know:
Equity balance: this sounds very pompous, but it is nothing more than listing the value of our assets (house, money in the bank, investments, jewelry, and documenting our debts (mortgage, consumer credit, etc.).
Daily finances: How much we enter (payroll, rent, courses) vs. how much we spend here; we need to list the expenses and classify them into three levels: essential, necessary, and avoidable.
Find motivation.
The effort is more bearable if it leads you to a dream. Saving is difficult and, therefore, you have to have reasons to do so. It is essential to look for motivation, and there is no better motivation than our dreams.
First, let’s think about what life goals we have and quantify them (both in amount and in time): Go live abroad one year (we will need $10,000 in 5 years), open your own office ($17,000 in 8 years), change of car ($21,000 in 7 years).
Second, let’s calculate how much we need to save a month from reaching them. And the next step is to sort in order of importance. Now we have to combine this plan with our finances. Or put another way: With what we have left after taking away all our expenses, how many dreams can we achieve?
Review expenses.
If you want to change, start with what is within your reach. Knowing our finances and with our quantified and ordered life goals, we may realize that we need to save more. Saving more can be achieved in two ways, increasing revenue or reducing expenses. Which of the two strategies depends only on us?
The most immediate is to review our expenses to see which we can avoid changing our customs.
Automate.
Saving requires military discipline. To make sure that the size of our piggy bank will increase month by month, we must do two things, both of equal importance: Save when we receive the income and automate the savings process.
Automate can be a simple transfer to another account or hiring a savings product that monthly addresses the amount we want to save per month.
Keep inflation in mind.
There is an invisible tax that we all suffer and almost forget. If we have a goal that we want to achieve in 10 years, and that we have quantified today at around $20,000, when the time comes, it is normal for it to cost us more than $20,000. Prices rise year after year for inflation, and on average, an annual increase of 2% is evaluated. It means that the $20,000 we thought we were going to need, it turns out, will eventually become $24,500 after ten years.
We must not forget inflation! We calculate the price that the objective we seek will have in the future and increase the monthly saving amount, or we invest the savings to save inflation. We can all save, and the motivation to achieve our life goals will help keep the effort it represents.
Consider a systematic investment plan.
A systematic investment plan is a reliable source for professionals that are finding to amplify their wealth or income. With this approach, anyone can set aside a deliberate amount to invest in a monthly SIP of their choice. In the past, agents conducted this process and charged a commission for operational services and advisory. Today, you can do this by downloading new-age financial apps. Only you will need to add your primary details. You can start an investment at $500 for one month. You can add 5% of your monthly income if you want to ensure better and timeless returns.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
There are many types of insurance available to people covering every aspect of life. There is auto insurance, health insurance, life, homeowners, renters, and travel insurance. Many don’t know that you can also carry insurance on your debit or credit cards. This insurance is primarily to cover the holder should they have issues with the card or have identity theft issues.
Before you decide if you should carry this type of insurance, it is recommended that you carefully read all the documentation to be clear about the conditions to use the insurance, its coverage, and its maximum amounts. Not only have credit cards had insurance against fraud or contingencies during trips or accidents. There are coverages associated, debit cards, and, in some cases, without you having to pay an additional cost.
The electronic payments industry is overwhelmed by four organizations. Visa, MasterCard, American Express, and Discover are answerable for taking care of most of the world’s card payments. Visa and MasterCard present exceptional contributions since neither of the companies is engaged with broadening credit or giving any cards.
It implies all Visa and MasterCard installment cards are given through some co-marked relationship. While the two organizations don’t broaden or give any cards, they do accomplish offering the broadest cluster of items enveloping credit, charge, and pre-loaded card choices.
Visa and MasterCard are the main installment processors associated with every one of the three territories of the installments market. Working only as organization processors, these two organizations have a novel edge yet work unexpectedly.
Visa and MasterCard are both traded on an open market. Visa orders a $365 billion market capitalization while MasterCard follows intently behind at $293 billion. Since neither one of the companies broadens credit or issues cards through a financial division, both have a wide arrangement of co-marked contributions.
The plans of action of the two organizations are fundamentally the same. Visa and MasterCard don’t give cards legitimately to general society but instead through part money-related organizations like banks and credit associations. At that point, the cards issued for people and organizations, either straightforwardly or in association with aircraft, inn, or retail rewards through banking institutions or other issuing organizations outside of Visa and Mastercard.
Not only have credit cards had insurance against fraud or contingencies during trips or accidents. There are coverages associated, debit cards, and, in some cases, without you having to pay an additional cost.
Likely, you have never done so, but when choosing what the best account to hire is, you should also check which insurance includes your Visa or MasterCard debit card. In times of moderation of expenses like those of now, different policies can be beneficial when traveling, in case of an accident or for the theft and loss of our means of payment.
The contract signed with the bank includes all the advantages and benefits of the account and the debit card. We recommend that you carefully read all the documentation to be clear about the conditions to use the insurance, its type of coverage, and its maximum amounts.
Saving money to allocate to other expenses
Many financial institutions offer debit cards at no cost, without any commission for issuance and maintenance. Therefore, the included insurance can be decisive when choosing between one card or another. Keep in mind that if the debit cards do not have these policies, the approximate cost of the annual premium that you should pay to access basic coverage and compensation will range between 200 and 400 dollars.
Remember that to benefit from the guaranteed benefits. The incidence must occur when making transactions such as payments, cash withdrawals, or purchases. If an accident, you must also block your card from the customer area or channels indicated by your entity and make a complaint to the corresponding authorities.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
With so many forced to work at home and start their businesses, there is a lot of concern about financing a business venture or small business. Looking at ways to finance a business is nothing new, but crowdlending is still a fairly recent form of getting your business or idea financed.
People are finding ways to earn money by not aligning with an organization with the help of the internet and opting to be self-employed. Especially in 2020, where COVID-19 changed the world of business, many people were forced out of work. This unemployment pushed more people to start their businesses or become freelancers.
Last year was the year of crowdlending. Financially speaking, the shortage of credit that undermines the competitiveness of the autonomous and small companies has further sharpened the ingenuity and even more alternative financing formulas for which SMEs opt and entrepreneurs, such as crowdlending.
Crowdlending is another collective financing formula in which individuals are giving and receiving business loans, generally from online platforms. The main difference of this financing model compared to crowdfunding is that, in the second, individuals invest in social capital, obtaining shares of the company. In the first, the financing is carried out in the form of a loan.
What are the conditions of crowdlending loans?
In this credit system, the investors themselves, the individuals, decide the amount they will lend and the interest rate. If a company receives many financing requests, it can choose between those that offer less interest. At the end of the financing period, each individual will receive the requested interest.
The philosophy that revolves around this financing model is to provide individuals with the power to decide what type of projects they invest in. Thanks to the online platforms from which the investment is made, transparent information is offered on what activities the money invested is used.
Although it has gained ground, it is a developing formula in our country in which it is necessary to consider some aspects. It has been, precisely, the concept of transparency, of connection between the investor and the company in the online environment and, especially, through the use of social networks, which has made this formula gain positions in recent months.
However, it should be remembered that crowdlending platforms are not within the deposit guarantee fund. If the company in which it has invested fails, the individual will have difficulty recovering the investment.
However, the platforms that manage this type of financing carefully select the projects that will become part of them, reducing the default rate to 2%. In comparison, the delinquency in banking is more than 10%.
How has crowdlending evolved?
Crowdlending or the P2P lending system initially provided credit access to people who could get spurned by conventional institutions. It was also a way to consolidate student loans with a more favorable interest rate.
However, in recent years, crowdlending has substantially increased its reach. Many target consumers who wish to pay off their credit card debt or even students at a good, lowered interest rate. Moreover, they can also pay off home improvement loans as well as auto financing loans as well.
Not to mention the advent of modern-day websites, which has improved ways to improve crowdlending practices. It also opened up opportunities for freelancers to provide services individually. It’s also a blessing in disguise for consumers; because of the lowered service cost and improved service quality.
Conclusion
However, before you opt for acquiring freelance crowdlending services, you need to keep a few things in mind. Whichever consumer or investor using a P2P lending site should observe the fees on transactions; every site or professionals sets money differently. Still, commissions may be charged to the lender or borrower.
It works similarly to banks, where they charge late fees, loan origination fees, and bounced-payment fees extensively. All in all, if you want to improve your credit score or just rid yourself of a hefty student loan, crowdlending is how you should go about it.
And with freelance services in the frame, you have ample opportunities to expand your horizons and become debt-free. Remember, the world provides you opportunities, and you have to make the most out of it.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
A lack of flexibility, management involvement, support, appropriate training, effective organizational communication, and communication between employees and management are the main obstacles that may hinder organizational change management practices. Similarly, failure to cope with people resistance and test the process, poor senior management, misapplication, and misunderstanding of the models and techniques can all contribute to negative associate morale and slow down the change management process.
When the outcome of the process does not exceed the expectation of the Organizational Change Management (OCM), then the process of Business Process Re-engineering (BPR) has failed and can cause the organization a tremendous financial loss. Moreover, companies can also bring changes to the organizational management system by focusing on the Maturity Model that assists in increasing their maturity level and stabilizing their positions in the competitive marketplace.
Impact of Constraints on Construction Projects
Various factors may limit the Change Management (CM) process of organizations, predominantly construction projects. The most common constraints are mentioned below:
Economic Constraints
Economic constraints are based on the allocation of money and budgetary limitations. Simply stated, economic constraints are centered around money. Companies without budgets would not be able to effectively achieve proposed objectives and goals regarding quality measures and productivity. Therefore, the allocation of money within the budget is entirely dependent on the progress of the project. If the funds are not allocated appropriately, it will negatively affect the performance and progress of the project and can result in a financial loss for the organization.
Legal Constraints
Rules and regulations may cause some issues in the lifecycle of construction projects. These legal constraints are likely associated with safety and work laws, supervision regulation, and plans but may affect the project’s performance. Legal constraints generally impede the construction process by creating delays that affect schedules and affect the reliability of the projects and organization. Understanding legal constraints allows the project manager to prepare and work to avoid any obstacles so the project can be completed on time and on budget.
Environmental Constraints
Environmental constraints are rules and considerations regarding the physical environment within a construction project. These considerations can include air quality, tree maintenance, site visitor limits, sound management, and so forth. Within the planning and design stage of the project, the project management team must consult with the Environmental Division to obtain an endorsement or validation for the project. If the endorsement is not obtained at the appropriate point in time, the project could be delayed or canceled altogether. Additionally, there could be one-time technological constraints that surface from air security, hierarchy renovation, visitor limits, excavation restrictions, and so forth.
Technical Constraints
There are specialized requirements in the United Kingdom that can apply to temporary technical sites. Specialized requirements can be thought out and prepared for by the project team at the onset of the construction project. Building assignments in the United Kingdom can become a constraint on a project if they require a temporary field site. These sites may have capacity or space limits, difficulties receiving deliveries, or have technical constraints where electricity, air conditioning, heat, and maintenance work are essential. Similarly, having an internet connection with appropriate broadband, phone lines, and a security system are additional technical constraints on a worksite of a construction project. In essence, worksites require adaptability that traditional work environments may not need. In addition to these technical constraints, the project team must continue to advance the project according to the timeline and budget.
Conclusion
Constraints are inevitable in any construction project. They commonly include economic constraints, legal constraints, environmental constraints, and technical constraints. While awareness does not suggest that every requirement or constraint can be overcome, it is beneficial to the team and construction project to be prepared and work within the limitation and not against it.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
Financial stability is a goal every individual in this world is striving to achieve. Whether it is a business owner or a job worker, each of these people struggles to get to a point where financing their dreams is not an issue. Millions of people in this world have to give up on their dreams and passions just because they do not have the financial support they need. The term itself is subjective. It means it holds a different definition in the eyes of different people.
For some people, financial stability is not looking at the price tag when shopping; it is a sustainable business. There are people for whom purchasing a house or diving their car is reaching financial success. Then some believe that paying off their debts is the point of financial stability.
Throughout life, many people borrow loans, sometimes for completing their educations, sometimes for purchasing a house, sometimes for a vacation, and sometimes for medical emergencies. Anyone who wishes to reach financial stability needs to make repayment of debts their top priority.
Repayment of debts is one of the biggest obstacles in one’s path towards achieving financial stability and success. Here are the most effective steps that can help you succeed in debt repayment, leading you to financial stability and remove stress.
Calculate the total amount of your debts: The first step towards getting rid of your debts is to admit that you have debts. Once you hit yourself with a reality check, make up your mind to get rid of this financial risk hovering above your head.
Carefully calculate the total amount of money you owe. Get rid of the debts with the highest interest rates first; this will help you save a lot of money. It is difficult to solve your problems if you do not look at the full picture of your financial status.
Address Your Bad Spending Habits: One of the most important steps is to address your bad spending habits. You will not be able to repay your debts until you cut down on your unnecessary expenses. It is time for you to stop wasting money. You can start by changing your spending practices.
Carefully monitor the amount you earn, enlist your basic expenses, and try to reduce expenses as much as possible. All this means a change in your way of life. Make sure you do not even add even a single dollar to your already crippling debt. For instance, using a debit card instead of a credit card can help you keep your credit card debt from growing. Try to use the card if you have money in your account.
When you acquire some extra money, instead of buying clothes, shoes, or your favorite perfume, use it to repay the debts.
Choosing the Smartest Way Out: There are several options to solve your debt problems, but not all these methods are suitable for you. Make sure to select the most appropriate option that is perfect for your needs. Remember that one bad step can ruin the future.
Avoid Using Credit Cards: As soon as you have successfully repaid your debts, call the bank to cancel the credit card. Leave credit cards at home and fight the temptation to use them. You will not have to fight your inner self when you do not have a credit card.
Never pay the debts of one credit card with another. It might be the biggest blunders of your life. We know that credit card offers can be attractive, but you want to stay financially stable, you need to turn your head the other way.
Hire Professional Assistance: For some, being extravagant is a psychological problem. Its sending habit turns into an addiction similar to that of drinking, gambling, or doing drugs. Social problems such as divorce and loss of work or inevitable emergencies such as illnesses can also be a cause; in such cases, it is advisable to seek professional financial advice.
Make repayment of your debt your financial priority. It will help you reach a stable state, where you think about saving and even looking for investment options in the best cases. Debt repayment is the first step toward financial stability.
About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.
 About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.