Employee Theft Reporting Requirements:
Why Small Businesses Miss Steps
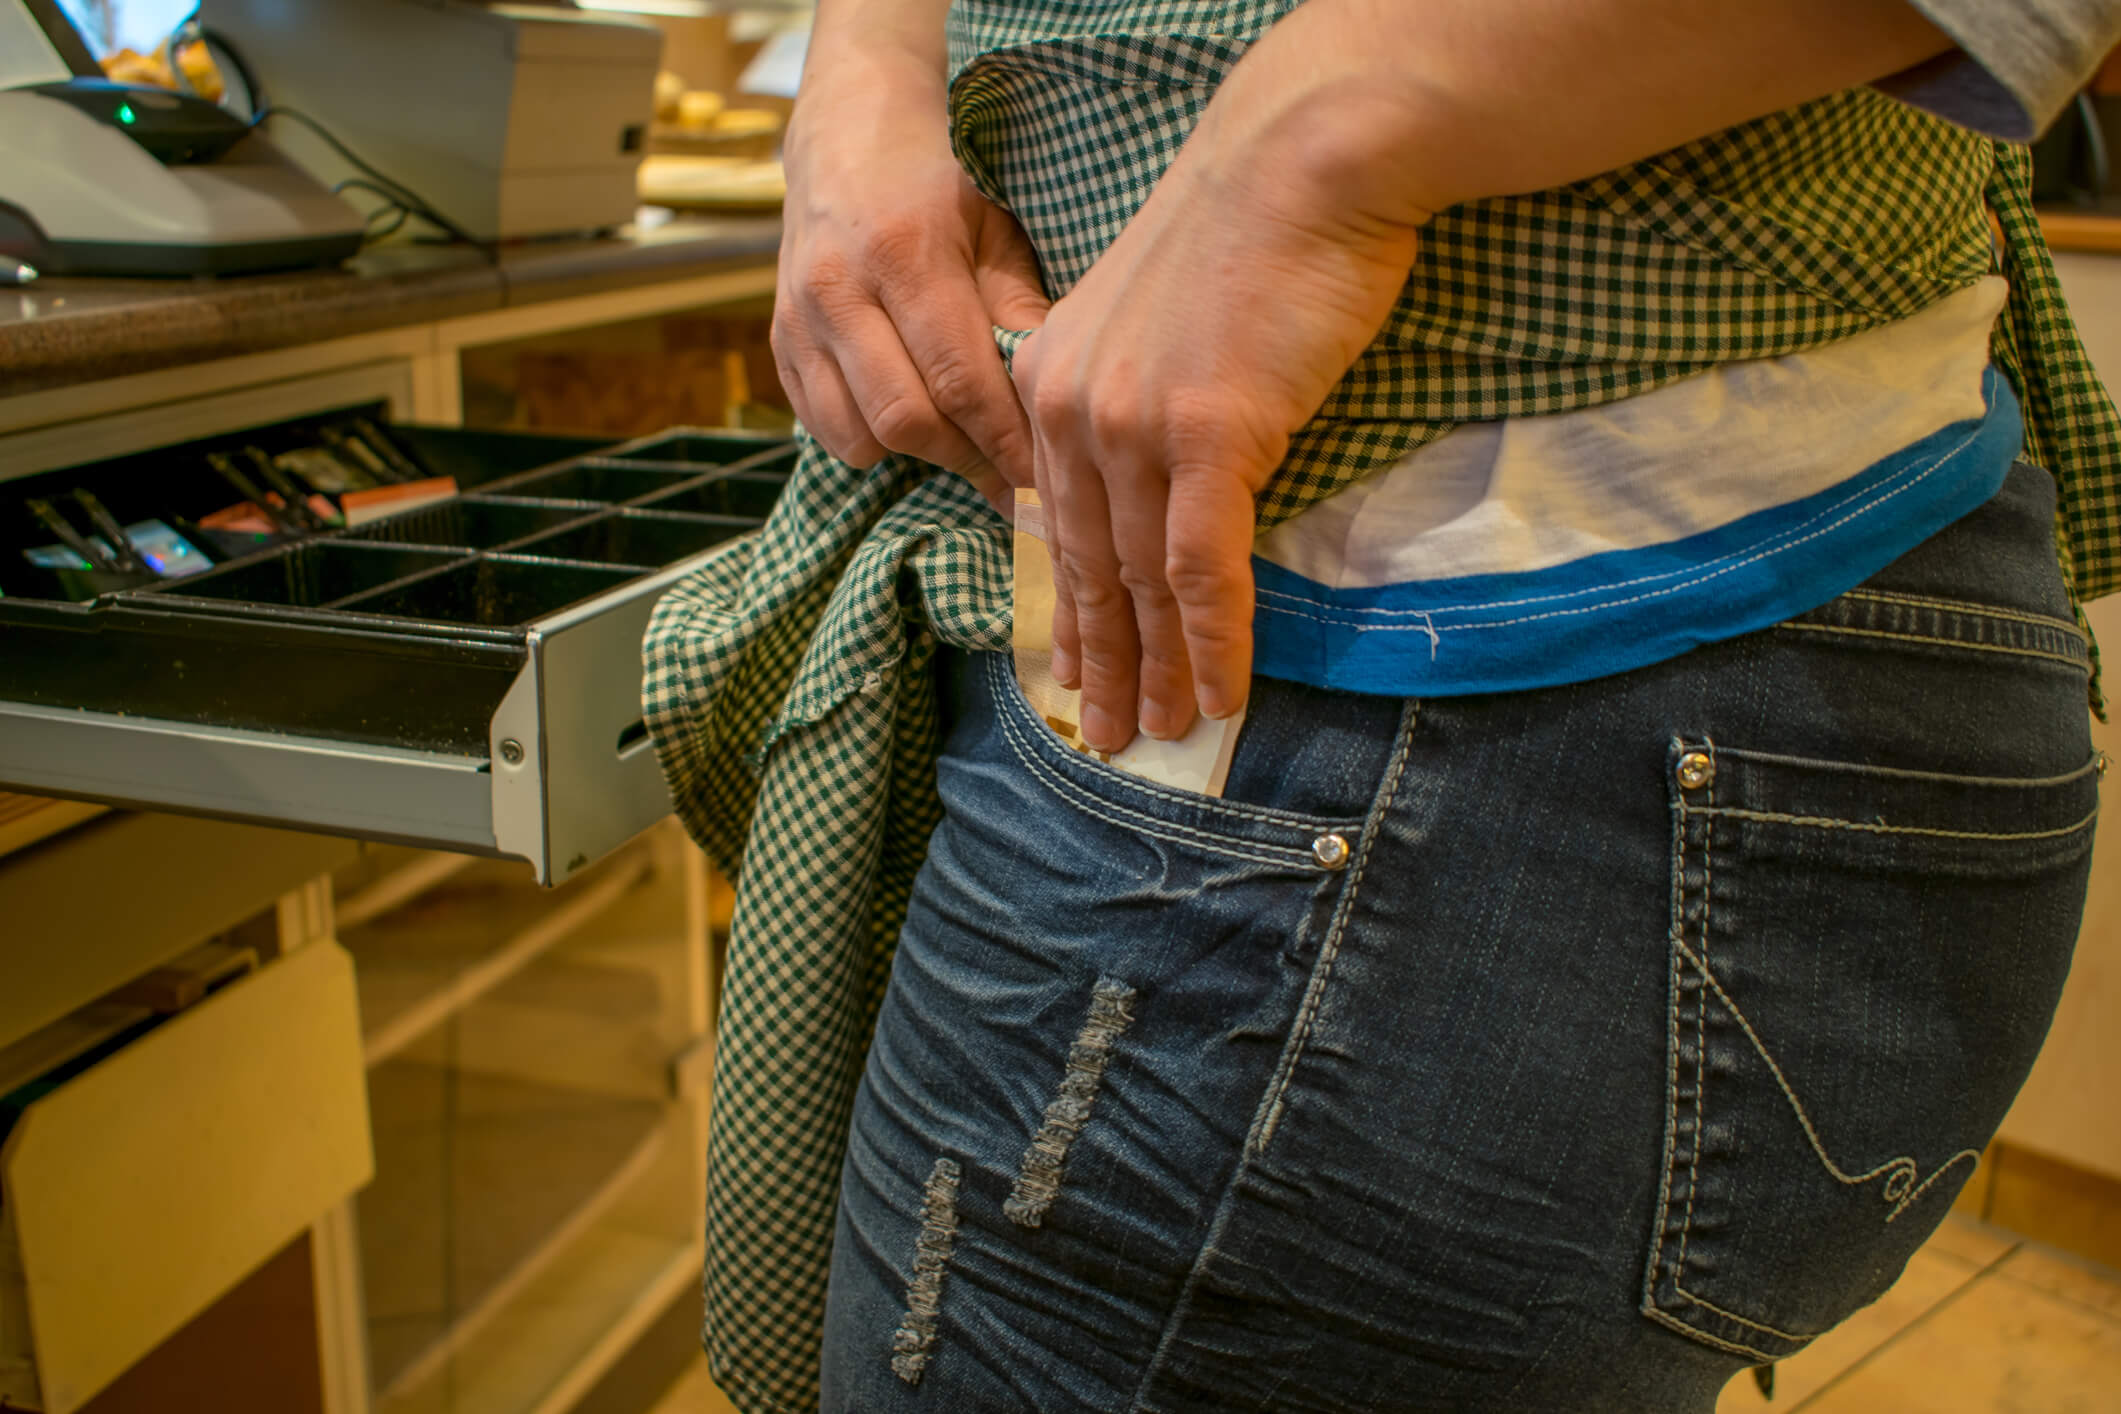
Employee theft reporting requirements generally involve five core steps: documenting the suspected loss, preserving evidence, following your company’s internal escalation procedure, notifying your insurance carrier within policy windows, and deciding whether to involve law enforcement or regulators. There is no single nationwide filing deadline that covers every incident—your obligations shift based on the loss amount, state law, insurance policy terms, industry rules, contractual duties, and whether privacy or whistleblower protections apply.
Here’s what keeps me up at night: in over 20 years building Complete Controller into a trusted partner for small and mid-sized businesses across nearly every industry, I’ve watched good owners freeze when theft hits close to home. They delay because the amount feels too small, the evidence feels too thin, or the suspected employee feels too much like family. That hesitation is exactly what costs them—missing records, expired insurance windows, and avoidable legal exposure. In this article, I’ll walk you through the first-24-hour checklist, the legal and insurance landmines, how to document evidence without creating new risks, and the practical reporting roadmap I wish every founder had before an incident happens.
What are employee theft reporting requirements and why do small businesses miss steps?
- Employee theft reporting requirements include internal documentation, evidence preservation, management or HR escalation, insurance notification, and—when appropriate—law-enforcement or regulatory reporting.
- Most small businesses lack a written theft reporting policy, named reporting owners, and an employee theft reporting hotline.
- A suspicion should always be documented, even when you aren’t ready to accuse, terminate, or prosecute.
- External reporting and civil recovery are separate decisions—you can pursue one, both, or neither, subject to your duties and contracts.
- The safest process protects evidence, limits unnecessary disclosure, prevents retaliation, and brings in counsel before confrontation.
What Small Businesses Must Do First When Employee Theft Is Suspected
The clock starts the moment someone raises a credible concern. What you do in the first few hours shapes everything that follows—evidence integrity, insurance coverage, employment liability, and whether you can recover losses.
How to report employee theft internally
A clean internal report protects the business and the person raising the concern. Here’s the baseline:
- Report to the designated manager, HR department, owner, compliance department, or workplace ethics hotline.
- Use neutral language like “suspected unauthorized transaction” rather than naming someone guilty.
- Record when the concern surfaced, who discovered it, and what triggered the report.
- Escalate immediately when the loss is ongoing, involves sensitive data, or may involve collusion.
- Do not interrogate or tip off the suspected employee before evidence and legal review.
Employee theft incident reporting procedure for managers
Managers need a repeatable workflow so judgment calls don’t derail the response:
- Ensure safety and stop ongoing access only when authorized.
- Notify the designated investigation owner.
- Secure records, devices, inventory, payment systems, and credentials.
- Open a confidential incident file.
- Separate facts, assumptions, and witness statements.
- Contact counsel, the insurer, law enforcement, or forensic professionals as appropriate.
- Document every decision and deadline.
What information is required for an employee theft report?
A standardized report form should capture the date, location, and discovery method; the asset or amount involved; names and roles of people with relevant access; transaction IDs and account references; a factual description without unsupported conclusions; witness information; supporting documents, logs, and physical evidence; immediate actions taken; any insurance or police notifications; and the person responsible for each follow-up step.
How Employee Theft Reporting Requirements Interact With Law, Insurance, and Employment Rules
“Reporting” has multiple destinations, and the rules vary by jurisdiction. Mistaking one obligation for all of them is how small businesses lose coverage and create new liability.
Legal requirements for reporting workplace theft
Before you act, check state criminal thresholds and statutes of limitation, mandatory-reporting rules for your industry, contractual duties to customers or lenders, data-breach notification rules when stolen property includes personal information, employment and surveillance laws, and whistleblower protections. Don’t treat any single dollar amount as a universal reporting trigger—misdemeanor and felony thresholds vary by state, and every incident should still be documented.
Insurance notice and loss prevention reporting
Review your crime, employee-dishonesty, cyber, and fidelity policies before assuming police notification is the only step. Many insurance policies set strict notice duties. The ISO Commercial Crime Coverage Form requires the insured to notify the carrier “as soon as possible” and submit a signed, sworn proof of loss within 120 days after discovery. Miss that window and you may lose the claim entirely.
Also:
- Preserve proof of loss and accounting records.
- Avoid settlement or repayment agreements before insurer and counsel review.
- Coordinate with a forensic accountant when the amount is uncertain.
- Record the claim number, adjuster contact, and document requests.
Employee theft can cost more than missing money. Strong bookkeeping helps catch financial red flags before they become bigger problems. See how Complete Controller can help protect your business.
How to Document Evidence Without Creating New Legal Risks
Most small-business articles tell owners to investigate but skip the controls that make evidence usable. This is where good intentions create bad outcomes.
Evidence preservation steps
Make read-only copies of accounting and point-of-sale records. Preserve original emails, messages, video, access logs, and cloud audit trails. Record the source, date collected, collector, and storage location. Restrict access to the investigation file. Never edit, rename, or casually forward originals. Maintain a simple chain-of-custody log.
Surveillance and recording laws differ by state. Audio recording, employee monitoring, and access to personal devices require legal review—don’t assume evidence is usable just because it’s technically obtainable.
Internal investigation process
In small companies, one person often wears several hats. Still, name an independent investigation owner—never let the suspected employee’s direct supervisor control the process. Typical roles include HR for employee communications and anti-retaliation controls, compliance for reporting decisions, finance for reconciliation and loss quantification, IT for logs and data preservation, and counsel for privilege, interview strategy, and termination decisions.
Why Small Businesses Miss Employee Theft Reporting Steps
The patterns are remarkably consistent across industries, and so are the fixes.
The owner treats theft as a personnel problem
Theft touches accounting, insurance, employment law, governance, and potentially criminal law. A private confrontation can destroy evidence and trigger retaliation claims. Build a written escalation matrix that names who receives reports, who preserves evidence, who contacts the insurer, and who approves law-enforcement notification.
The business has no theft reporting policy
A strong theft reporting policy defines covered conduct, reporting channels, good-faith protections, investigation ownership, evidence expectations, possible outcomes, and escalation deadlines. Templates commonly recommend multiple channels—manager, HR, email, phone, or anonymous system.
The cost of delay is real. According to the ACFE’s 2024 Report to the Nations, organizations lose an estimated 5% of revenue to fraud annually, the median loss per case is $145,000, and the median time from fraud start to detection is 12 months. A full year of silent bleeding is the price of waiting.
The business waits for perfect proof
There’s a difference between a reportable suspicion and a proven violation. Employees report credible concerns—investigators determine what happened. Waiting for certainty lets losses continue and records disappear.
Bookkeeping controls are too weak to detect patterns
Most employee theft surfaces through ordinary bookkeeping anomalies: duplicate vendors, unusual refunds, inventory shrinkage, altered payroll, missing deposits, or transactions just below approval limits. Monthly close should include owner review of bank reconciliations, exception reports, vendor changes, and user-access logs.
Real-World Case Study: Why Reporting Systems Matter
Weak controls plus no independent review can let theft run for decades. According to the U.S. Department of Justice, a small-town finance director in Dixon, Illinois stole roughly $53.7 million over more than 20 years by creating a fake account—the “Reserve Sewer Capital Development Account”—and using it to pay personal credit card bills. The scheme survived that long because no one independently reviewed her work.
The small-business takeaway: even a five-person company benefits from naming one investigation owner, one alternate reporting channel, and one evidence-preservation process. Your system doesn’t need to be bureaucratic—it needs to be clear, and it needs to assume that someday the normal reporting recipient might be the subject of the complaint.
Conclusion
Employee theft reporting requirements go far beyond calling the police. You need to document every credible concern, preserve evidence correctly, follow a written internal process, review insurance and contractual duties, protect good-faith reporters, and get legal advice before confrontation or termination.
After two decades of helping founders navigate exactly these moments, my advice is simple: build the reporting form and escalation checklist before you need them. A clear process protects your cash, your team, your customer data, and your reputation. Visit Complete Controller to learn how stronger bookkeeping and accounting services can help you catch irregularities earlier and respond with confidence.
Frequently Asked Questions About Employee Theft Reporting Requirements
What should I do if I suspect an employee is stealing?
Document the facts, preserve relevant records, notify the designated internal recipient, and avoid confronting or accusing the employee before you’ve reviewed evidence with counsel.
Do I have to report employee theft to the police?
Not every incident carries the same duty. The decision depends on state law, loss value, insurance terms, contracts, industry rules, and the nature of the conduct. Crime victims can also access support resources regardless of your reporting choice.
What information is required for an employee theft report?
Include the date, location, asset or amount involved, known facts, people with relevant access, witnesses, supporting records, immediate actions taken, and follow-up responsibilities.
Can I deduct the stolen amount from an employee’s paycheck?
Do not make a payroll deduction or require repayment without reviewing applicable federal and state wage laws, written agreements, and legal advice first.
How can employees report suspected theft anonymously?
Offer a workplace ethics hotline, secure web form, dedicated email, or third-party reporting channel—and clearly prohibit retaliation against good-faith reporters.
Sources
- Association of Certified Fraud Examiners (ACFE). (2024). Occupational Fraud 2024: A Report to the Nations. https://www.acfe.com/report-to-the-nations/2024-report
- Complete Controller. (2019, January 23; updated 2026). Why Employee Theft Goes Unreported. https://www.completecontroller.com/fraud-detection-prevention/
- Georgia State Properties Commission. (2023). Employee Theft and Dishonesty Policy. State of Georgia. https://spc.georgia.gov
- Insurance Services Office, Inc. (ISO). (2015). Commercial Crime Coverage Form (CR 00 21 11 15). https://www.independentagent.com/vu/SiteAssets/Documents/PDF/ISOForms/2013/CommercialCrime/CR0021_1115.pdf
- Lattice. (2025). Employee Theft Policy Template. https://lattice.com
- The Hartford. (2026). What to Do if You Suspect an Employee Is Stealing. https://www.thehartford.com
- Addison Law. (2025). Employee Theft and Fraud: Frequently Asked Questions. https://www.addisonlaw.com
- Fit Small Business. (2024). Employee Theft: Small Business Guide and Policy Template. https://fitsmallbusiness.com
- Workable. (2023). Employee Theft Policy Template. https://resources.workable.com
- U.S. Department of Justice, Office of Public Affairs. (2013, February 14). Former Dixon, Illinois Comptroller Sentenced to 19 Years in Prison for Stealing $53.7 Million. https://www.justice.gov/opa/pr/former-dixon-illinois-comptroller-sentenced-19-years-prison-stealing-537-million
- U.S. Department of Justice. Criminal Resource Manual 242: Maintaining Chain of Custody. https://www.justice.gov/archives/jm/criminal-resource-manual-242-maintaining-chain-custody
- U.S. Department of Labor, OSHA. Whistleblower Complaint. https://www.osha.gov/whistleblower/WBComplaint
- USA.gov. Help for Crime Victims. https://www.usa.gov/crime-victims
 About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.


 Brittany McMillen