


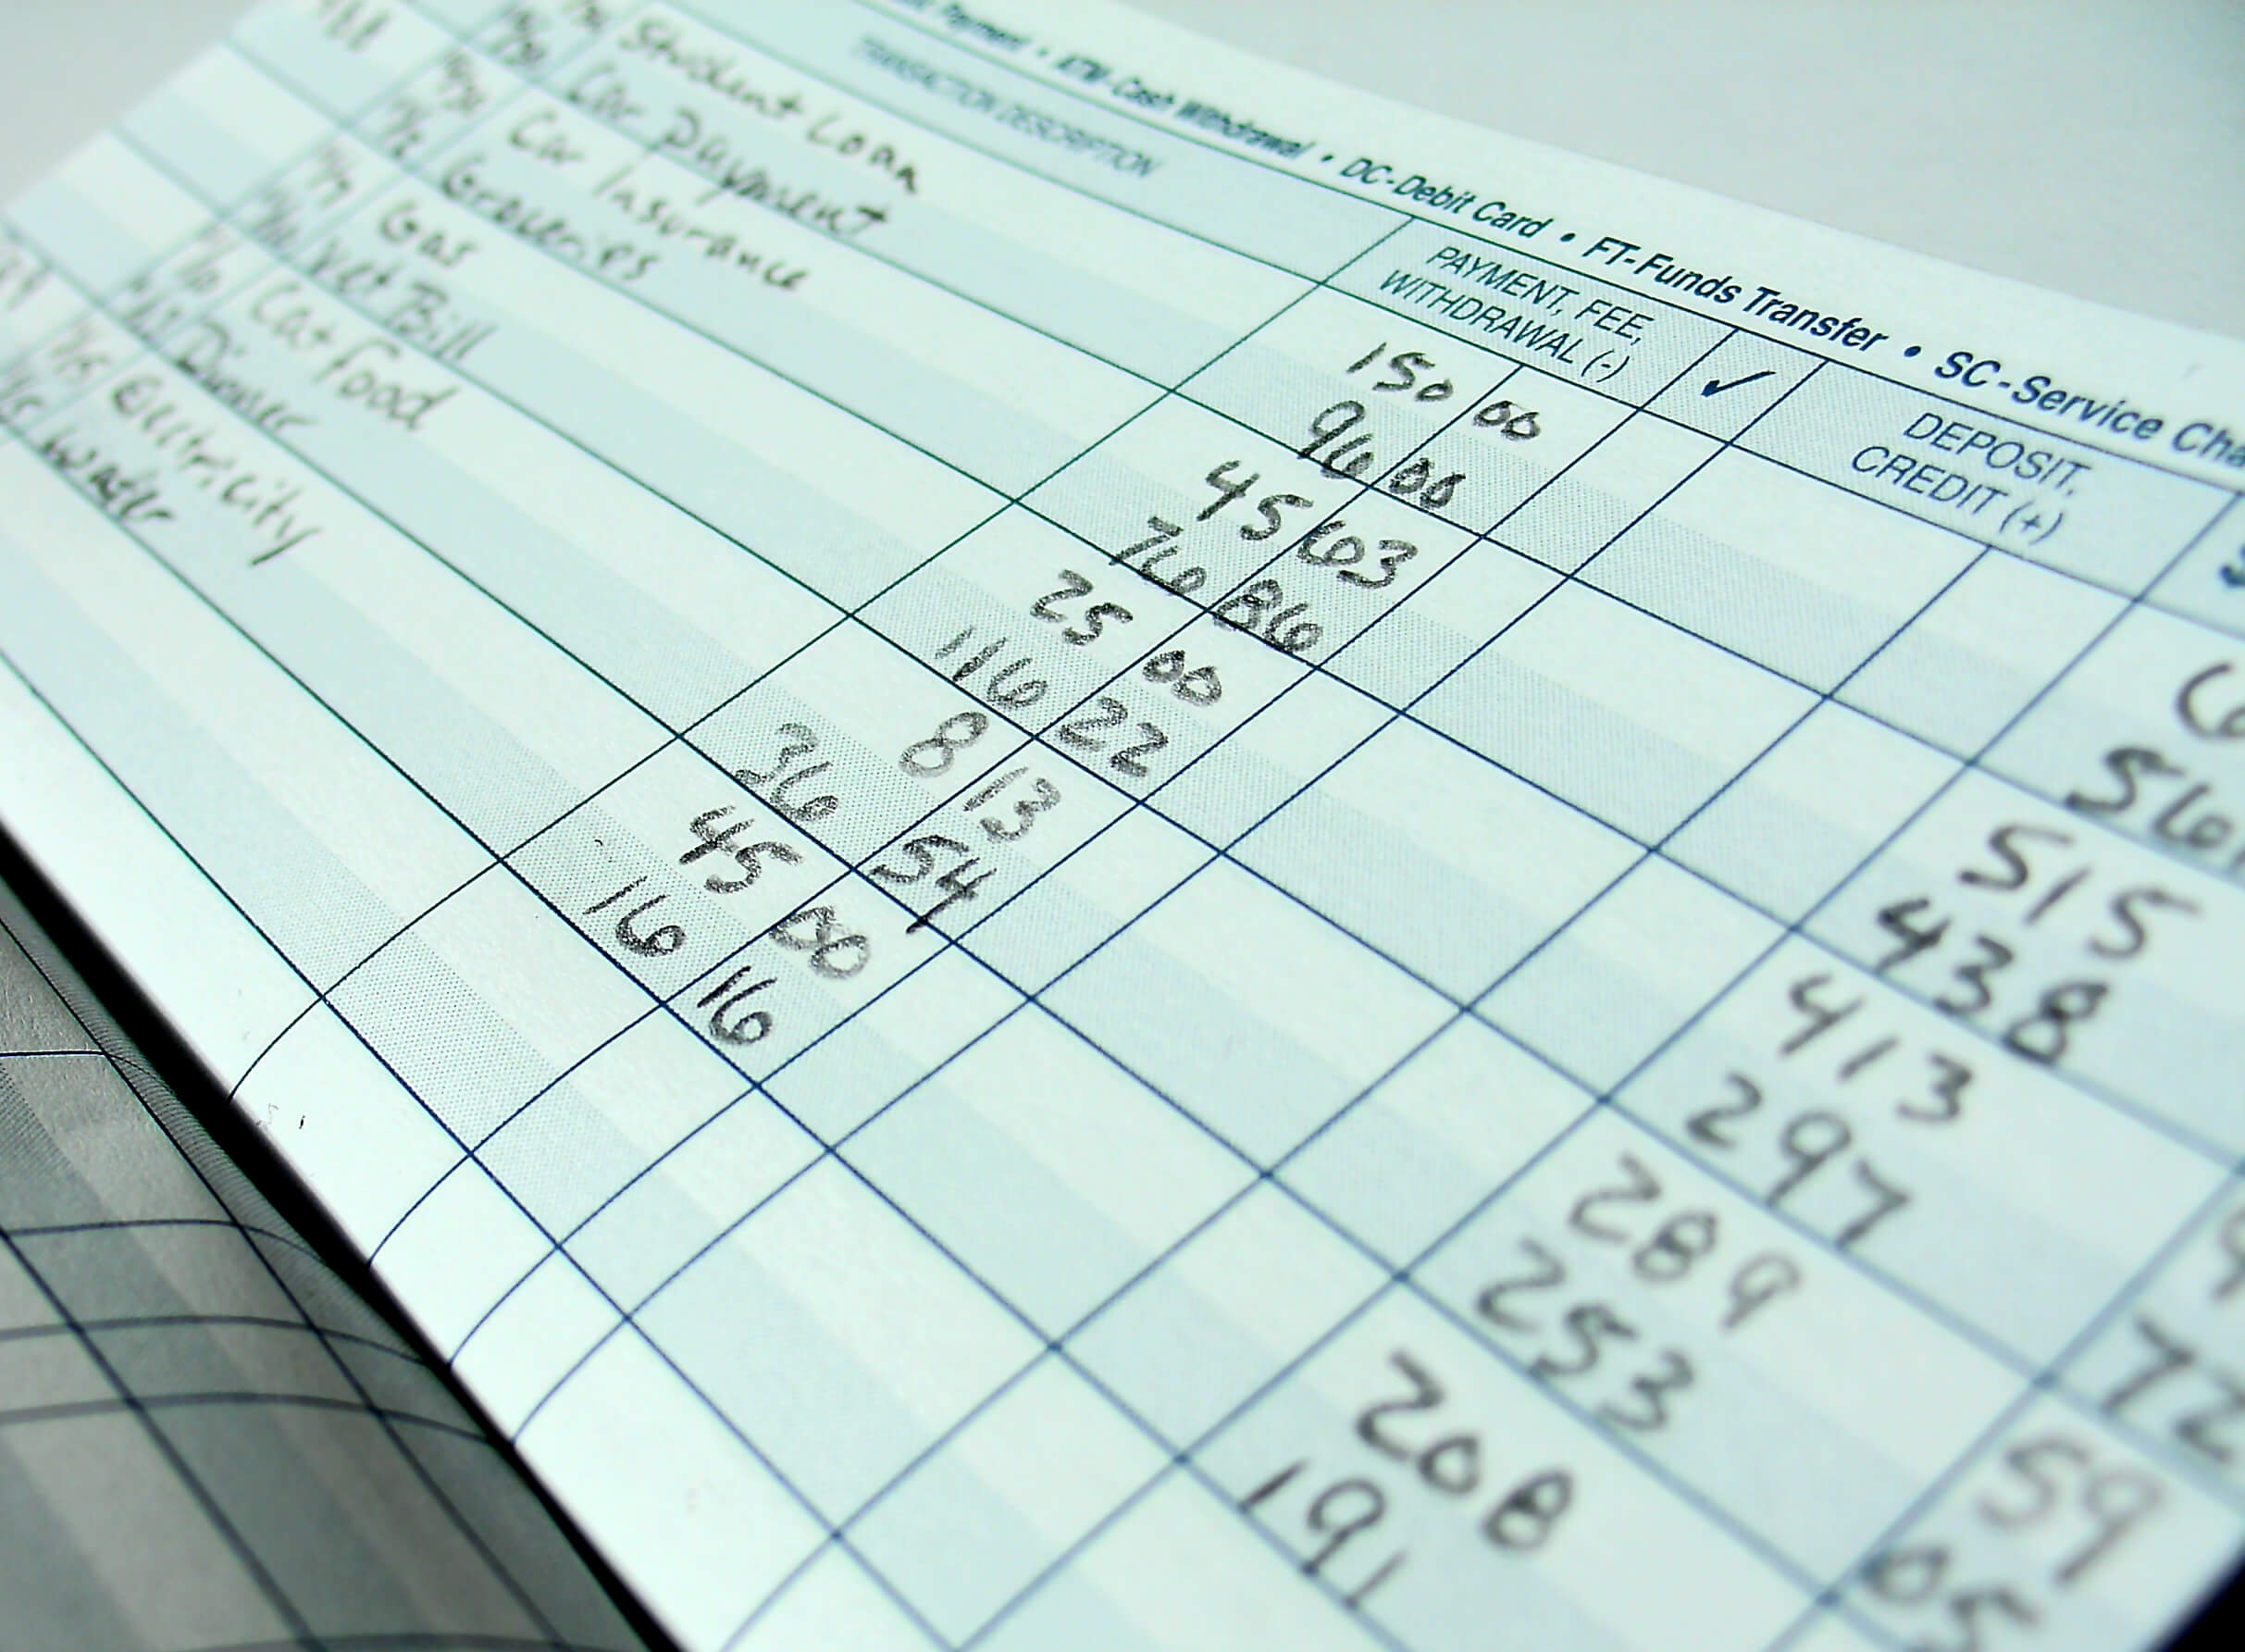
Balancing a Checkbook:
The Simple, Step-by-Step Guide
Balancing a checkbook means recording every deposit, withdrawal, fee, and payment in your register, comparing those entries against your bank statement, and adjusting for any transactions that have not yet cleared. To do it right, calculate your register balance, mark which transactions have cleared, add outstanding deposits and subtract outstanding withdrawals from the bank’s ending balance, and confirm the two adjusted figures match.
Over my 20+ years leading Complete Controller, I’ve watched a single missed subscription or forgotten bank fee quietly snowball into real cash-flow trouble for households and small businesses alike. The good news? The same reconciliation discipline we apply to multimillion-dollar client books works beautifully for your personal checking account. In this guide, I’ll walk you through the exact steps I teach my team, show you how to troubleshoot a stubborn discrepancy, and share the small habits that separate confident money managers from frustrated ones. By the end, you’ll have a repeatable system that protects your money, sharpens your financial awareness, and makes tax time a whole lot easier.
What is balancing a checkbook and how do you do it?
- Balancing a checkbook is matching your personal transaction register to the bank’s statement and explaining every difference between the two.
- Record every transaction immediately—checks, debit purchases, autopay, deposits, fees, and interest.
- Keep a running balance so you always know what’s actually available to spend.
- Mark cleared transactions against the bank statement and list what’s still outstanding.
- Compare your adjusted register balance to the adjusted bank balance; they should match.

What You Need Before Balancing a Checkbook
Before you sit down to reconcile, pull together the records that make the process smooth. A messy desk makes for a messy reconciliation.
Gather these essentials:
- Your most recent bank statement
- Checkbook register, spreadsheet, or budgeting app
- Online banking transaction history
- Receipts for debit purchases and ATM withdrawals
- A list of checks written but not yet cashed
- A calculator or reconciliation worksheet
Why a running ledger matters
Your bank’s displayed balance rarely tells the whole story. A check you wrote last Tuesday or an autopay scheduled for tomorrow may still be in limbo. A running ledger captures what the bank hasn’t caught up with yet.
According to the Consumer Financial Protection Bureau, federal rules require that cash deposits and most electronic payments like direct deposit be available by the next business day—but other deposits may take longer. That lag between what you did and what the bank shows is exactly why your register matters more than the app on your phone.
How to Balance a Checkbook in Seven Steps
Here’s the step-by-step process I recommend for anyone serious about personal finance tracking:
- Start with the correct opening balance from your last successful reconciliation.
- Record every transaction with date, payee, amount, check number, and updated balance.
- Add deposits, subtract withdrawals—one line at a time, no shortcuts.
- Match line by line against the bank statement, marking each cleared item.
- Record bank-only transactions such as fees, interest, and autopay you may have missed.
- List outstanding deposits and withdrawals that haven’t posted yet.
- Compare the adjusted balances using this formula:
Adjusted Bank Balance = Statement Ending Balance + Outstanding Deposits − Outstanding Withdrawals
If that number equals your corrected register balance, you’re reconciled. If not, it’s time to troubleshoot.
Difference between cleared and uncleared transactions
A cleared transaction has been processed by the bank and appears on your statement. An uncleared transaction sits in your register but hasn’t posted yet. For example, if you write a $250 check on the 28th and the recipient doesn’t cash it until the 5th of the next month, that check is a legitimate outstanding withdrawal—not an error.
Checkbook Reconciliation: How to Find and Fix Differences
When numbers don’t match, resist the urge to force a “plug” entry. A discrepancy is a clue, not a nuisance. It usually points to a timing difference, a missing entry, a duplicate, or occasionally a bank error.
Troubleshooting checklist
Work backward from your last reconciled balance and check:
- Addition and subtraction accuracy
- Transactions entered twice or skipped entirely
- Transposed digits and misplaced decimals
- Automatic payments and subscriptions
- Bank fees and interest you forgot to record
- Unfamiliar charges that may signal fraud
That last one matters more than ever. The Federal Trade Commission reported about 1.15 million credit card fraud complaints in 2023, making it the most common form of identity theft. Monthly reconciliation is one of the simplest ways to spot unauthorized charges before they spiral.
A difference of $9.90 may point to a forgotten streaming subscription. A difference of $54.00 could be one missed grocery run. The size of the gap is often your biggest diagnostic clue.
Tired of wondering if your numbers add up? See how Complete Controller makes bookkeeping and bank reconciliation easier, so you can catch costly mistakes and stay confident about your finances.
Balancing a Checkbook Without Mistakes
Accuracy comes from habits, not heroics. The people I see consistently get this right do a few small things exceptionally well.
Build a transaction-entry routine
Enter transactions as they happen, not at month-end. Hold onto receipts until each item appears on your statement. Write descriptions your future self will actually recognize—”Target” is less helpful than “Target – school supplies.”
Reconcile at least monthly
Monthly review limits the volume of transactions you must untangle and gives unauthorized activity nowhere to hide. If you run a business or have an account with heavy activity, weekly check-ins work even better.
Avoid unexplained plug entries
Never balance your register by entering a mystery “adjustment.” Those shortcuts can mask duplicate entries, bank errors, or outright fraud. Consider that in 2012, Bank of America agreed to pay $727 million over claims it reordered debit-card transactions from highest to lowest to maximize overdraft fees. If a bank with that much scrutiny can post questionable charges, your register deserves careful attention every single month.
Digital Tools for Balancing a Checkbook
Paper registers still work beautifully, but digital tools can make frequent tracking easier—as long as you don’t let automation lull you into complacency.
Spreadsheets and banking apps
A simple spreadsheet with columns for date, payee, category, deposit, withdrawal, running balance, and cleared status can automate the math while keeping you in control. Banking and budgeting apps add convenience by syncing posted and pending transactions in real time.
Just remember: automatic syncing can miss cash purchases, duplicate imports, or miscategorize charges. Always review imported entries before marking a reconciliation complete.
When manual review still matters
Technology handles arithmetic. It can’t tell you whether a $42 charge from “SP* GENERIC-LLC” is legitimate or a scam. Human judgment is still required to confirm whether a transaction belongs to you, whether a recurring payment should continue, and whether a discrepancy needs professional help. For more on building strong account ledger records, the Complete Controller team can guide you through it.
What Checkbook Reconciliation Teaches Small-Business Owners
The habits you build balancing a personal checkbook translate directly into stronger business bookkeeping. Business owners should reconcile operating accounts, payroll, credit cards, merchant processing, and loan accounts every month without exception.
Separating personal and business transactions is non-negotiable. Mixing them weakens financial reporting, complicates taxes, and makes bank statement matching nearly impossible. According to Investopedia’s guidance on checkbook balancing, the discipline of regular reconciliation also doubles as an internal control—surfacing duplicate vendor payments, missed deposits, and cash-flow pressure before they become crises.
Conclusion
Balancing a checkbook is simple, but it’s not optional. Record every transaction, keep a running balance, compare your register against the bank statement, and investigate every unexplained difference. Those four habits give you something far more valuable than a tidy number—they give you clarity about where your money actually goes.
In my experience, the real reward of reconciliation isn’t the matching balance. It’s the confidence that comes from knowing your financial story inside and out. That confidence is what fuels smarter spending, bolder saving, and stronger business decisions. Start with your latest statement today, mark every cleared transaction, list what’s outstanding, and correct your register. And when you’re ready for expert help with your personal or business bookkeeping, visit Complete Controller to connect with our team.
Frequently Asked Questions About Balancing a Checkbook
What does it mean to balance a checkbook?
It means comparing your transaction register with the bank’s records, entering any missing items, accounting for outstanding transactions, and confirming that your adjusted register balance matches the adjusted bank balance.
How often should you balance a checkbook?
At least once a month when your bank statement arrives. Weekly reviews are smart for accounts with heavy activity or tight cash reserves.
What is the difference between a checkbook balance and a bank balance?
Your checkbook balance includes everything you’ve recorded—even uncleared items. The bank balance reflects only what the bank has processed, which may lag behind your actual spending commitments.
How do you balance a checkbook if it won’t match?
Verify your opening balance, look for missing or duplicate entries, confirm fees and interest were posted, check for decimal errors, and list every outstanding deposit and withdrawal before comparing the adjusted totals again.
Is balancing a checkbook still necessary with online banking?
Yes. Online banking shows what the bank sees, but it won’t capture uncleared checks, pending charges, or cash transactions. A personal register gives you the full picture.
Sources
- Bankrate. “How to Balance a Checking Account and Why It Matters.” bankrate.com.
- Bray, Chad. “Bank of America Agrees to Pay $727 Million to Settle Overdraft Fee Suit.” The New York Times, Apr. 11, 2012. https://www.nytimes.com/2012/04/12/business/bank-of-america-to-pay-727-million-to-settle-overdraft-suit.html
- Consumer Financial Protection Bureau. “When Your Funds Are Available.” consumerfinance.gov. https://www.consumerfinance.gov/ask-cfpb/when-are-my-funds-available-en-1023/
- Federal Trade Commission. “Consumer Sentinel Network Data Book 2023.” Federal Trade Commission, Feb. 2024. https://www.ftc.gov/reports/consumer-sentinel-network-data-book-2023
- Home Bank. “Eight Simple Steps for Balancing Your Checkbook.” home24bank.com.
- Investopedia. “How to Balance a Checkbook.” Mar. 14, 2022. https://www.investopedia.com/articles/pf/07/checkbook.asp
- Michigan Department of Insurance and Financial Services. “Checking Account: Easy Steps for Balancing Your Personal Checking Account.” michigan.gov.
- Michigan State University Extension. “How to Balance a Checkbook: A Skill for Individuals and 4-H Group Treasurers.” Michigan State University, Feb. 8, 2017. https://extension.msu.edu/
- Regions Bank. “How to Balance a Checkbook: A Guide to Financial Control.” regions.com.
- U.S. Bank. “How to Balance a Checkbook.” usbank.com.
- U.S. News & World Report. “How to Balance a Checkbook.” Nov. 7, 2023. usnews.com.
 About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.



 Brittany McMillen