


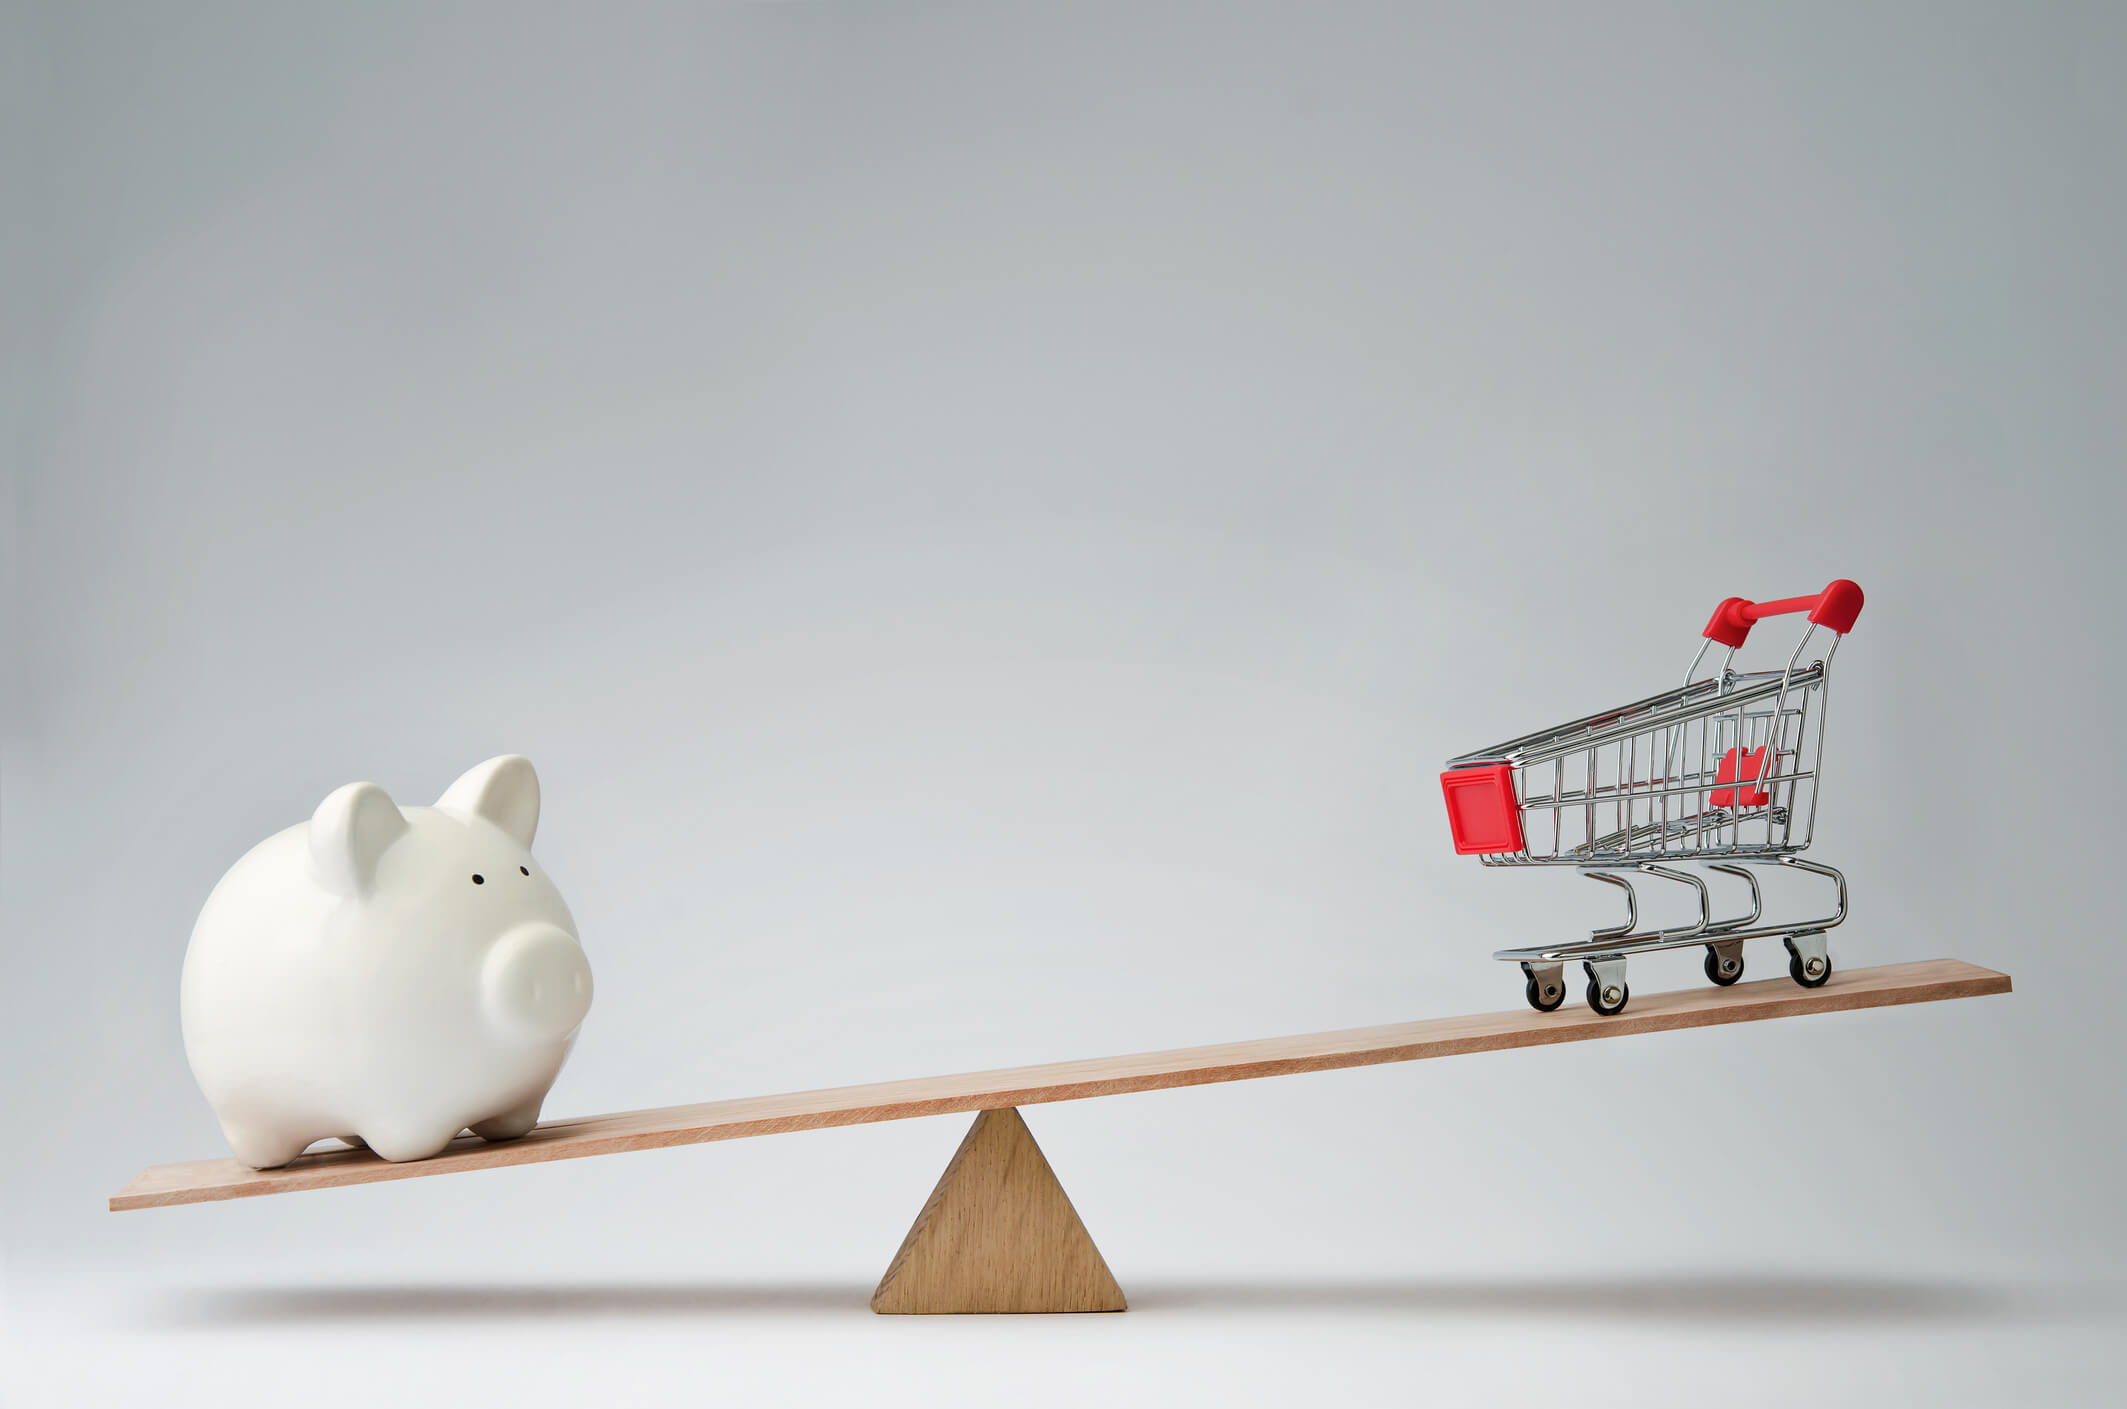
What to Spend vs What to Save:
A Smart Budget Guide for Real Life
When deciding what to spend what to save, spend first on essentials like housing, utilities, groceries, insurance, and minimum debt payments, then save for emergencies, retirement, and defined goals before putting the rest toward discretionary wants. A practical starting framework is 50% or less for needs, up to 30% for wants, and at least 20% for savings or extra debt repayment—but your actual percentages should reflect your income, obligations, and goals.
Here’s something that stops people in their tracks: more than 1 in 3 U.S. adults say they couldn’t cover a $400 emergency expense using cash or savings, according to the Federal Reserve. After more than 20 years running Complete Controller and working with business owners across nearly every industry you can imagine, I’ve learned that budgeting rarely means eliminating every enjoyable purchase. It’s about giving every dollar a job, catching waste before it becomes a habit, and making spending decisions that support both today’s stability and tomorrow’s freedom. In this guide, I’ll walk you through a priority-based framework, percentage models that actually work, a six-step monthly budget, and a decision checklist that keeps your plan on track—whether you’re managing a household, a business, or both.
What is the smartest way to decide what to spend and what to save?
- Spend on essentials and obligations, save for emergencies and goals, and use what’s left for intentional discretionary purchases.
- Essentials include housing, utilities, groceries, transportation, insurance, healthcare, and minimum debt payments.
- Savings should cover emergency reserves, retirement, planned irregular expenses, and measurable short- or medium-term goals.
- Wants are fair game when they fit defined spending limits and don’t crowd out savings goals.
- Review your plan monthly using expense tracking and cash flow management—don’t rely on memory.

What to Spend What to Save: Start With Financial Priorities
Before you argue over coffee runs or streaming subscriptions, protect basic stability first, fund future needs second, and only then expand lifestyle spending. This order matters because it keeps a bad month from becoming a bad year.
Use a three-tier decision framework
Sort every expense into one of three buckets:
- Protect: housing, food, utilities, insurance, healthcare, taxes, minimum debt payments, income-producing tools.
- Progress: emergency fund contributions, retirement savings, high-interest debt payoff, education, planned purchases.
- Enjoy: dining out, entertainment, travel, hobbies, upgrades, convenience spending.
An expense can shift categories based on your life. A reliable vehicle is essential for one household and a lifestyle upgrade for another.
Separate needs, wants, and future needs
Future needs are the sneaky ones—vehicle repairs, insurance renewals, tuition, holidays, annual software fees. Create sinking funds for these instead of treating them as emergencies when they arrive right on schedule.
Calculate your real monthly baseline
Monthly spending capacity = take-home income − fixed expenses − variable essentials − savings contributions. If your income is irregular, budget using a conservative average or your lowest reliable monthly income.
What to Spend What to Save Using a Realistic Percentage Framework
No single rule fits every household, but percentage models give you a starting line. The goal is a structure that flexes with your life.
Paycheck allocation: Start with 50/30/20, then customize
The classic model: 50% needs, 30% wants, 20% savings and extra debt repayment. Bank of America’s budget guide recommends starting with take-home income, listing fixed and variable expenses, and layering in savings.
Alternatives worth considering:
- 60/20/20 when housing, childcare, or healthcare costs run high
- 70/20/10 as a transitional model for tight cash flow
- Pay-yourself-first, where savings transfers happen the moment income arrives
What percentage of income to save
Savings targets should be progressive. Start with any consistent amount, build an initial emergency reserve, then work toward 15%–25% of income for savings and investments when your cash flow allows. If your employer offers a retirement match, capture it—leaving matching dollars on the table is leaving part of your paycheck behind.
Spending limits: Guardrails, not deprivation
Set monthly caps on restaurants, shopping, entertainment, travel, subscriptions, personal care, and convenience purchases. A weekly discretionary allowance makes limits easier to follow than a once-a-month reckoning.
How to Create a Monthly Budget That Actually Works
A budget only works when it’s repeatable. Here’s the six-step process I recommend to clients at Complete Controller.
A six-step monthly budget process
- Calculate reliable take-home income.
- List fixed expenses and minimum debt payments.
- Review the prior two or three months of bank and card statements.
- Estimate variable essentials like groceries, fuel, and healthcare.
- Assign amounts to savings goals and irregular expenses.
- Set limits for discretionary categories and compare planned vs. actual spending.
Expense tracking: Catch small purchases and annual bills
Small recurring charges distort budgets fast—app subscriptions, delivery fees, bank fees, premium memberships, unused software, annual renewals. Build a one-page annual-expense worksheet and divide each yearly cost by 12.
Cash flow management: Budget by timing, not just totals
A healthy monthly surplus can still produce overdrafts if bills land before paychecks. The Consumer Financial Protection Bureau found that overdraft and non-sufficient funds fees are most common in the days right after paydays, when bills cluster together. Timing matters as much as totals.
- Match bill due dates to paydays when possible
- Keep a bill-pay account with a minimum balance
- Forecast large withdrawals a week ahead
- Separate business and personal accounts if you own a business
For deeper help, our team at Complete Controller’s cash flow services can map your inflows and outflows week by week.
What to Spend What to Save When Money Is Tight
If standard percentages feel out of reach, you’re not failing—you’re starting from a different line. Prioritize protection over perfection.
Emergency fund: Build protection before lifestyle expansion
Use a staged approach:
- First target: a small cash buffer for immediate disruptions
- Second target: one month of essential expenses
- Longer-term target: three to six months, depending on job stability, dependents, and income volatility
Given that over a third of U.S. adults can’t cover a $400 emergency, a modest starter fund protects you from the first crack in the sidewalk. More on building reserves is available from the FDIC Consumer Resource Center.
Where to cut expenses to save money
Tackle high-impact categories first: unused subscriptions, insurance or telecom plans you can renegotiate, dining and delivery, vehicle costs, impulse shopping, and high-interest debt. One large recurring cut usually beats dozens of tiny ones.
What not to cut first
Protect health insurance, necessary maintenance, retirement contributions up to your employer match, compliance-related professional services, and any debt payment below the required minimum.
Spending vs Saving Strategy: Decide Which Purchases Are Worth It
Go beyond “needs vs. wants” and evaluate the real value and timing of what you buy.
Calculate the total cost of ownership
For big purchases, include price, financing interest, maintenance, insurance, taxes, replacement parts, and the opportunity cost of money that could’ve been saved or invested.
Spend on quality when it prevents larger costs
Higher upfront spending can be smart on safety equipment, reliable business technology, preventive maintenance, professional bookkeeping support, and durable items used daily. “Cheapest” and “best value” aren’t always the same thing—read more in our guide to smart business spending.
Guardrails beat vague goals
The New York Times profiled a six-figure couple who still lived paycheck to paycheck until they tracked expenses and discovered over $3,000 a month vanishing into restaurants and convenience spending. After setting category limits and automating savings, they began consistently saving and paying down debt. Vague “spend less” goals don’t work. Specific category caps do.
Give every savings goal a deadline
Monthly contribution = (goal amount − current savings) ÷ months remaining. Write each goal with an amount, target date, account, and review date. For retirement guidance, see the U.S. Department of Labor’s retirement resources.
What to Spend What to Save as a Small-Business Owner
Business budgeting follows the same logic, but the stakes multiply. Revenue is not the same as spendable profit.
Separate business and personal cash flow
Use dedicated business banking, predictable owner compensation, tax reserves, payroll reserves, and separate operating and savings accounts. Forecast cash flow monthly and set approval rules for discretionary business purchases.
Evaluate every recurring expense quarterly
For software, contractors, and vendors, review monthly price, setup costs, transaction fees, integration costs, cancellation terms, time saved, and revenue enabled. Explore our bookkeeping and advisory services for a structured review process.
Use three business cash buckets
Operating expenses, tax and compliance reserves, and profit/emergency/growth reserves. After a strong revenue month, resist the urge to lift personal spending immediately—let the reserves catch up first.
Conclusion: Give Every Dollar a Purpose
The strongest what to spend what to save strategy isn’t about following a perfect percentage. It’s about funding essentials, protecting against emergencies, paying down expensive debt, investing for the future, and spending intentionally on what matters most.
In my two decades leading Complete Controller, I’ve watched business owners gain real confidence when they stop treating bookkeeping as backward-looking recordkeeping and start using financial information to make decisions. Start by tracking one full month, identify your three largest controllable expenses, automate one savings transfer, and review your results at the same time every month. For help organizing business finances, improving cash-flow visibility, and building a reliable bookkeeping process, visit Complete Controller and talk with our team.
Frequently Asked Questions About What to Spend What to Save
What should I spend money on first?
Prioritize housing, utilities, groceries, healthcare, insurance, transportation, taxes, and minimum debt payments. Then fund emergency savings, retirement, and defined goals before expanding discretionary spending.
How much money should I save each month?
A common starting target is 20% of take-home income, though a smaller consistent amount beats an unrealistic one. When cash flow allows, work toward 15%–25% for combined savings and investments.
Is the 50/30/20 budget rule still useful?
Yes, as a starting framework. It assigns roughly 50% to needs, 30% to wants, and 20% to savings or extra debt payments. High housing costs, irregular income, or caregiving duties may require customization.
Should I save or pay off debt first?
Keep all minimum payments current, build a small emergency buffer, then prioritize high-interest debt while maintaining retirement contributions at least up to any employer match. Interest rates and tax considerations guide the exact sequence.
How can I stop overspending?
Track every purchase, set category limits, automate savings on payday, cancel unused recurring charges, and add a 48-hour waiting period for nonessential purchases. A weekly 15-minute review catches problems early.
Sources
- Bank of America. (2026). “Your Guide to Creating a Budget Plan.” Better Money Habits. https://www.bettermoneyhabits.bankofamerica.com
- Board of Governors of the Federal Reserve System. (May 2024). “Economic Well-Being of U.S. Households in 2023.” https://www.federalreserve.gov/publications/2024-economic-well-being-of-us-households-in-2023-expenses.htm
- Consumer Financial Protection Bureau. (March 2022). “Data Spotlight: Checking Account Overdraft.” https://www.consumerfinance.gov/data-research/research-reports/data-spotlight-checking-account-overdraft/
- Fidelity. (2025). “How to Save Money: 8 Ways to Save.” Fidelity Learning Center. https://www.fidelity.com
- Financial Consumer Agency of Canada. (2017, updated 2025). “Case Study: Tackling Problem Spending.” https://www.canada.ca/en/financial-consumer-agency.html
- First Citizens Bank. (2022). “The Ultimate Guide to Making a Budget.” https://www.firstcitizens.com
- Lieber, Ron. (July 19, 2019). “A Lesson From a Six-Figure Couple Who Still Lives Paycheck to Paycheck.” The New York Times. https://www.nytimes.com/2019/07/19/your-money/budgeting-high-income-paycheck-to-paycheck.html
- U.S. Bank. (2026). “9 Easy Ways to Save Money.” U.S. Bank Financial IQ. https://www.usbank.com
- U.S. Consumer Information. “Make a Budget.” Consumer.gov. https://www.consumer.gov/content/make-budget-0
- U.S. Department of Labor. “Retirement Plans, Benefits and Savings.” https://www.dol.gov/general/topic/retirement
- U.S. Federal Deposit Insurance Corporation. “Cash and Emergency Savings.” https://www.fdic.gov/consumer-resource-center/cash-emergency
- Vanguard. (2025). “10 Ways to Start Saving Money.” https://www.vanguard.com
 About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.



 Brittany McMillen