Mobile Home Park Opportunity:
Profit Potential & Insights
A mobile home park opportunity can deliver recurring lot-rent income, operationally driven appreciation, and attractive tax advantages—but your actual returns depend on purchase price, occupancy, infrastructure condition, local regulations, financing terms, and the quality of management you put in place. Before you write a check, verify the park’s net operating income, normalize every expense, inspect physical systems, confirm rent sustainability, stress-test debt service, and model the downside carefully rather than trusting the broker’s projected cap rate.
In my 20-plus years as founder and CEO of Complete Controller, I’ve had a front-row seat to thousands of small-business and real estate deals across nearly every industry you can name—and I’ve watched promising investments unravel because the books were sloppy, expenses were understated, or someone confused cash flow with profit. This guide walks you through how to evaluate a park like a professional investor: the return math, the due diligence checklist, the financing options, the resident dynamics, and the bookkeeping controls that protect your profit after closing. By the end, you’ll have a repeatable framework you can apply to any park you look at this year.
What is a mobile home park opportunity, and how can investors evaluate its profit potential?
- A mobile home park opportunity is an investment in land and infrastructure leased to residents who typically own their manufactured homes, with profit coming from lot rent, ancillary income, occupancy gains, and expense control.
- The return metrics that matter most are NOI, cap rate, cash-on-cash return, DSCR, IRR, and equity multiple.
- The strongest deals pair stable occupancy with measurable upside—below-market rents, vacant pads, utility recapture, or weak management.
- Verify rent rolls, taxes, insurance, utilities, repair history, zoning, and infrastructure before you make an offer.
- A park can still be a bad deal if the price is inflated, infrastructure is failing, or local rules cap your ability to raise rent.
Why a Mobile Home Park Opportunity Appeals to Real Estate Investors
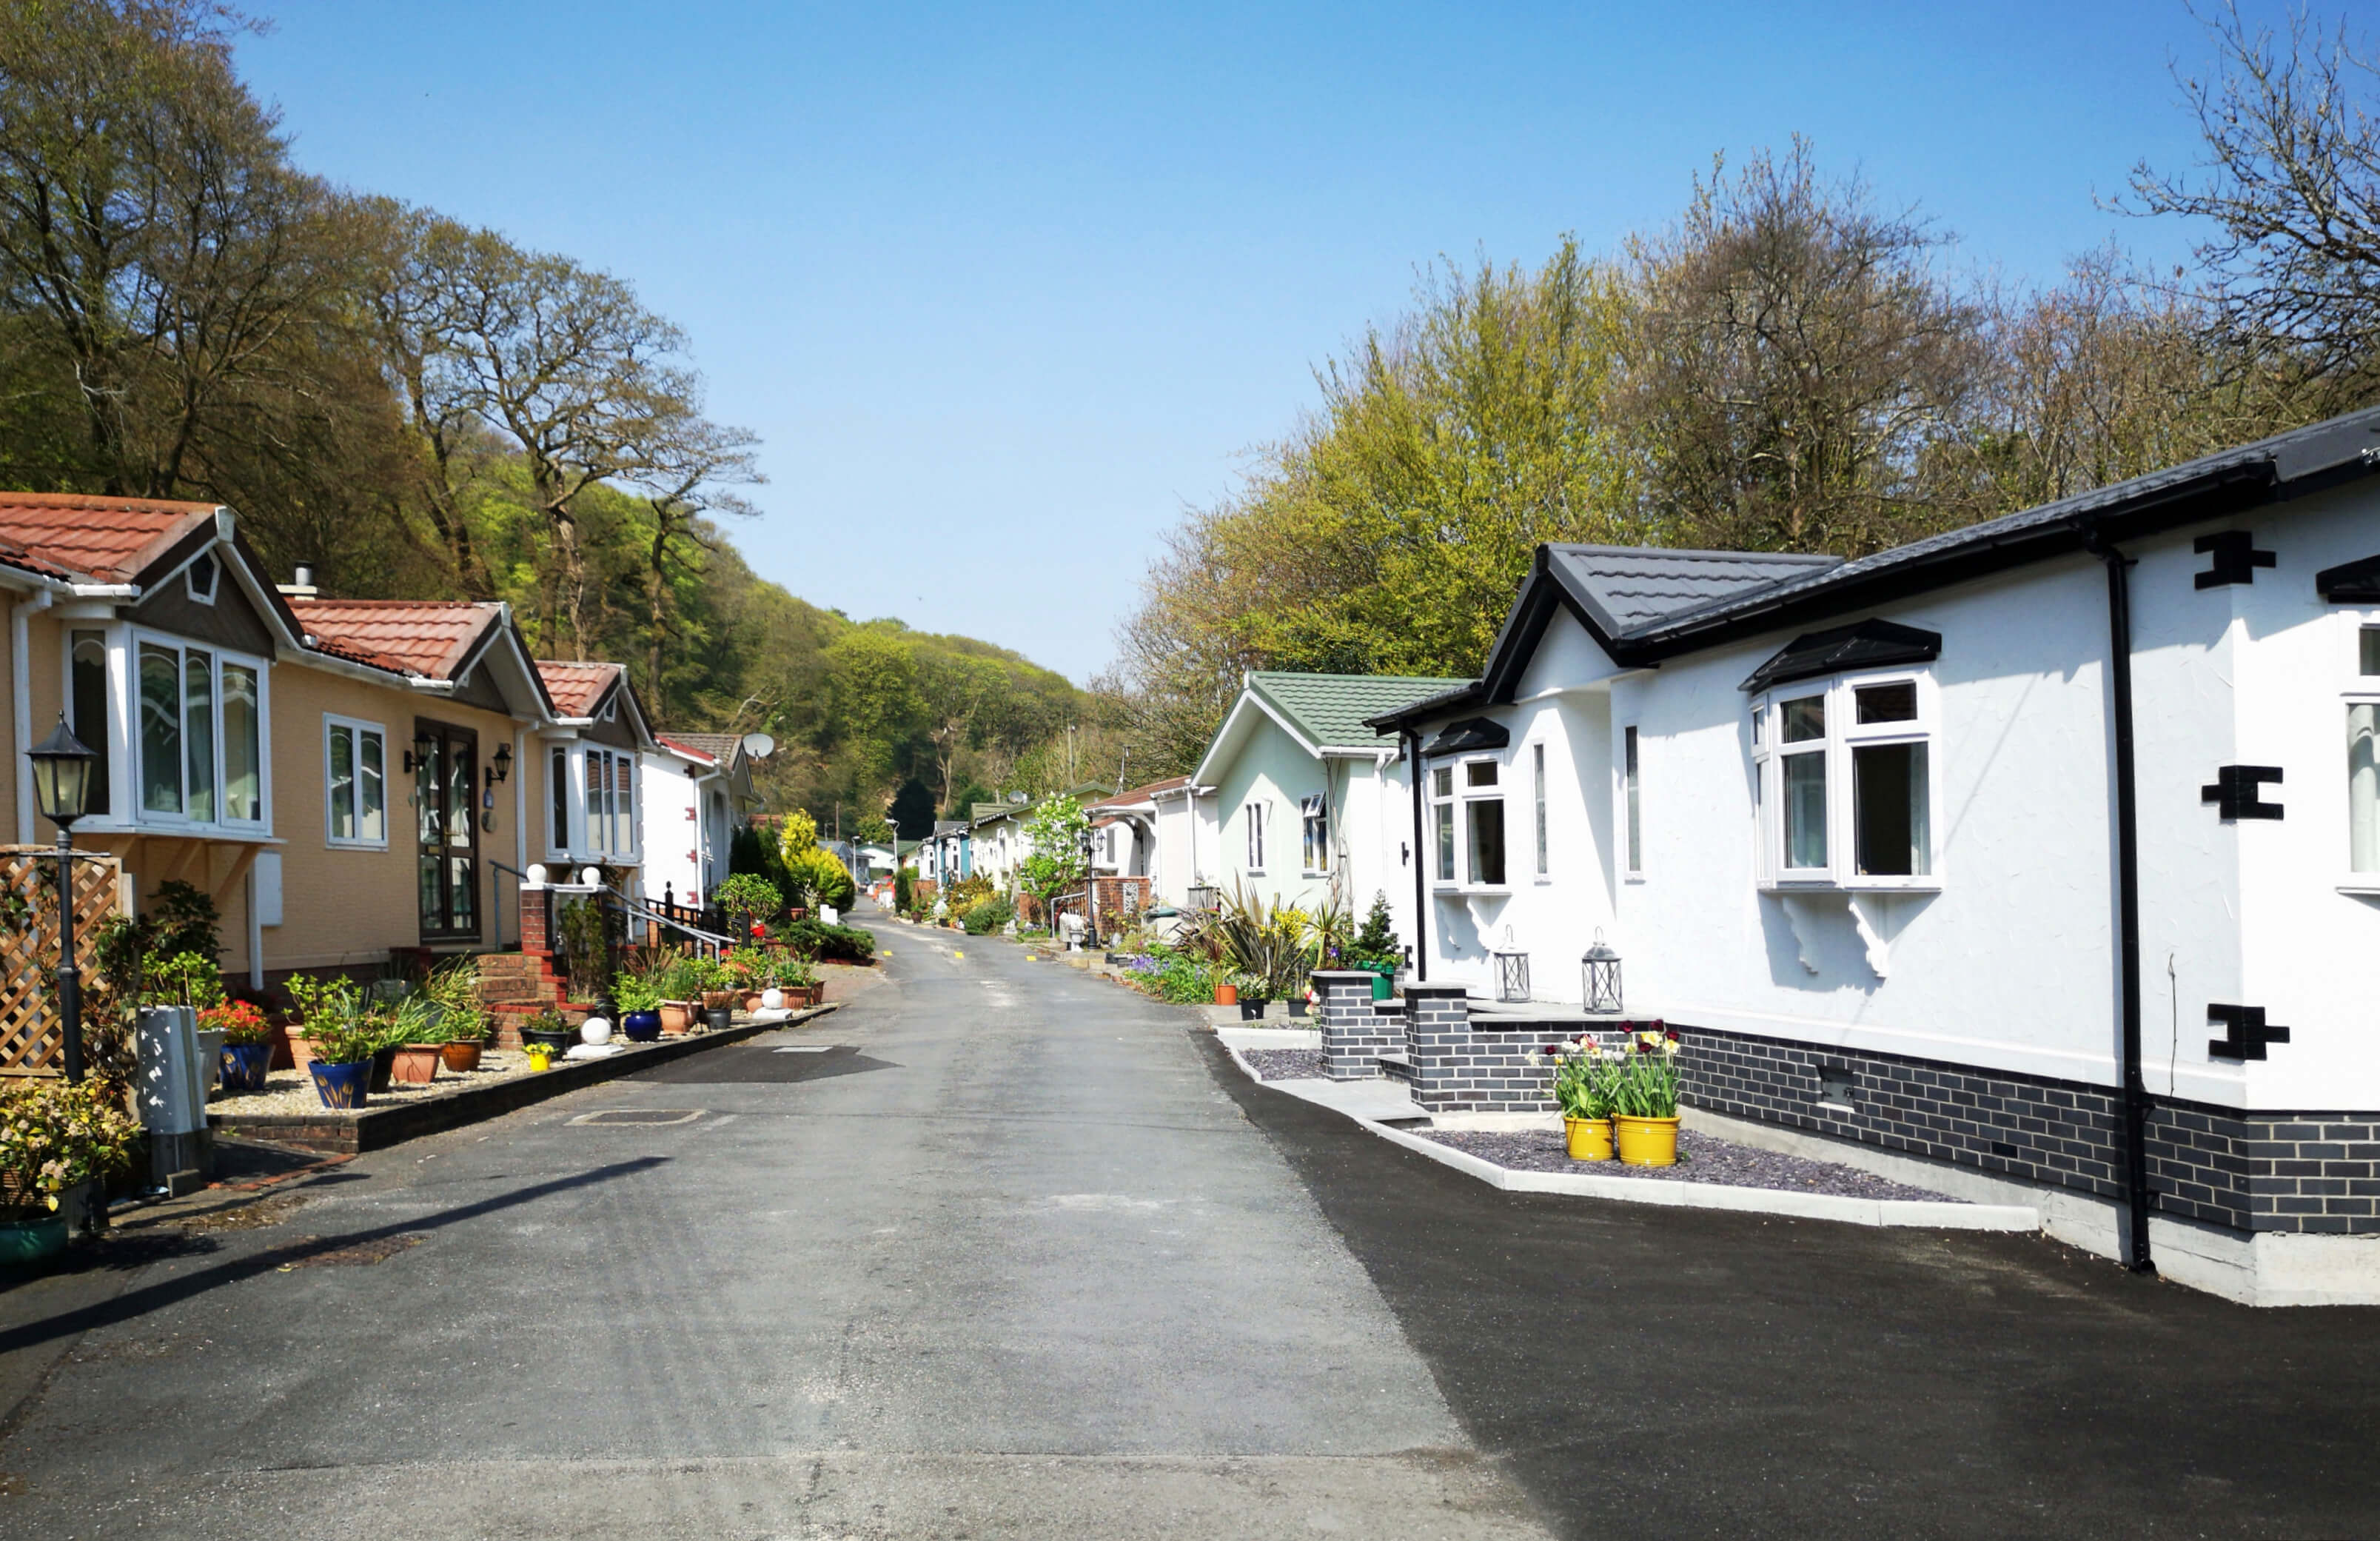
Mobile home parks hold a unique spot in commercial real estate because the resident usually owns the home while you own the land underneath. That separation often reduces turnover costs and heavy maintenance compared with traditional multifamily, where the landlord owns every unit.
Resident ownership also creates stickiness. Moving a manufactured home can cost $5,000 to $10,000 for a short move—and up to $15,000 or more for longer distances, sometimes more than the home itself is worth [3]. That economic reality tends to produce longer tenancies and more predictable collections than apartment rentals.
The mobile home park income model
The core revenue source is lot rent—the monthly fee a resident pays for use of the homesite and shared infrastructure. A healthy park typically layers in several additional income streams:
- Utility reimbursements or resident-paid utilities
- Income from park-owned homes
- Application, late, and transfer fees (where legally permitted)
- Laundry, storage, and parking income
- New-home placement fees
A rent roll showing full occupancy doesn’t automatically mean the owner collected every billed dollar. Always reconcile gross potential rent against actual bank deposits.
Why sffordable housing demand matters
Manufactured housing is one of the largest sources of unsubsidized affordable housing in America. In 2022, roughly 6.5 million occupied housing units—about 5% of all U.S. housing—were manufactured homes [1]. The cost advantage is dramatic: in 2024, a new manufactured home averaged $87.90 per square foot versus $166.49 for a new site-built home [2].
That affordability supports demand, but it doesn’t eliminate risk. Compare your target park’s lot rent against local wages, nearby apartment rents, and competing manufactured housing communities before assuming rent growth is automatic.
Stabilized vs. Value-add strategies
Pick your lane before you shop:
- Stabilized: high occupancy, predictable collections, limited deferred maintenance, lower upside, higher pricing
- Value-add: vacant pads, below-market rents, weak collections, deferred maintenance, bigger returns but real execution risk
“Value-add” should never mean “the seller says rents can go up.” It means you’ve identified a specific, legal, affordable path to higher NOI.
How to Underwrite a Mobile Home Park Investment Before You Buy
Start with verified history, not the broker’s pro forma. Rebuild the operating statement from tax returns, bank statements, and utility bills—then calculate your own numbers.
The metrics that matter
- Net Operating Income (NOI) = Effective Gross Income − Operating Expenses
- Cap Rate = NOI ÷ Purchase Price
- Cash-on-Cash Return = Annual Pre-Tax Cash Flow ÷ Total Cash Invested
- DSCR = NOI ÷ Annual Debt Service
- IRR and Equity Multiple for timing and total return
A low-expense year or omitted capital needs can make a cap rate look great while hiding real liabilities. Normalize everything.
A practical example
Picture a $4,000,000 park with verified NOI of $300,000—a 7.5% going-in cap rate. With a $2,600,000 loan at $190,000 annual debt service, pre-tax cash flow lands at $110,000 on roughly $1,500,000 in equity, delivering about a 7.3% cash-on-cash return. Now model the upside (occupancy rising from 85% to 94%, lawful utility recapture, gradual rent moves to market) alongside the downside (insurance spikes, a sewer failure, interest rates up at refinance). A credible deal survives the conservative case.
For deeper reporting discipline on these numbers, I recommend reviewing business bookkeeping essentials before you underwrite anything.
Real estate opportunities look better when the numbers are clear. Complete Controller helps property owners and investors track cash flow, expenses, and profitability with confidence. Explore bookkeeping for property management and real estate.
Mobile Home Park Due Diligence: What to Verify Before Closing
Due diligence is where the opportunity in marketing materials meets the reality in the records.
The due diligence checklist
- Current rent roll and three years of operating statements
- Bank statements, deposit records, and delinquency reports
- Lease forms, resident files, and eviction records
- Utility bills, reimbursement records, and tax bills
- Insurance policies and claims history
- Vendor contracts and payroll
- Capital expenditure history and maintenance logs
- Code violations and litigation records
- Environmental reports, survey, title, and zoning confirmation
- Water, sewer, electrical, road, and drainage records
Make regular bank reconciliation part of the diligence—your purchase price depends on it.
Buying a mobile home park with existing residents
Residents are part of the operating system. Review lease terms, payment histories, informal side agreements, pending evictions, home ages, local notice requirements for rent increases, and rules on home removal or resale. The Consumer Financial Protection Bureau outlines resident protections you’ll want to understand before closing.
Infrastructure can make or break the deal
Order independent inspections, video sewer scopes, water testing, and professional repair estimates. A park with great occupancy and a failing septic field is a liability wearing a cash-flow mask.
How to Find and Finance a Mobile Home Park for Sale
Sourcing combines brokers, direct owner outreach, lender contacts, and industry conferences. Build a market scorecard ranking population growth, lot-rent-to-income ratios, competition, insurance costs, and exit liquidity.
Financing options compared
| Financing Source | Potential Advantage | Key Risk |
| Agency loan | Long-term, competitive pricing | Strict underwriting |
| Local bank | Relationship flexibility | Shorter term, balloon risk |
| Seller financing | Negotiable, fast | Higher price demanded |
| Bridge loan | Funds stabilization | Higher cost, refinance risk |
| Equity partner | Reduces capital need | Dilutes control |
Avoid using optimistic future NOI to justify leverage, and always maintain an ideal liquidity position separate from your operating reserves.
How to Improve Returns Without Compromising Resident Stability
The best operators grow NOI through operations, not just rent hikes. Standardize leases, add online rent payment, bill utilities accurately, renegotiate vendor contracts, infill vacant pads, and enforce rules consistently.
Bookkeeping controls that protect profit
- Separate property-level bank accounts
- Monthly rent-roll-to-deposit reconciliation
- Delinquency aging reports
- Class-based tracking for utilities, repairs, and capex
- Monthly budget-to-actual reporting
- Documented owner draws and intercompany transfers
Case study: Mobile acres
Sunrise Capital Investors acquired Mobile Acres, a 100-lot community in Ashtabula, Ohio, at 94% occupancy, with 74 of 94 occupied homes owned by residents [4]. The operator pursued gradual rent increases, utility recapture, vacant-lot infill, and community improvements. The lesson: value creation came from several moderate moves, not one aggressive rent hike. A separate Three Pillar Communities example reports a $2.8M Meadowlands Estates acquisition later refinanced at a $6.35M valuation—an operator-reported result, not a typical outcome [5].
Managing the Risks in a Mobile Home Park Opportunity
Every park carries regulatory risk (zoning, rent control, eviction rules), infrastructure risk (aging utilities, flooding), market risk (local employment, affordability), and exit risk (buyer pool, interest rates). Model longer hold periods, build capital reserve schedules with timing and cost, and test rent increases against local income—not just competitor pricing.
Final Thoughts
A mobile home park opportunity is an operating business attached to real estate. The most durable investments combine verified cash flow, sustainable rents, functional infrastructure, conservative financing, and measurable operational improvements—backed by books that tell the truth every month.
What I’ve learned building Complete Controller is simple: reliable decisions start with reliable data. Reconcile the rent roll to deposits, normalize every expense, quantify infrastructure obligations, and document exactly how NOI will grow. When you’re ready for property-level reporting and financial controls built for serious investors, visit the experts at Complete Controller.
Frequently Asked Questions About Mobile Home Park Opportunity
Is a mobile home park a good investment?
It can be, when the park has sustainable demand, verified collections, manageable infrastructure, appropriate financing, and experienced management. Returns vary widely by market, price, and execution.
How profitable is a mobile home park?
Profitability depends on occupancy, lot rents, operating expenses, capital needs, and financing. Industry sources often cite national cap rates in the 7%–10% range, though individual properties can perform far above or below that.
What is the biggest risk of owning a mobile home park?
Infrastructure failure—especially private water and sewer systems—combined with rising insurance costs and excessive leverage. Identify these risks during due diligence, not after closing.
How much money do I need to buy a mobile home park?
Expect to need 20%–30% down plus closing costs, capital reserves, and working capital. On a $2M park, that’s often $500,000–$700,000 in equity before reserves.
Can I buy a mobile home park with existing residents?
Yes, and most acquisitions include them. Review leases, payment histories, home ownership status, and local notice rules before closing, and plan a resident communication strategy for day one.
Sources
- U.S. Census Bureau. (2023). American Housing Survey (AHS) 2023 Table Creator—Manufactured (Mobile) Home (Units), 2022 estimates. https://www.census.gov/programs-surveys/ahs/data/interactive/ahstablecreator.html
- Manufactured Housing Institute. (2024). Manufactured Homes: Your Best Housing Value. https://www.manufacturedhousing.org/manufactured-homes-your-best-housing-value/
- Sullivan, Esther. (May 22, 2019). In Mobile Home Parks, Residents Say They’re Under Siege. NPR. https://www.npr.org/2019/05/22/725459653/in-mobile-home-parks-residents-say-theyre-under-siege
- Sunrise Capital Investors. Selected Case Studies. https://www.sunrisecapitalinvestors.com
- Three Pillar Communities. Three Pillar Communities: Home. https://www.threepillarcommunities.com
- Complete Controller. Business Bookkeeping Essentials. https://www.completecontroller.com/business-bookkeeping-essentials/
- Complete Controller. Importance of Reconciling Your Accounting Statements Regularly. https://www.completecontroller.com/importance-of-reconciling-your-accounting-statements-regularly/
- Complete Controller. Ensure Ideal Liquidity Position. https://www.completecontroller.com/ensure-ideal-liquidity-position/
- HUD User. (September 9, 2020). Manufactured Housing Community Affordability. https://www.huduser.gov/portal/pdredge/pdr-edge-featd-article-090920.html
- Investopedia. Net Operating Income and Cap Rate. https://www.investopedia.com/terms/c/capitalizationrate.asp
- Consumer Financial Protection Bureau. Manufactured Housing Communities: What Renters Need to Know. https://www.consumerfinance.gov/about-us/blog/manufactured-housing-communities-what-renters-need-to-know/
 About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.


 Brittany McMillen