How Much to Tell Kids About Money:
Family Finance Tips That Actually Work
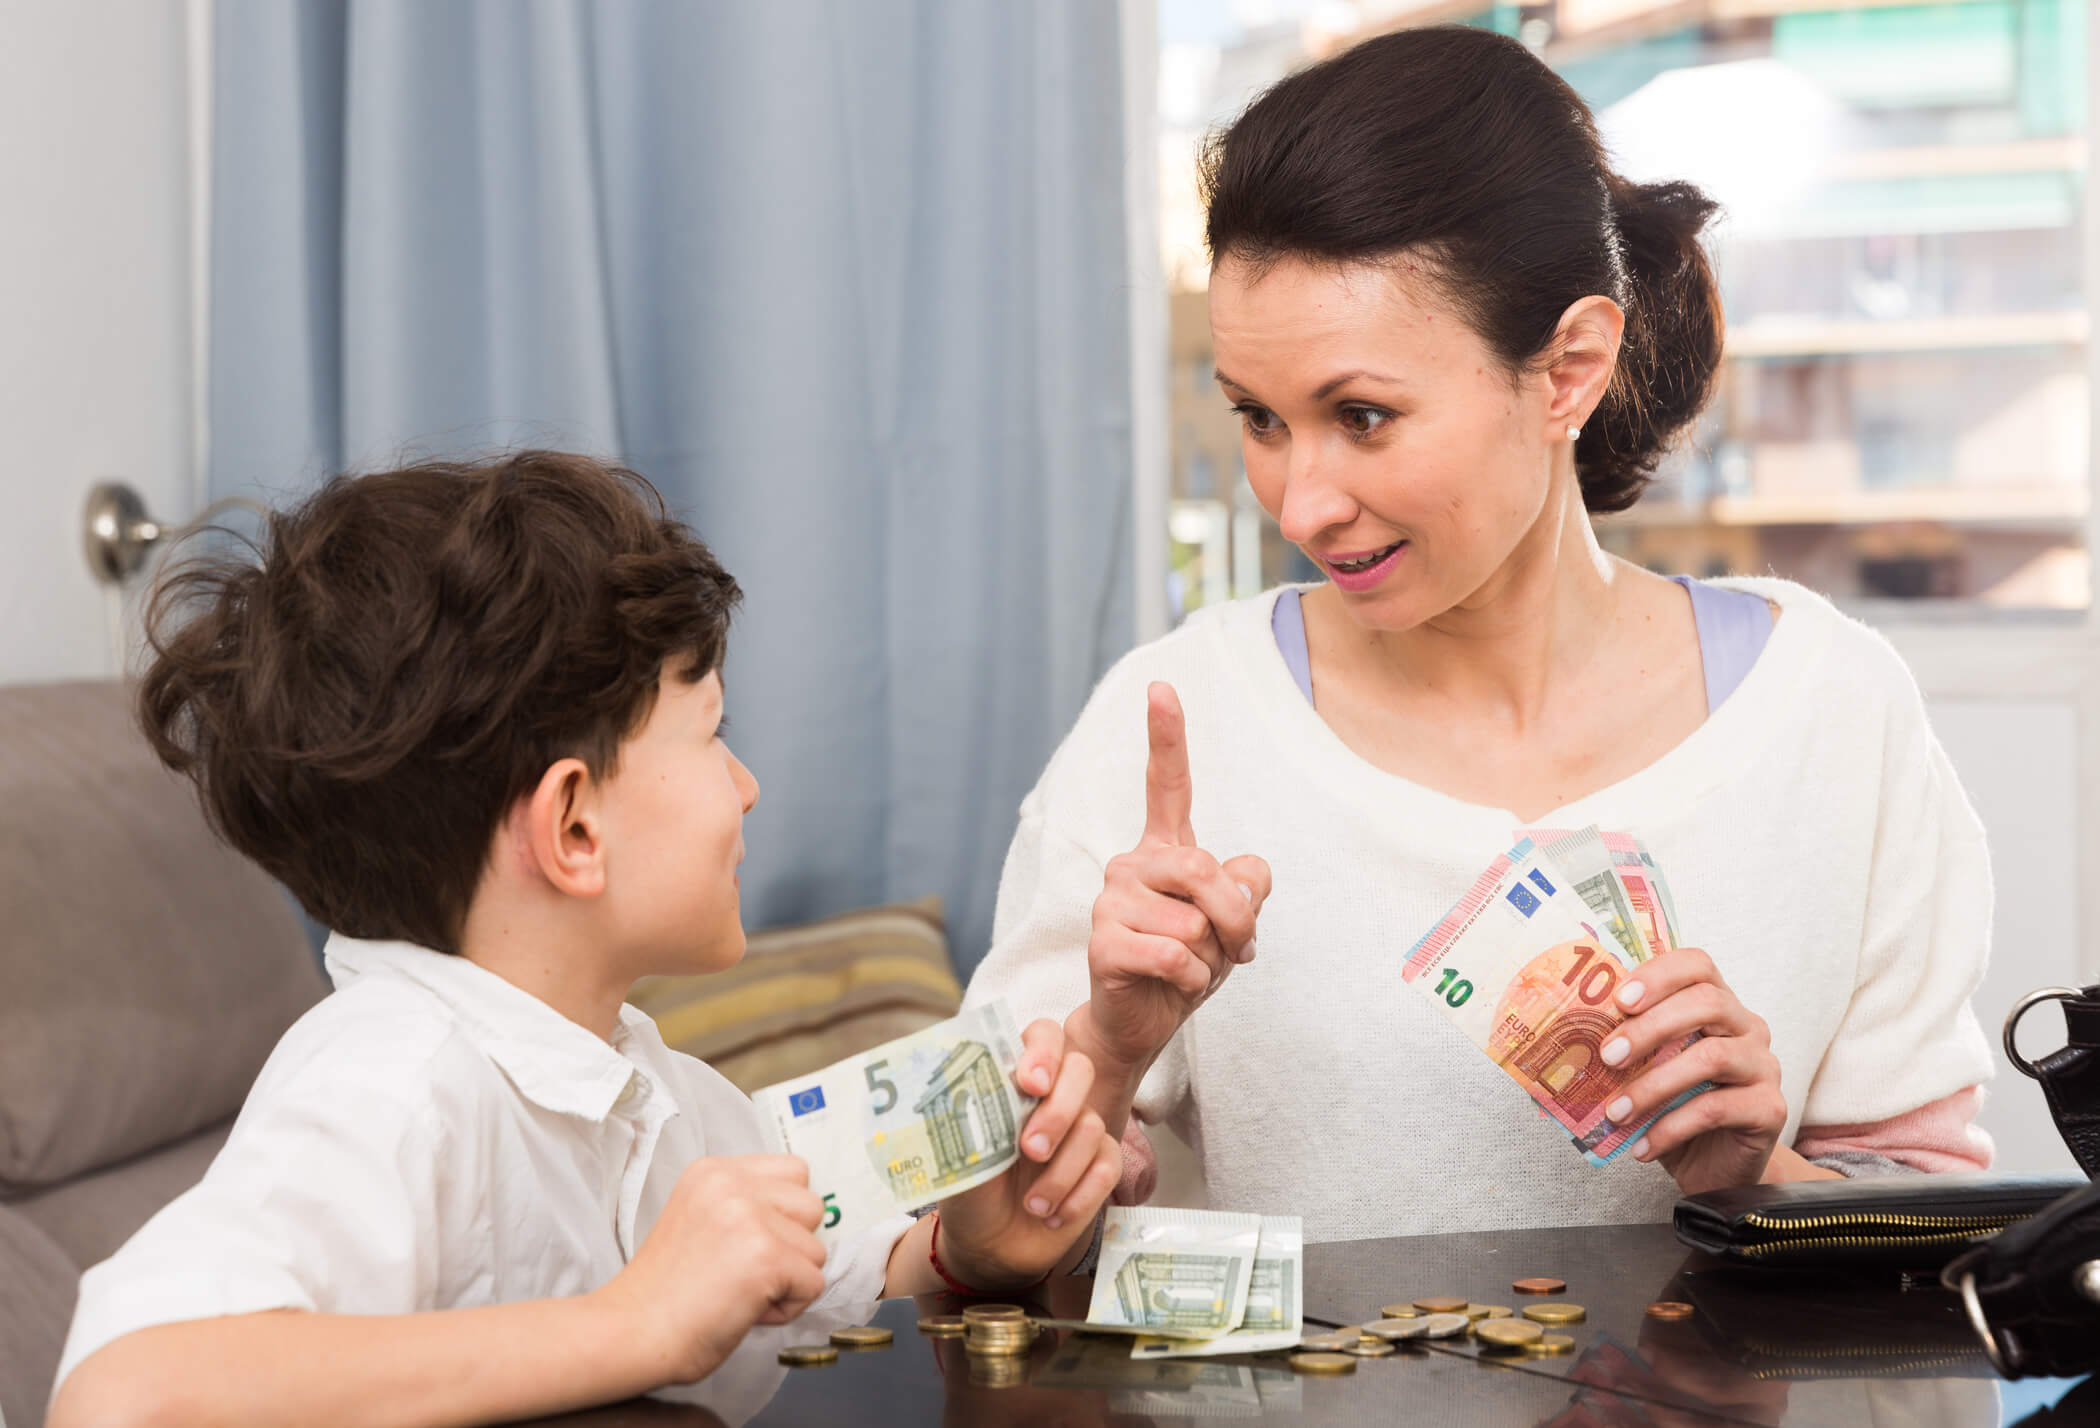
How much to tell kids about money depends on their age and maturity—share enough to teach them earning, spending, saving, giving, and trade-offs, but never so much that they carry adult financial stress. Start with simple truths in early childhood (money is exchanged for things, adults work to earn it), add allowance and savings goals in elementary school, introduce budgeting and banking to tweens, and prepare teens for paychecks, taxes, credit, and independence. The rule is progressive disclosure: reveal more as their comprehension grows.
After more than 20 years leading Complete Controller and working alongside business owners across nearly every industry, I’ve noticed something surprising—the families who raise financially confident kids use the same principles that keep small businesses healthy: honest numbers, calm conversations, and consistent review. In this article, I’ll show you exactly how much to tell kids at each stage, how to talk about family finances without oversharing, how to build practical saving habits, and how to handle sensitive money conversations during divorce, illness, or job loss. You’ll leave with a real plan you can use this week.
How much should you tell kids about money, and when?
- Short answer: Tell kids the truth in age-appropriate language, covering earning, spending, saving, sharing, and trade-offs—more detail as they mature.
- Ages 3–5: Concrete examples, visual jars, and simple choices between two items.
- Ages 6–10: Allowance, savings goals, needs vs. wants, and basic budgeting.
- Tweens: Household budgets, comparison shopping, banking, and interest.
- Teens: Paychecks, taxes, credit, debt, insurance, and long-term planning.
Why the Right Amount of Money Talk Matters
Children who hear nothing about money often invent their own beliefs—and those beliefs are usually wrong. Children who hear too much too soon absorb anxiety they can’t process. Both extremes create adults who struggle with money.
A national survey by the Federal Reserve Bank of Minneapolis found that three in four U.S. teens say they want more financial education, and many report learning about money from their parents. Translation: kids are asking for these conversations. They just need us to keep them calm, useful, and connected to real life.
A simple filter before you share
Before revealing a financial detail, ask yourself:
- Does my child need this to make a decision?
- Can I explain it without transferring fear?
- Is it age-appropriate?
- Does it teach a useful skill?
- Can I answer follow-up questions honestly?
If the answer is yes across the board, share it. If not, keep it in the “adult matter” category.
How Much to Tell Kids at Each Age
Money lessons should evolve from concrete experiences to abstract decisions. The Consumer Financial Protection Bureau’s research shows children can be developmentally ready to save as early as age five.
3–5-Year-old child: Start with a kid-friendly explanation
A 3-5-year-old child can grasp that money is exchanged for goods and adults work to earn it. Keep it short and tangible—use a clear jar or three labeled containers for spend, save, and share.
The classic Stanford delay-of-gratification study found that children who could wait for a bigger reward later had stronger outcomes as adults. That’s what a savings jar quietly teaches: patience pays off.
6–10-Year-old child: Build saving and budgeting habits
A 6-10-year-old child can handle simple budgets, savings goals, and trade-offs. Practical activities include:
- A small, predictable allowance divided into spend/save/share
- A visible savings target the child tracks weekly
- Comparing two products at the grocery store
- Paying for a small purchase and counting change
Repeated practice matters. The “I Can Save” program with 4th graders showed that structured, age-appropriate saving practice produced measurably stronger habits than no program at all.
Tweens: Introduce household budgeting and banking
Tweens are ready for limited family planning conversations—like how much is set aside for groceries or a vacation—without seeing every account balance. Good topics: unit pricing, savings interest, digital payment security, gross vs. take-home pay, and how subscriptions quietly drain a budget.
Teenagers: Connect money to independence
Teens need practical prep for adulthood: reading a pay stub, opening a bank account, understanding credit utilization, comparing job offers, and spotting scams. Give them honest information—but don’t make them carry mortgage stress or marital disputes. Our small business financial resources include budgeting templates teens can adapt for a first apartment.
How Much to Tell Kids About Family Finances
You don’t have to choose between secrecy and total transparency. Share principles, relevant facts, and decisions that affect the child.
What younger kids need to know
- Why one activity is chosen over another
- Why some purchases must wait
- That “not today” doesn’t mean “never”
A calm script: “That toy isn’t part of today’s plan. We’re saving for groceries and your school trip.”
What older kids and teens may need to know
Older kids can appropriately learn how the household budget is organized, which expenses are fixed, why emergency savings matter, and how taxes shape take-home pay—especially when tied to a real decision like choosing a car or college.
What parents should keep private
Kids should never be confidants for adult financial distress. Keep private: marital money arguments, collection calls, exact debt figures, and housing fears without a plan. Privacy is not deception. You can say, “That’s an adult matter, but I’ll tell you what affects you.”
How to Teach Kids Budgeting, Saving, and Spending
Kids learn money through repeated practice, not lectures.
Use a three-part system
Divide money into spend, save, and share. Proportions can flex—the point is showing money serves multiple purposes. For older kids, introduce the 50/30/20 framework as a teaching model, not a rigid rule.
Let children experience small consequences
If a child spends everything before a fun outing, resist replacing the money. Try: “You used what you had. Let’s decide what to save for next and how long it may take.”
Allowance without a formula
A common starting point is roughly $1 per year of age per week, but adjust based on maturity, what the allowance covers, and family budget. The lesson matters more than the number.
How Much to Tell Kids About Money During Difficult Family Situations
Money conversations get sensitive during divorce, illness, job loss, or death. Kids deserve truth about what affects them—without adult weight.
How much information to share with kids about divorce
Explain what’s changing in daily life, where they’ll live, and that they aren’t responsible. The American Psychological Association’s guidance on divorce and children emphasizes protecting kids from adult conflict. Never ask a child to choose sides or share private financial details about the other parent.
Should you tell kids the truth about illness?
Yes—matched to their developmental level. Use accurate words, answer the question asked, and skip false reassurance. If illness changes spending: “We’re making fewer extra purchases while we pay for medical care. Your basic needs are covered.”
How much should you tell kids about death?
Be honest and direct. Avoid confusing phrases like “went to sleep.” Financial details—inheritance, funeral costs, estate disputes—usually belong in adult conversations unless an older teen is directly affected.
How much to tell kids about money during job loss
Say what’s true without promising nothing will change. Try: “My job changed, so we’re reviewing our budget. The adults have a plan, and I’ll tell you about anything that affects your activities.”
Better money habits start with clearer numbers. Complete Controller helps business owners simplify bookkeeping, understand their finances, and plan what comes next.
Building Age-Appropriate Communication Into Family Life
The best money lessons happen in ordinary moments.
Storytelling and everyday examples
A kids story can illustrate delayed gratification—like saving for a bike over several weeks. Storytelling for children works when it includes a recognizable goal, a real obstacle, a choice, and a visible result.
Follow the child’s curiosity
Child curiosity is your best opening. When a kid asks how a card can buy something, a kid friendly explanation might be: “A debit card moves money from our bank account. It doesn’t create extra money.” If money conversations start triggering real anxiety or family conflict, a child psychologist or family therapist can help.
A Founder’s Perspective on Family Money Lessons
Running Complete Controller has taught me one thing above all: money decisions get clearer when information gets organized. The same is true at home.
Track before you teach
Show kids that budgeting starts with knowing what comes in and goes out—whether that’s an allowance or a first paycheck.
Separate facts from feelings
Teach kids to distinguish “we’re worried” from “we have no options” and “we’re choosing not to buy this” from “we can’t ever afford it.” That single skill will serve them for life.
A family money conversation plan for this week
- Pick one real situation (grocery run, saving for an outing).
- Explain the decision in one or two sentences.
- Ask what your child notices or would choose.
- Let them practice with a small amount of money.
- Review without shame.
Conclusion
How much to tell kids about money grows with them: visible examples for the youngest, hands-on saving for elementary kids, real budgeting for tweens, and honest prep for adult life for teens. The goal isn’t full disclosure—it’s building judgment, confidence, and habits that last.
In my two decades helping businesses organize their financial lives, I’ve seen the same truth apply at the dinner table: clarity beats perfection every time. Start with one small lesson this week. For more expert guidance on organizing your family or business finances, visit the team at Complete Controller.
Frequently Asked Questions About How Much to Tell Kids
At what age should you start teaching kids about money?
Start during preschool with simple concepts—money is exchanged for things, adults work to earn it. Add saving, budgeting, banking, and credit gradually as your child matures.
How much allowance should a child receive?
A common starting guideline is about $1 per year of age per week, but adjust based on your household budget, your child’s maturity, what the allowance is expected to cover, and whether chores are tied to it.
Should parents tell children about family debt?
Share what affects your child’s life or a decision they must make, but don’t make them responsible for adult debt. Explain the relevant trade-offs calmly and in age-appropriate language.
What is the best way to teach kids to save money?
Give them a specific goal, make progress visible with a jar or chart, and let them save a portion of any money they receive. Pairing patience with a visible outcome is the winning formula.
Should children know how much their parents earn?
Younger kids need to understand priorities, not exact income. Older teens may benefit from seeing how gross pay, taxes, and major expenses shape available money—especially when tied to real planning.
Sources
- American Psychological Association. “Divorce and Child Custody.” https://www.apa.org/topics/divorce-child-custody
- Consumer Financial Protection Bureau. “Building Blocks to Help Youth Achieve Financial Capability.” https://www.consumerfinance.gov/consumer-tools/money-as-you-grow/
- Elliott, William B., Jr., and Samuel A. Friedline. (2013). “You Save, We Match: The ‘I Can Save’ Program and Savings in Children.” Children and Youth Services Review. https://doi.org/10.1016/j.childyouth.2013.03.001
- InCharge Debt Solutions. (September 15, 2026). “Teach Kids to Save.” https://www.incharge.org
- JPMorgan Chase. (September 23, 2026). “How to Teach Kids About Money.” https://www.chase.com
- Mischel, Walter, Yuichi Shoda, and Monica L. Rodriguez. (May 26, 1989). “Delay of Gratification in Children.” Science. https://doi.org/10.1126/science.2658056
- Mutual of Omaha. (August 17, 2026). “Financial Literacy for Kids: How to Teach Money Skills.” https://www.mutualofomaha.com
- National Endowment for Financial Education. (2019). “How 5-Year-Olds Learn About Money.” https://www.nefe.org
- National Financial Educators Council. (April 3, 2024). “How to Teach Financial Literacy to Kids.” https://www.financialeducatorscouncil.org
- National Cancer Institute. “Talking with Children.” https://www.cancer.gov/about-cancer/coping/adjusting-to-cancer/support-groups/talking-with-children
- PenFed Credit Union. (July 14, 2025). “Teaching Your Kids to Have a Healthy Relationship with Money.” https://www.penfed.org
- Regions Bank. (January 31, 2025). “Teaching Kids About Money: Making Sense of Financial Concepts.” https://www.regions.com
- Ziegler, Laura. (May 23, 2023). “Survey: Most Teens Want More Financial Education.” Federal Reserve Bank of Minneapolis. https://www.minneapolisfed.org/article/2023/survey-most-teens-want-more-financial-education
 About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.


 Brittany McMillen