


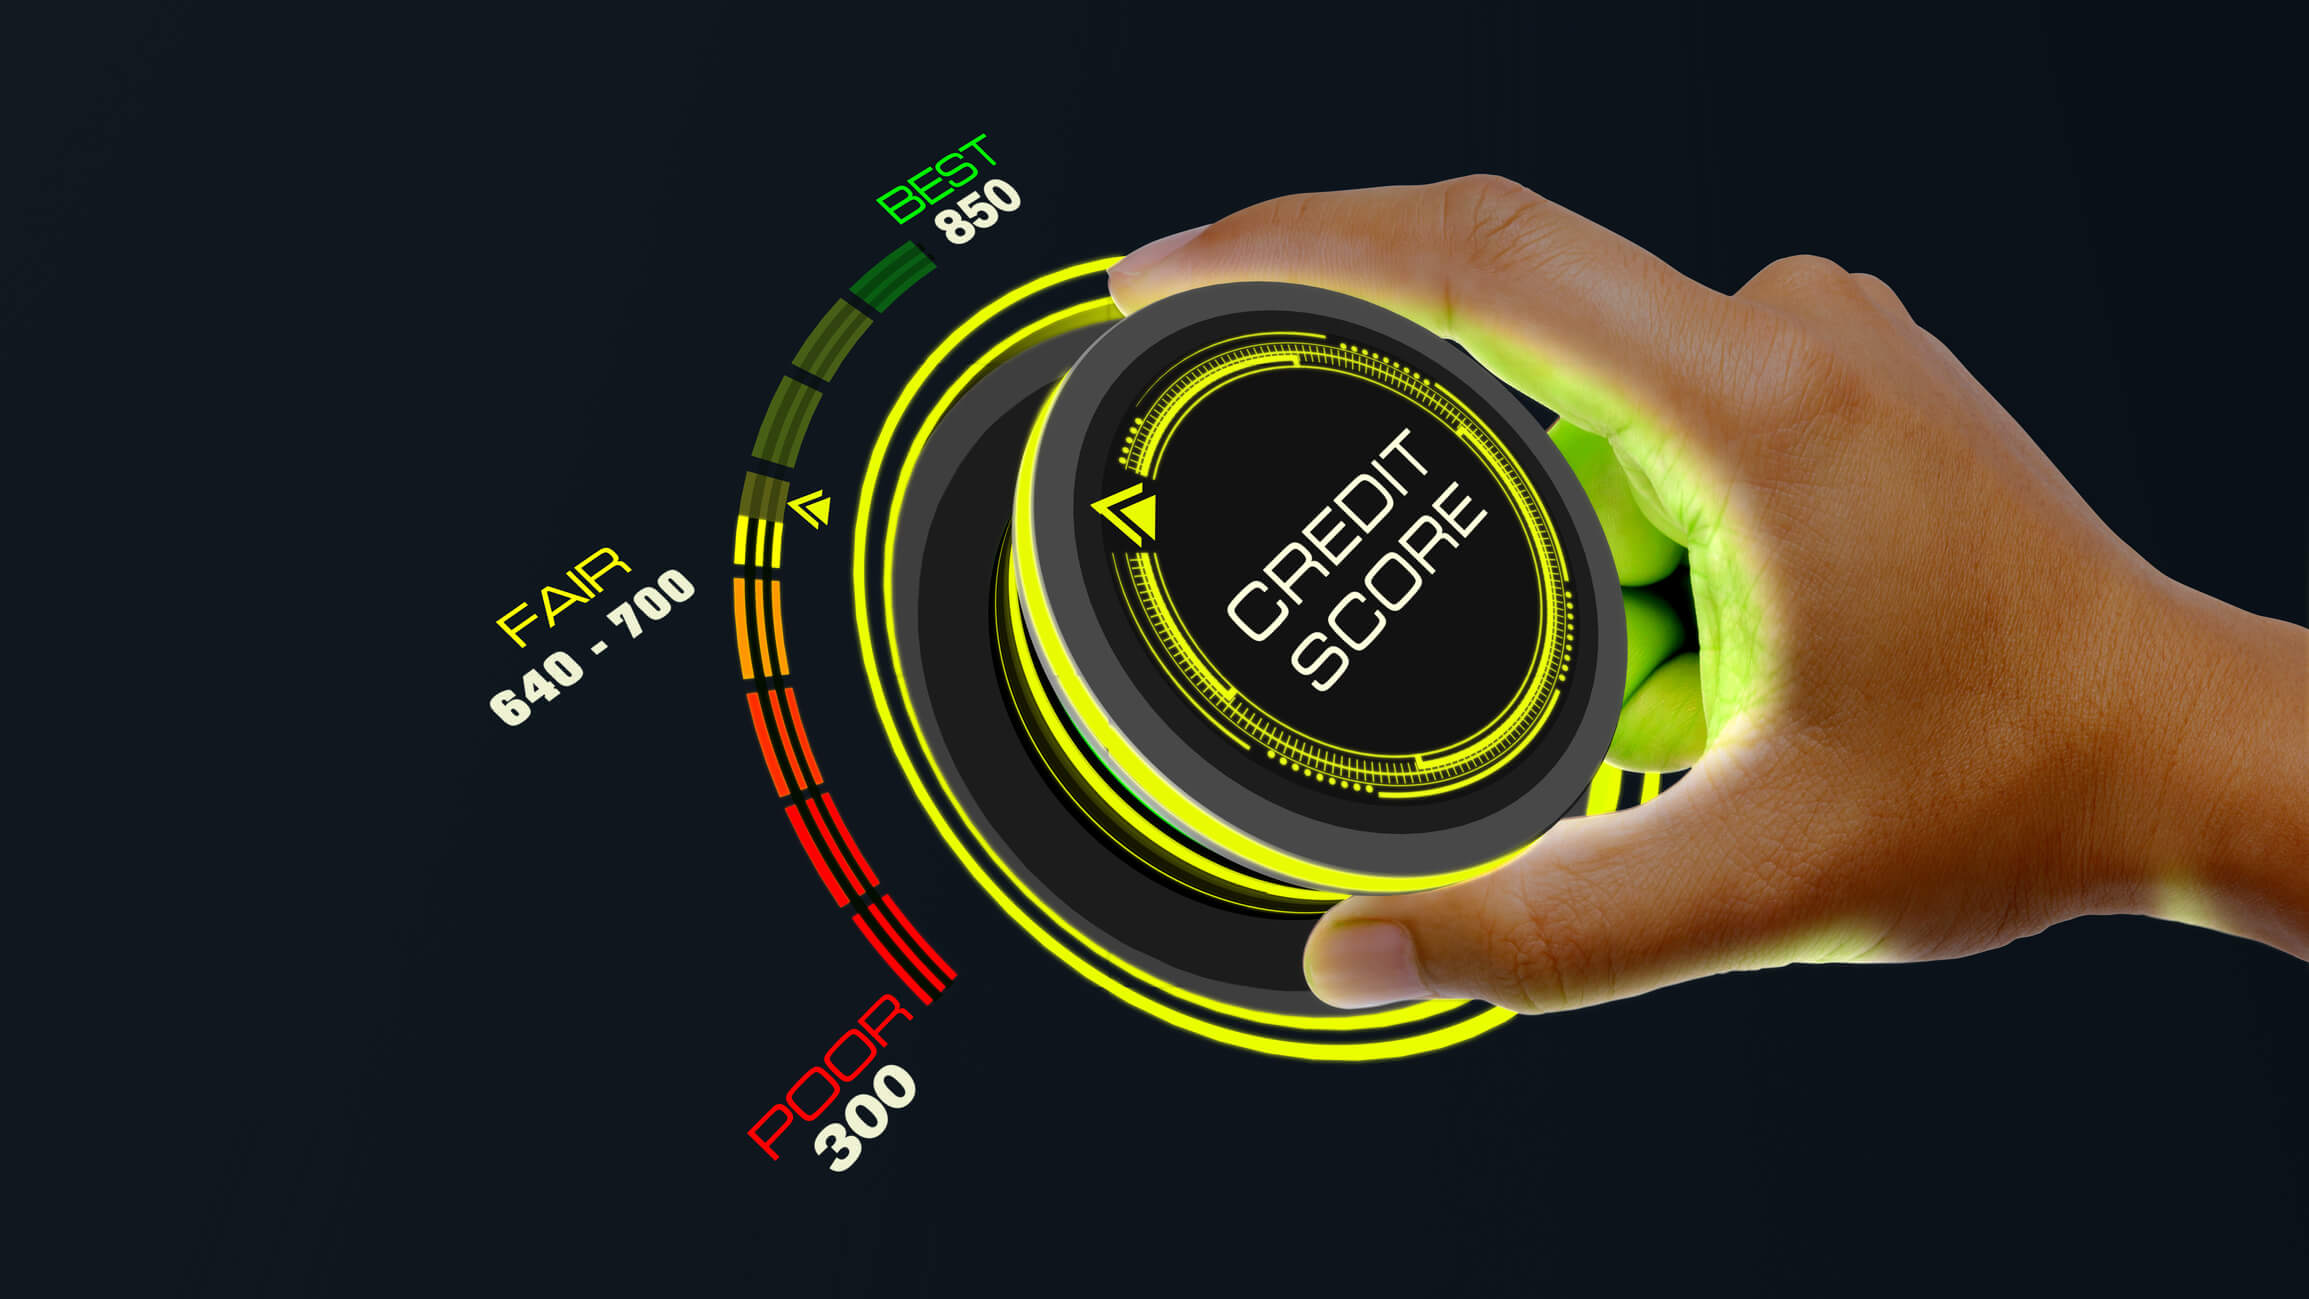
How To Improve Credit Score:
Fast, Proven Steps
To improve credit score quickly and sustainably, pay every account on time, lower your credit card balances below 30% of each limit, dispute inaccurate items on your credit reports, avoid unnecessary credit applications, and keep older accounts open when they carry no fee. Reducing revolving balances can lift your score as soon as your lender reports the new balance, while rebuilding payment history takes consistent, repeated effort over several months.
In my 20+ years leading Complete Controller, I’ve worked with thousands of entrepreneurs, freelancers, and families across nearly every industry, and I can tell you credit trouble almost always starts the same way: a missed due date, a forgotten business charge on a personal card, or a reporting error nobody caught in time. The good news? The same financial habits that keep a business healthy will also raise your credit score. In this article, I’ll walk you through the highest-impact steps, how utilization really works, how to repair late payments, how to dispute errors like a pro, and how long real progress takes, so you can take control with confidence.
How do you improve credit score fast?
- Improve credit score by correcting report errors, paying on time, lowering utilization, limiting new applications, and maintaining accounts responsibly.
- Payment history is the single most influential FICO factor, accounting for 35% of your score, with amounts owed close behind at 30%.
- A lower credit utilization ratio can produce faster improvement because lenders typically report updated balances monthly.
- Disputing inaccurate items with both the credit bureau and the company that supplied the data can remove incorrect negative information.
- No legitimate service can guarantee an overnight increase; durable gains come from accurate records and repeated on-time payments.

What Determines Your Credit Score and Where Should You Start?
Credit scores summarize how lenders may interpret your borrowing behavior. Before changing anything, pull your reports from Equifax, Experian, and TransUnion, identify the biggest scoring problem, and attack that first. FICO scores are driven by five factors: payment history (35%), amounts owed (30%), length of credit history (15%), new credit (10%), and credit mix (10%), which is exactly why on-time payments and lower balances deliver the fastest wins.
Credit score improvement: identify the highest-impact problem
Start by reviewing:
- Late or missed payments
- Credit card balances compared to limits
- Accounts in collections
- Recent hard inquiries
- Account age and recently closed accounts
- Incorrect personal information or unfamiliar accounts
Build a one-page “credit action sheet” listing every account, balance, limit, minimum payment, due date, and status. This bookkeeping-style inventory is the same discipline we teach small-business clients, and it keeps small accounts from quietly damaging your score.
How to improve credit score fast without creating new damage
Follow this sequence:
- Set automatic minimum payments on every account.
- Direct extra cash toward the card with the highest utilization.
- Ask creditors when they report balances to the bureaus.
- Pause unnecessary credit applications.
- Review reports for errors and submit disputes immediately.
- Track changes monthly rather than refreshing your score every day.
A higher score doesn’t automatically mean approval. Lenders also weigh income, debt-to-income ratio, and their own underwriting standards.
How Does Credit Utilization Affect My Score?
The credit utilization ratio is the percentage of available revolving credit you’re using. A $2,000 balance on a $10,000 card equals 20% utilization. The CFPB and most consumer guidance recommend staying below 30%, and lower is typically better.
Credit utilization ratio: reduce reported balances
Prioritize this way:
- Pay down the cards closest to their individual limits first.
- Make an extra payment before the statement closing date so a lower balance gets reported.
- Avoid charging balances back up after paying them down.
- Don’t close a no-fee card just to simplify, because losing that limit can spike your utilization.
Example: Three cards with combined $15,000 limits and $6,000 in balances equal 40% utilization. Paying down to $3,000 drops you to 20%, often triggering a score bump within one reporting cycle.
How does credit utilization affect my score when I pay in full?
Paying in full by the due date avoids interest and supports payment history, but the balance reported before your payment may still show up on your score. Pay earlier in the billing cycle to make sure a lower number lands on your report.
How Can Payment History and Late Payments Be Repaired?
Payment history is the foundation of credit rebuilding. The CFPB recommends paying on time every time, getting current after missed payments, and staying current from there forward.
Payment history: prevent the next late payment
Set up:
- Automatic payments for at least the minimum due
- Calendar reminders several days before each due date
- A dedicated account for recurring debt payments
- Low-balance alerts
- A weekly cash-flow review
Autopay is a safety net, not a substitute for monitoring. Confirm funds are available and every payment actually posted.
Steps to improve credit score after late payments
- Bring the account current immediately.
- Contact the creditor and ask about a goodwill adjustment.
- Verify the late payment is reported accurately.
- Dispute information that is incomplete, duplicated, or incorrect.
- Avoid additional late payments for the next six to twelve months.
- Call a nonprofit credit counselor if minimum payments are no longer affordable.
Be cautious of any company promising guaranteed deletions or overnight score jumps. Accurate negative information generally can’t be removed just because it’s inconvenient.
Building better credit starts with smarter financial habits! 💡 Let Complete Controller simplify your small business bookkeeping, improve cash flow visibility, and help you make confident financial decisions. Get expert bookkeeping support today!
How Do You Check Credit Report Accuracy and Dispute Errors?
An inaccurate credit report can tank approval chances even when your income and habits are strong. Consumers can pull reports from all three nationwide bureaus through AnnualCreditReport.com, and the three bureaus must provide a free report each week, making it easier than ever to catch errors early. The CFPB recommends disputing errors with both the reporting company and the information furnisher.
Credit report accuracy: review every bureau
Compare each report for:
- Accounts that don’t belong to you
- Incorrect payment dates or delinquency status
- Wrong balances or credit limits
- Duplicate collection accounts
- Accounts shown as open after closure
- Outdated negative information
A creditor may report different data to different bureaus, so checking only one leaves blind spots.
Credit report dispute process to improve score
- Save the report showing the error.
- Gather statements, payment confirmations, or identity-theft records.
- Submit a clear written dispute to the bureau.
- Send a separate dispute to the furnisher.
- Keep copies, dates, and confirmation numbers.
- Review the investigation result and updated report.
How Can a Secured Card or Credit-Builder Product Help?
For consumers with limited or damaged credit, a secured card can support credit rebuilding when the issuer reports to all three bureaus. These cards generally require a refundable deposit that sets your credit limit.
How to raise credit score with a secured credit card
- Confirm the issuer reports to all three major bureaus.
- Choose a card with manageable fees and a clear graduation path.
- Use the card for one small recurring purchase.
- Keep utilization low and pay in full before the due date.
- Never apply for several cards at once.
A credit-builder loan is another option, but it creates a payment obligation, so compare fees and reporting practices before signing.
How Long Does It Take to Improve Credit Score?
Timeline depends on the cause of the low score and when creditors report updates.
Short-term improvements
- Lowering a high card balance may help within one reporting cycle.
- Correcting a confirmed error may help after the bureau updates the file.
- Bringing an account current prevents further deterioration.
Longer-term credit rebuilding
- Six to twelve months of on-time payments builds meaningful positive momentum.
- Most negative information, including late payments, generally stays on a credit report for seven years, and bankruptcies can remain for up to ten.
- Older delinquencies matter less as newer positive history accumulates.
Conclusion
To improve credit score, start with a full report review, automate every payment, lower revolving balances, dispute inaccurate items, and skip credit applications you don’t need. Add a secured card or credit-builder product only if it’s affordable and reports to all three bureaus.
At Complete Controller, I’ve learned that financial progress sticks when it’s supported by accurate records and a repeatable cash-flow routine. Pick three actions today: set up autopay, calculate each utilization ratio, and download all three credit reports. For help building the financial systems that support stronger credit and clearer cash flow, visit Complete Controller and connect with our team.
Frequently Asked Questions About Improve Credit Score
How can I improve my credit score quickly?
Pay down high-utilization credit cards, correct report errors, bring past-due accounts current, and prevent new late payments. The fastest wins usually come from lowering reported revolving balances or fixing inaccurate data.
How many points can a credit score increase in one month?
There’s no universal number. Changes depend on the scoring model, current utilization, account history, and whether a creditor reports a lower balance or corrected error during that cycle.
Does paying off a credit card improve credit score?
Yes, paying down or paying off a credit card reduces utilization and often improves your score. Keep the account open if it has no fee, because closing it reduces available credit.
How long do late payments stay on a credit report?
Accurate late payments generally remain on a credit report for seven years, though their impact fades as positive history grows. Bankruptcies can stay for up to ten years.
Does checking my own credit report lower my score?
No. Checking your own report is a soft inquiry and does not affect your score. Regular self-checks are a core part of monitoring credit-report accuracy.
Sources
- AnnualCreditReport.com. “Request Your Free Credit Reports.” Accessed October 17, 2026. https://www.annualcreditreport.com/
- Consumer Financial Protection Bureau. “How Do I Get and Keep a Good Credit Score?” December 12, 2024. https://www.consumerfinance.gov/
- Consumer Financial Protection Bureau. “How Long Does Information Remain on My Equifax Credit Report?” Accessed October 17, 2026. https://www.consumerfinance.gov/ask-cfpb/how-long-does-information-remain-on-my-equifax-credit-report-en-323/
- Consumer Financial Protection Bureau. “How to Rebuild Your Credit.” June 24, 2025. https://www.consumerfinance.gov/
- Consumer Financial Protection Bureau. “Understand Your Credit Score.” June 4, 2025. https://www.consumerfinance.gov/
- Consumer Financial Protection Bureau. “What Is Credit Utilization?” Accessed October 17, 2026. https://www.consumerfinance.gov/ask-cfpb/what-is-credit-utilization-en-1200/
- Fair Isaac Corporation. “What’s in My FICO® Scores?” myFICO. Accessed October 17, 2026. https://www.myfico.com/credit-education/whats-in-your-credit-score
- Federal Trade Commission. “Disputing Errors on Credit Reports.” Consumer.ftc.gov. https://www.consumer.ftc.gov/articles/disputing-errors-credit-reports
 About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud platform where their QuickBooks™️ file, critical financial documents, and back-office tools are hosted in an efficient SSO environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity.



 Brittany McMillen