4 Financial Risks Small Businesses Face and How to Deal With Them

Financial risks are taken on by every business, no matter the size. For the large business owner or shareholders, the risks are minimized by the amount of revenue coming in that covers it. For the small business owner, every decision carries a risk. Most small businesses fail within the first five years. The highest percentage of those are within the first year. However, this does not have to be the case. The failures don’t stem from poor decision making alone. They stem from not understanding the risks and safeguarding your business from these risks to eliminate them or minimize them.

Preparation for your small business should include making a business plan. Within that plan, there should be market and financial analysis. This analysis is where you can discover and assess the risks of starting your small business and how to handle them so your business will succeed. Here are four financial risks small business owners face and how to minimize or eliminate them. Check out America's Best Bookkeepers

Failure to Plan

Every aspect of starting and running a small business is a financial risk. This risk comes from issues with financing and working to turn a profit during your first year in business. Depending on the type of business, you usually don’t start in the black as far as finances. This means that you have to acquire financial backing, whether from your savings, investors, or lenders. If you obtain financing from alternative sources, the financial risks increase as they are either looking for a return of investment or repayment of the loan. Both carry risks against your business if you are unable to produce.

To minimize or eliminate this risk, you should have a strong financial projection in your business plan, and beyond startup, you need to continue implementing financial forecasting. If it is your first year in business, you can use market and competitor trends to forecast month to month what your business finances may look like. If you have been in business for more than a year, you can use your previous year’s financial statements to help you forecast. Financial forecasting will help you prepare for downturns or business slowdowns if they are expected. It will also help you plan how to utilize the money best in those times when business is booming.

Product or Service Failure

Though you may believe you have the best service or product idea or business plan, customers may disagree. Every business is dependent on some level of sales to survive, but if what you are selling isn’t any good or if it is good but not something people need or want, your business will not survive, and that could potentially no only hurt you as the business owner. Still, it could hurt any other investors in your business.

To avoid this, you should do a market analysis. The market analysis is as it sounds. You research and analyze the market to which your product or service belongs. You don’t want to just focus on current trends because those can come and go, and if you are only offering something that is currently on-trend, you will go out of business when it is no longer the hot thing. Your focus should be on a product or service that has a long life ahead of it.

Don’t count trends out totally. If you have a central and timeless product or service, you can then add some products and services on trend to give your business boosts. If you are creative, you can even be the one setting the trends. Check out America's Best Bookkeepers

Risky Financing

Most small businesses can’t operate at startup or the first few years without outside financial sources. Therefore, you will need to seek out financing. While there are many reputable lenders and investors, there are equally those that are not. Before entering into any contract for financing, make sure you go through the contract thoroughly. It would even be suggested that you consult a lawyer to ensure nothing in the financial contract could later come back to hurt you or your business. Both investors and lenders can add things into the contract that could give them your business should you fail to return on their investment or repay the loan.

Though all financing carries some level of risk, some are riskier than others. When seeking financing, you must do a lot of research and choose wisely.

Not Knowing Your Target Market

Many business owners make the mistake of believing that their product or service is perfect for everyone. While this kind of confidence is encouraged, it is not realistic. Even products or services that everyone uses varies from person to person. Also, when considering your target market, it is not always the person who will use the product that you target but rather the one going to do the purchasing. For example, grocery shopping is generally done by one household member. Each person in the household may need things from the grocery store, but the person making the purchase and selection may not use the product. So in some cases, those who sell grocery items may only want to target the person doing the purchasing, not necessarily the person who will be consuming the product. Check out America's Best Bookkeepers

Market and target audience analysis are crucial if you want to get your share in the market. Once you identify your target market, then you should put all your marketing efforts towards them. This targeting will increase sales and minimize financial risks.

Conclusion

For the small business owner, part of owning a business is facing financial risks. However, as long as the small business owner recognizes the risks and understands how to overcome them, they will not affect the business. Owning and operating a business can be fulfilling and challenging all at the same time, but if you’re prepared, you can overcome those challenges, and your business will succeed.

Check out America's Best Bookkeepers About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity. Check out America's Best Bookkeepers

6 Reasons You Should Hire a Tax Accountant for Your SME

No matter if a person is running a small or medium business or SME, it is important to hire a professional to perform tax services. Tax accountants are responsible for preparing and filing your business’s taxes. Furthermore, the tax accountant’s job is to do a detailed assessment to ensure that the business’s financial activities are running smoothly. The tax accountant also plays a major role in keeping the business operations in a prosperous and healthy state. A business person who is thinking of initiating a startup needs to make a proper plan. This plan includes including different strategies on how to engage professionals, tax compliance, and cash flow. Check out America's Best Bookkeepers

Instead of using accounting software or doing the business taxes yourself by hand or using handwritten books, hiring a tax accountant for the business makes good sense. Here are six reasons you should hire a tax accountant for your SME.

Helps the Business Save Time

As a business owner, there are several important responsibilities to conduct properly to run business activities more smoothly. Responsibilities of an entrepreneur include marketing, selling of products and services, and budget planning. A tax accountant is responsible for ensuring that the business’s financial side gets taken care of accurately. Hiring a tax accountant will allow the business owner to run operations to accomplish business goals within a short period. Check out America's Best Bookkeepers

Helps the Business Avoid Costly Mistakes

Due to the number of responsibilities that a business owner has, it becomes challenging to ensure that every business operation is accurate. There is a high risk that entrepreneurs will make some serious mistakes when dealing with the tax filing process in such cases. These mistakes can either cost the business a lot of money or worse; they can cause the business to be shut down.

To remedy these issues, there is a need for a tax accountant to help the organization navigate the business processes in the easiest way possible. This approach will help the organization to save the business amounts to prevent errors.

Helps Businesses Deal with Complicated Tax Filing Processes

The process of paying taxes is considered a ‘cumbersome affair’ because, to file taxes, it is important to fill out the appropriate form accurately by providing facts, including details of accounts, income, expenses, and payroll. All of these factors are necessary to keep the businesses on the right track. Hiring a tax accountant will help a business owner take care of all these issues efficiently.   

Helps the Business Identify Deductions

Hiring a tax accountant will help the business owner identify the potential deductions and provide the best possible advice. This advice will help an entrepreneur to make strategic decisions concerning year-end deductions. It has been observed that business owners often forget to keep track of the items like home office space, out-of-pocket expenses, and depreciation. Check out America's Best Bookkeepers

Helps Reduce Tax Liability

The job of a tax accountant is to know and understand tax laws and regulations. They also understand the current deductions available to the business. Understanding the laws, regulations, and deductions and finding other ways to cut taxes by reviewing the books will ensure that the business owes as few taxes as possible.

The tax accountant can also look at ways to save on your taxes throughout the year instead of just during tax season.

Helps the Business Grow

Hiring a tax accountant can help a business grow by keeping all the financial aspects of the business well recorded. These records can produce financial statements that will help the business owner understand what kind of capital the business has for growth. With a tax accountant taking care of the business’s financial side, the business owner can concentrate on other business areas, such as operations, and focus on growth.

Check out America's Best Bookkeepers About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity. Check out America's Best Bookkeepers
6 Ways to Invest as a Couple

Creating wealth management is something every financially responsible adult should do. This doubles whenever you become a couple. Regardless of your plans for marriage, owning a home, and having kids, planning for your financial future should be a priority for you as a couple. To plan wealth management requires you as a couple to sit down and have a financial discussion.

Some couples don’t combine their finances or manage them together, let alone invest together. Whether you have joint accounts or keep your finances separate, you can still invest as a couple. It is a matter of communication. You need to come together and discuss what your investment goals are, clarify your expectations, and discuss your risk tolerance. Check out America's Best Bookkeepers

Once you have established what you desire and expect, you can find common ground and work your way from there. If you invest as a couple, it is essential that you are on the same page, or the investment process could be overly challenging and even contentious.

After you have firmly established where you want to invest and how much you want to dedicate to investing, you have to choose where to invest as a couple. Here are six ways you can invest as a couple.

401(k) or Workplace Savings Plan

Like you might do as an individual, you can both invest in your company’s 401(k) or other workplace savings plans. If both of you have company 401(k) or other savings plans, both of you should be investing money into them. However, this investment needs to be strategic. If your company (many do) offers to match up to a certain percentage of your income, you should choose the one that carries a higher percentage.

You should be investing as much as you can afford this investment. The most important thing is to leave the money in the 401(k) because withdrawals have penalties, and they also get taxed after they come out since they go into the 401(k) before taxes. Check out America's Best Bookkeepers

Traditional and Roth IRAs

Traditional IRAs or Roth IRAs are individual retirement accounts opened by the investor at the banking institution of their choice. A traditional IRA has tax-deductible contributions and is tax-free until withdrawal. A Roth IRA is tax-free going in and coming out as long as you withdraw after retirement.

IRAs could be invested jointly, or you could have separate IRA accounts. It would probably be more profitable to put it all in a joint IRA so that more could be invested to get you a higher rate of return.

Health Savings Accounts

Though the Health Savings Account can only be used for qualifying medical expenses, the contributions and withdrawals are tax-free; therefore, it can reduce healthcare costs. These accounts can also gain extra revenue if your company does matching contributions.

Taxable Brokerage Accounts

Taxable brokerage accounts are accounts opened at a brokerage firm after the application approval. These accounts allow the firm to trade and buy or sell stocks on your behalf. There are no limits to the number of these taxable accounts you can have. Some investors may choose to have accounts at multiple brokerage firms. Diversifying your brokerage account investments can protect you in case of a downturn in the market in which you are invested. Check out America's Best Bookkeepers

Individual stocks

As a couple, you can buy individuals docs and companies, which means you are buying ownership. This can be done after a company goes public and offer shares in ownership to those who can afford to buy them. These stocks can later be bought and sold on an exchange between sellers and buyers through a stockbroker. Money can be made when the stock appreciates, and you sell it, or it can be made when profits are made on the company, and you receive a portion of those profits for being a shareholder.

These investments have no limit as far as what you can make; however, that means there is no limit regarding the losses either.

Mutual Funds

Mutual funds are an investment in which you pull your money and other investors to buy more shares in a collection of bonds, stocks, and securities. The price of a mutual fund is called the net asset value. It is the total value of the securities in the portfolio then divided by outstanding shares. The price varies based on the value held by the portfolio at the end of each day. One of the differences between mutual funds and individual funds is that be investors do not own the individual stocks or investments they are investing in the fund itself.

Check out America's Best Bookkeepers About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity. Check out America's Best Bookkeepers
5 Essential Steps to Creating a Business Budget

Having a business budget is as important as having a household budget. The purpose of the two budgets is similar in some ways and diverse in other ways. A business budget is an outline of monthly operational income and expenses. Still, your business should have a yearly budget so you can work to cover it with or without financing. You should have at least a six-month business budget before you start your business and should adjust as you work through the year.

The business budget is essential for making financial decisions but can also be important when trying to obtain financing from investors or lenders. Here are five essential steps to creating a business budget. Check out America's Best Bookkeepers

Add Up Your Income Sources

When writing your business budget, you need to figure out all your income sources. This will be cash flow and any other positive income that you use to operate your business. This can be from financing, sales, outstanding accounts receivable, and refunds.

Once you have all your income sources, you will enter them into your budget, broken out by source, and finally calculating your total income.

Determine Your Fixed Costs

Fixed costs are those expenses that will always be the same month to month. It is best to always have your fixed costs at the top of your expenses since they will not change. Generally, fixed costs are your lease, fixed utilities, internet and phone services, and payroll. If you have any other expenses that are the same every month, you should add it to your budget’s fixed costs.

If you cannot determine your fixed costs, you can use a bank statement to see what costs were consistently the same. Once you figure out your fixed costs, you will total them on your budget. Check out America's Best Bookkeepers

Determine Variable Costs

Variable costs are all the expenses that don’t fall in the fixed costs category. These are any expenses that change from month to month in an amount or due date. These expenses are usage-based utilities, travel costs, commissions, or any other fluctuating expenses.

Since variable expenses can change from month to month, they can be difficult to budget. However, you can budget for the average or general cost each month. When looking at variable costs, if you are not making enough to cover the budget, this is where you will look for expenses to cut. This is similar to a household budget in that if you aren’t making your business ends meet, you will use your budget to help you determine where to cut.

One-Time Spending

While most of your expenses, whether variable or fixed, will be the same each month, there are also costs that only happen on occasion that need to be added to the budget. These costs can be easily forgotten when they are not a regular expense. Make a list of these expenses, so when you are making your yearly budget, you can add them and also add to the monthly budget when the time is appropriate.

These one-time expenses will fall into two categories, planned and unplanned. While you may wonder how you can add unplanned expenses, you should have a miscellaneous yearly expense that will be used to cover those unplanned expenses that inevitably come up. Check out America's Best Bookkeepers

The most important thing to remember when figuring out your expenses is that you are striving for your business always to be prepared for all possibilities so that nothing will leave you devastated and possibly out of business.

Putting it All Together

Once you have gathered every source or possible source of income and your variable, fixed, and one-time spending costs, it is time to put your budget together. Make sure you have every category covered and the most accurate amounts possible.

Once you have your budget put together and have totaled everything, you will use your budget to compare cash flow out and cash flow in to see your profitability and see whether you are in the black or need to seek financing.

Check out America's Best Bookkeepers About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity. Check out America's Best Bookkeepers
6 Things You Must Consider When Choosing Your Banking Institution

Banking is something that everyone who earns a paycheck has to consider. While there may be some that don’t use a bank, it is uncommon. With so many people keeping their money in banks, new banking institutions, especially online, have increased. This leaves people who need a bank account or are unhappy with their current banking institution with a wide variety of choices.

Sometimes, like at a restaurant that has far too many choices on the menu, having such a wide variety of choices in banking institutions makes it difficult to choose one that’s right for you. There are several things to consider when choosing your bank. Here are six tips to help you choose a bank that fits your banking needs. Check out America's Best Bookkeepers

Account Type

The first thing you need to consider before choosing a bank is what type of account you need. First, you need to decide whether you need one account or multiple accounts. Many people will have both a checking and savings account in the same banking institution, often linking them together. However, today, people are more concerned with bank accounts that help them earn money or invest in their future savings.

Savings accounts at most banking institutions do not have a very high yielding interest rate. However, online banks have generally been offering higher-yielding interest rates on savings accounts or checking accounts. They can do this because they have less or nonexistent fees. Many banks also offer cashback bank accounts to earn money every time you use your debit card or checking account. Also, many checking accounts offer the ability to put away spare change. The idea is that it is rounded to the nearest dollar, and that difference will be put into savings.

Fees and Balances

An important thing to consider when choosing a banking institution is what kinds of fees and balances they have or require. Many banks will charge exorbitant fees for overdrafts and some banking transactions. Some banks require minimum deposits or balances, or they will charge additional fees. It is important when you are choosing a banking institution that you look into what their fees and policies are on balances. These fees could end up costing you a lot of money. So look for a banking institution that has minimal fees and balance requirements. Check out America's Best Bookkeepers

Accessibility

When opening a bank account and choosing a banking institution, a crucial thing to consider is accessibility to the accounts. You want to consider whether your banking institution has multiple ATM locations and multiple branches for cash withdrawal and in-person banking needs. While many will do most of their banking online in recent surveys, many people still prefer to do some of their banking in person.

Online banking has taken the financial industry by storm. It has even established banks that are 100% online. Many of these banks appeal to customers because they have lower fees due to low overhead and offer higher-yielding savings accounts. Some still prefer brick-and-mortar traditional banking more prefer to complete all banking transactions through mobile devices and online. When considering what bank to put your money into, accessibility needs to be a high priority consideration.

Credit Unions

Many people who are considering opening a new bank account or switching banks disregard credit unions. While credit unions usually have some membership requirement, they are much easier today to qualify for in the used to be. If you can get a bank account at a credit union, it is highly recommended.

There are many advantages to banking with a credit union. They often have lower fees and higher interest rates on savings accounts. They also have membership benefits not offered at other banking institutions. Because they value their members, they will often work with members who may have faulty credit. The only disadvantage is that most credit unions are local and don’t have ATMs. But to make up for this, many credit unions reimburse and waive all ATM fees. Check out America's Best Bookkeepers

Online Banking

While almost every banking institution offers online versions of banking and banking through your devices, there is also a surge of banks that are contained 100% online. When speaking of banks that are centralized only to the online environment, there are many advantages to using these for your bank account. Online banking institutions generally have lower fees and, in some cases, no fees. They also offer higher-yielding interest rates on savings accounts. They can do this because they have no overhead and can pass those savings to their customers.

It should be noted that there is no possible way to deposit cash since there is no brick-and-mortar location or branch. To combat this single disadvantage, you can use your cash to purchase gift cards through major credit card companies that will work like a debit or credit card for purchases.

Terms and Conditions

The final thing you want to consider when choosing your banking institution is the terms and conditions of the bank your considering. It is imperative that you need every line of the bank’s terms and conditions before depositing money into it. Many banking institutions have hidden fees and requirements that could end up costing you money. Though we live in a society where we often skip the terms and conditions, it is important when choosing a bank that you read them. You may find there are some deal breakers hidden within the words.

Check out America's Best Bookkeepers About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity. Check out America's Best Bookkeepers
What Financial Personality Trait Are You?

Psychology plays a big role in every aspect of life. Every person possesses a different kind of personality and has unique traits. Behavioral economics plays a major part in defining a person’s financial personality. According to your characteristics, pick from this financial personality list and know more about yourself and your personality traits.

Virtuoso: You belong to the virtuoso personality if; you are full of spiritual wealth, generosity, honesty, and love spending the money to benefit family and friends. But while doing so, make sure you don’t lose all your income and spend smartly—plan about savings in any responsible mutual funds, insurance plans, or legal currency accounts. Check out America's Best Bookkeepers

Persistent: You belong to a persistent group of personality if you have these traits; Persistent financial persons are consistent and stick to their routine of spending. You never spend on new things and stick to your plan of expenses. As a persistent financial person, you never like a surprise expense. You have a financial plan that you follow religiously, and you are superglued to it no matter if your favorite dress in sales this month. If it is not on your list this month, you will not spend on it.

Perilous: You are not afraid of taking risks. You are prone to have fun even at the expense of losing all your salary at once before the month ends, and you love that others have fun with you. Taking a risk with money makes you ecstatic. You believe in YOLO and live the moment. Check out America's Best Bookkeepers

Architect: You are a planner. You draw your financial map and follow it. You know where you have spent each of your pennies, which is a commendable task. You love detailing and can pen down your financial break down precisely. You work on your financial matter your way because nobody knows them better than you. You plan about emergency expenses beforehand and have a saving plan for yourself.

The child: You don’t think about the future; you follow your heart. You seem to be contented with whatever you have, and that’s why you have not saved the amount you must have saved by now. Your savings are low returns. You need the motivation to start saving and realize why saving is important.

The scared one: For you, money is a very serious matter. You keep checking your account balance and spend time thinking about where that $1 was spent. You are afraid of making a financial mistake and losing even a small amount of investment. You tire yourself up by analyzing every single detail of your expenditure. You are unable to make important decisions about the money. But the matter of fact is, it is better not to do anything in which there is money to risk.   Check out America's Best Bookkeepers

The multiplier: If you have a multiplier financial personality, you are prone to risk and invest in every opportunity that you think will multiply and increase your wealth. This might sometimes lend you in trouble as not every risk is worth taking. Investment is a gamble that does not guarantee profit every time. Sometimes you gain, and sometimes you lose. The negative trait of having a multiplier personality is that you are not afraid of losing, so you invest without thinking twice and losing your investment. It is not bad to invest in multiple projects, but you should discuss it with a financial adviser to minimize the risk.  The ostrich: An ostrich buries its head when it senses danger rather than running away or saving himself. The same is with you if you have an ostrich personality. Rather than going through your financial plans and organizing them, you keep spending until you know that your account balance is zero. As soon as someone starts earning, they must spend some time reviewing the expenses and plan it out for the future. It is true that in different aspects of our lives, we all have different customs and characteristics. Psychology impacts financial aspects, as well. If you have found out about your financial personality by now, then work on improving it. Check out America's Best Bookkeepers About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity. Check out America's Best Bookkeepers
6 Reasons Your Business Should Switch to E-invoicing

Most businesses, no matter their size by now, have switched to e-invoicing. But some small businesses are having a hard time making the switch from a manual process to an electronic one. Most accounting and bookkeeping software have e-invoicing options, or there is software specifically dedicated to the electronic billing option to help make the transition.

Business owners who may be hesitant to switch to e-invoicing should know there are no disadvantages to doing so except possibly the software cost, which will be made up in the e-invoicing process. Here are six reasons your business should switch to e-invoicing. Check out America's Best Bookkeepers

Higher Efficiency

The process of invoicing is generally a cumbersome task for any business. The process is to create the invoice, check for accuracy, print, mail to the buyer, wait for payment, and then enter your servers’ payment. E-invoicing bypasses the difficulties associated with traditional invoicing. Besides invoicing software, you can use a downloadable and customizable e-invoice template instead of creating it from scratch. The most efficient aspect of e-invoicing is that you will avoid the hassle of printing and sending it to the customer, as your e-invoice can be billed immediately. The payment can be made right away, keeping your cash flow accurate and well documented.  Check out America's Best Bookkeepers

Cost Reduction

The process includes many costs such as printer ink, paper, postage, and the time you pay an employee to process invoices. You can purchase invoicing software, and the rest of the process is cost-free since you will be sending the invoice electronically. Though individually, the costs may be less than a dollar, depending on how many invoices you generate per month or year, the cost could add up, and the cost of the software would pay for itself fairly quickly.

Avoiding Data-Entry Errors

Traditional invoices depend on data entry to be completed. Even scanning invoices that are returned with payment will require manual processing. Besides the consumption of time to do the data entry, there is room for entry errors. Even one decimal point entered incorrectly can end in a costly mistake. E-invoicing makes the entire process electronic. The accuracy will then be 100% rather than some room for error by doing it manually.

Better Access, Tracking, and Control

Most e-invoicing software offers the ability to access your e-invoicing data from any device, making it accessible from anywhere. The e-invoicing software lets you know when the customer opens the invoice, makes a payment, or communicates about the invoice. There are reports, analytics, and insights into your operations through the electronic process, enabling you to optimize them further. Check out America's Best Bookkeepers

Account Reconciliation

Businesses being suppliers to customers know that if there is any process for your business that includes deferred payments, invoicing is difficult to reconcile. This reconciliation is especially difficult when your customers may pay invoices all at once or break it up into lesser payments on their own. With e-invoicing, the process will be simplified, and the same no matter how your customer decides to make payments. The e-invoicing process allows for every type of payment and will record it accurately.

Reduced Carbon Footprint

With so many people concerned with the environment, e-invoicing is surprisingly environmentally conscious. You will save on paper products and non-biodegradable ink cartridges in your budget, and it will also save on their impact on the environment. Other waste reduction in the manual invoicing process will overall reduce your business’s carbon footprint.

Conclusion

Switching to e-invoicing has many advantages and no known disadvantages. It increases efficiency by saving time in the process and increasing the invoicing process’s accuracy. The data entry is built into the software and done upon receiving payment through the e-invoicing process. Because of the electronic process, you will also have better tracking, reporting, and control, which can make your business’s financial aspect more accurate.

Check out America's Best Bookkeepers About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity. Check out America's Best Bookkeepers
3 Things You Should Stop Overpaying For

Every financially responsible adult generally has a budget. If you are not meeting that budget, it may be because you are overpaying for some of the bills or other items you purchase. When considering your monthly or yearly budget, you should look for ways to lower your payments instead of completely cutting out items. Here are three things you should stop overpaying for. Check out America's Best Bookkeepers

Cable

Entertainment is the number one area most people overpay. Many get cable packages with hundreds of channels, and studies show that people generally regularly watch about seventeen of them. There a few ways you can save money when it comes to cable.

Get a smaller cable package: Knowing that most people only watch a handful of channels, you should assess what channels mean the most to you and get a cable package that includes those channels and as few channels more as possible.

Use cable services you can customize: A few services will let you completely customize the included channels, so you can choose to leave out channels you never watch and keep only the ones you do.

Cut out cable altogether: Many have “cut the cable” and never regretted it. You can have multiple streaming services which generally carry many of the shows you love. If you add up the monthly subscriptions with access to hundreds of movies and shows, you can have them all and still pay far less than cable. Also, you can choose when you watch the shows. Check out America's Best Bookkeepers

Car Payment

Many people overpay for their car and often because car salespeople are good at what they do. You can, however, beat them at their own game with a few pro tips.

Never purchase payments: Often, when in the negotiation process, a salesperson will at some point ask you what kind of payment you can afford. This is where it gets tricky. Never give the maximum you can afford, and be sure they don’t come back and give you only the car payment and length of the loan. Even if the payments are comfortable, you may have agreed to pay significantly more than you should because of the length of the loan. Be sure to ask for the total cost of the car and the interest rate.

Get a Loan Yourself: Many people don’t realize that they can go to their banking institution and get a preapproved loan for a certain amount if they have decent credit. They can then look to purchase a car for that amount or lower using that preapproved loan. This is a way to get a super low-interest rate and no hidden costs in the car purchase because you strictly negotiate the price.

Boost your Credit: The higher your credit score, the lower the interest. If you have a good or great credit score, it gives you the negotiating power to get the lowest interest rates on your car loan possible. You can sometimes save thousands on your car purchase by having a low-interest rate. Check out America's Best Bookkeepers

Utilities

Of course, there are so many areas of life we can save or be more frugal, but utilities is an area most of us can stop overpaying. Here are a few ways you can save on your utilities.

Cut your usage: We all have been guilty of leaving lights and electronics on when not in use, but you can also cut your usage other ways besides remembering to turn things off. Many utility companies now offer thermostats built-in money-savers such as automatically adjusting the temperature for a few hours a day while you are at work, or less likely to need cooler or warmer air. You would be amazed at how that adds up.

Payment plans: Many utility companies have payment plans in which you pay the same amount every month at a fixed rate. This payment plan is generally an average calculated by the previous year’s usage. If you don’t use as much as you paid, you get the money back or get it as a credit on our account at the end of the year. If you overuse, you will have a balance due. Most find they will use less with this type of payment arrangement.

Conclusion

While there are many areas we can save in our budget, these areas are usually the three all household budgets include. However, now that you have your mind on not overpaying, you shouldn’t. Look at other areas you can adjust. You may be surprised at how naturally thrifty you are!

Check out America's Best Bookkeepers About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity. Check out America's Best Bookkeepers
Everything You Need to Know About a Money Laundering Specialist

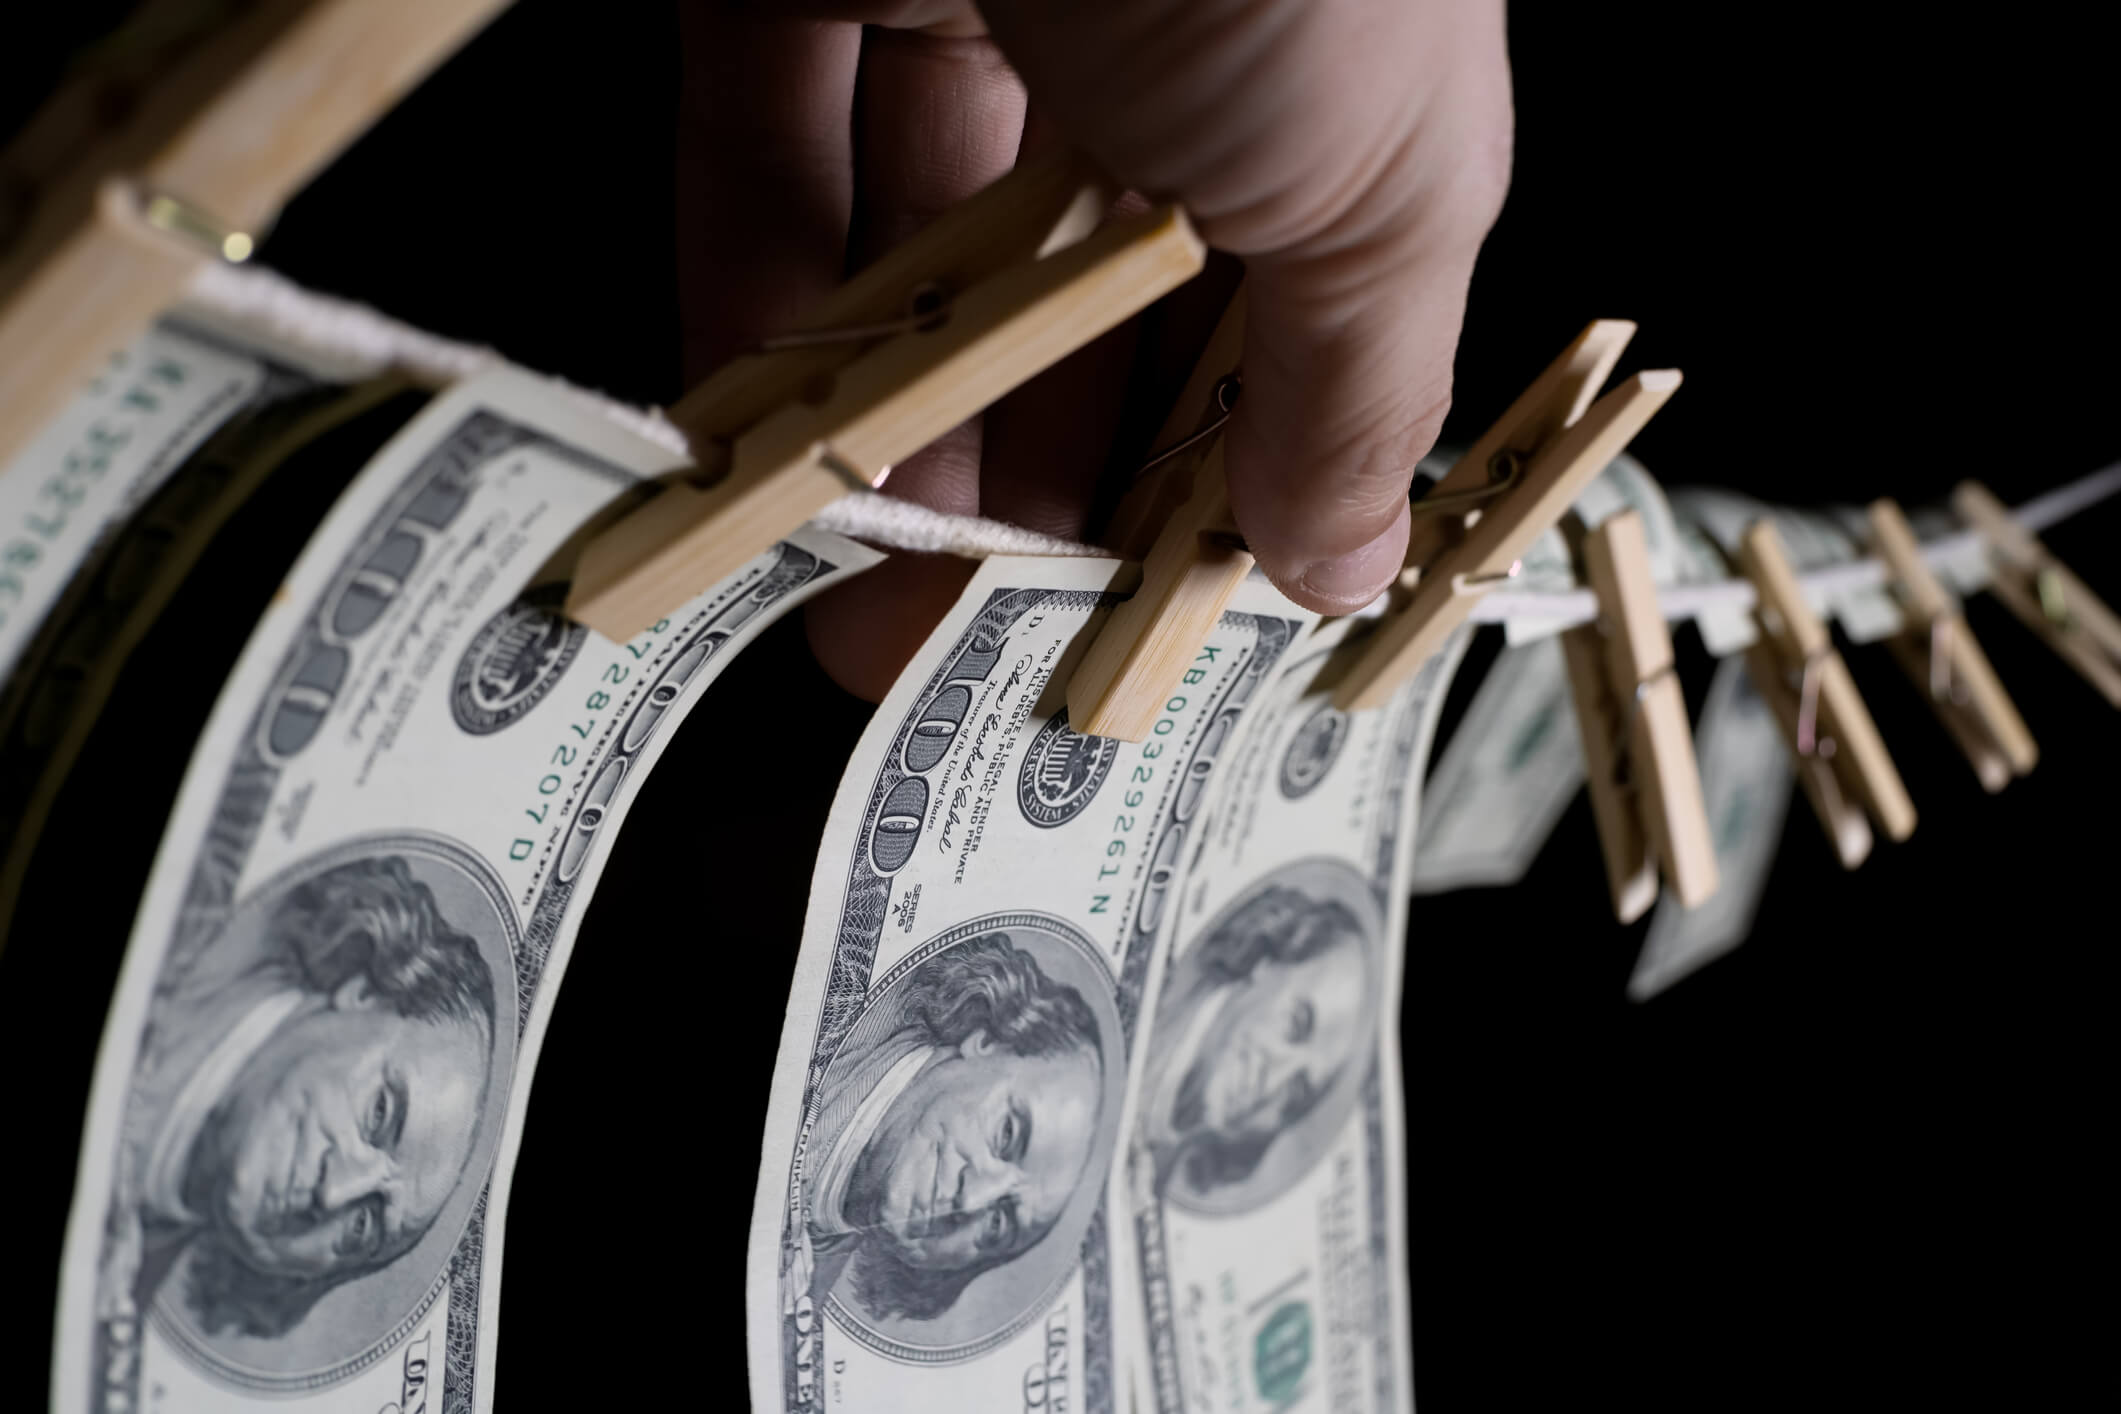
A money-laundering specialist is a financial industry professional who focuses on preventing and detecting money laundering activity. Many of these specialists belong to professional organizations and carry credentials to increase their employability. Others can get their job training and rely on experience when applying for a job. Banks regularly use anti-money laundering specialists, as do law enforcement agencies and agencies charged with implementing government policy. Check out America's Best Bookkeepers

This work requires knowledge of the laws of a specific country related to money laundering. Anti-money laundering specialists are familiar with all the law details, including the responsibilities of individual financial institutions. In banks, these people train other personnel, help establish compliance policies, and cooperate with the police when investigations arise. Their work includes everything from reporting on the client’s activity suspected of helping bank branches to train their staff to know how to submit reports by the law.

The anti-money laundering specialist is also often trained to search for money laundering signs and take appropriate measures. Even if the activities do not need to be reported to the government, they can be tracked internally so the bank can monitor clients of concern. Reports from government agencies can be prepared with a collection of information about clients. The anti-money laundering specialist helps define, establish, and reform the bank’s policy to deal with the financial industry, changes in the law, and the community.

In law enforcement agencies, anti-money laundering specialists review reports submitted by banks, insisting those interested in further evaluation. They can also help banks with legal compliance and provide assistance and training to help banks identify money laundering and take action. This work may also include the education of untrained law enforcement officers who wish to work in a working group on financial crimes. In other government agencies, these professionals create sound, comprehensive policies to combat money laundering. Check out America's Best Bookkeepers

A problem with financial crimes is that people tend to be highly adaptable when adjusting their behaviors and habits, to reduce the risk of being caught. As the law changes, people change tactics, making it difficult to track their activities. Specialists against money laundering have to think like their goals to accurately and quickly identify interest’s financial activities. The anti-money laundering specialist also needs to be alert to bribery and corruption within a bank or government agency. People are paid to look the other way when financial crimes occur.

  • Some professionals focus on the prevention and detection of practices that represent money laundering.
  • A money-laundering specialist should be alert to issues such as bribery and corruption.

Anti-money laundering compliance tools

Technology is an integral part of the anti-money laundering compliance framework. Companies can mitigate financial crime risks well by using such tech-savvy tools. There are multiple propriety AML automated tools and tricks available that are so much helpful. Check out America's Best Bookkeepers

These tools are a combination of financial services, risk, information, technology, and regulatory subject matter experts. They have lots of iterations and advantages due to the cumulative information of anti-money laundering experts. With these gadgets, clients can cope all of their complex AML compliance challenges.

Those anti-money laundering compliance tools are:

  • Computer-assisted tool for subject and investigation – There is web integration in it. It facilitates AML compliance, trade surveillance, operational risks, management of the anti-fraud case, and AML transaction tracking.
  • Entity matching or name matching tool – They are scoring tools with sophisticated matching and techniques. With it, you can improve the searching system of transaction and account details, including business lines. In this way, there will be a single client view that advances your name or entity screening, such as OFAC, PEP, etc. It also involves matching methods such as ad-hoc searches, NSL, subpoenas, etc.
  • Due diligence tool for the customer – Website is its foundation. It works as a risk rating and a single data entry point. It is highly useful for all customers and accounts details supporting Know Your Customer (KYC). The captured account data and additional clients include directors/officers of financial institutions, co-signers, ultimate beneficiaries, power of attorney, and the other associated parties.
Check out America's Best Bookkeepers About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity. Check out America's Best Bookkeepers
Everything You Need to Know About an Administrative Cost

An administrative cost is a type of business expense that has to do with expenditures related to the company’s operations as a whole and do not identify with a specific department. These administrative expenses have to do with the general maintenance of corporate records; an administrative cost helps to account for the indirect expenses that impact the business’s operations instead of focusing on a single business area. Companies of almost any size will have administrative expenses that provide support and benefit for the business operations as a whole and are not limited to just a small segment of the company. Check out America's Best Bookkeepers

Generally, an administrative cost is any expense that does not directly correlate with the business operation’s production aspects. Similarly, this type’s expenses also do not include direct costs associated with marketing or financing business efforts. Instead, these costs typically encompass tasks that impact all aspects of the operation, including production, marketing, and financing functions.

One of the most common examples of an administrative cost is the salaries of corporate executives. Although most executives have assigned tasks within the business operations, the tasks are usually broader than those of the employees who are specifically assigned to work in the production line. Similarly, the tasks associated with the supporting departments, but still critical to support production, marketing, and financial aspects, are generally classified under services’ general heading. Some examples of general services include day-to-day management of the company’s accounting records, labor relations, loss prevention, and supply and inventory functions. Check out America's Best Bookkeepers

Although not connected to a specific department within the corporate structure, monitoring administrative costs is important for its general and financial well-being to maintain control of the most direct costs. When there is a need to reorganize a company’s structure to reduce expenses and allow the company to continue during an economic downturn or the change in consumer demand that restricts production to arrive measured, there is the possibility that some changes in expenses associated with the administration or in general services will also be carried out. It is especially true if assessing the company’s structure reveals that the two executives’ tasks can be managed successfully by one.

Company benefits, administrative worker’s salaries, rent, and managerial compensation all come under administrative expenses. They are all direct accounting costs as they don’t relate to product manufacturing, such as engineering and assembly line workers. There is great involvement in the income statement. It will come under the paid condition. In the context of the tech startup, business becomes advance and expand. As a result, administrative expenditures help proportionality and stability. It occurs when front-line engineers and workers line up in size. The production level increases and the development of the latest revolutionary software or hardware came into existence. Check out America's Best Bookkeepers

Different administrative expenses have different categories. The main two types are administrative and non-administrative expenses. The first one includes the managerial team, rent of equipment & building, executive compensation, IT team, etc. The second one includes the sales team, developers, manufacturers, and engineers. You will consider the reason for business operational, sales, and administrative expenses during budgeting and forecasting. You can allocate the capital and increase the business by learning expense growth and staying stagnant. In this way, investors will notice your managing capital, the standard of business knowledge, and your style of allocating and scaling business resources.

Learn administrative expenses from the investor’s point of view for the best decision making. Such expenditures help contextualize the cost of the purchased product. It is a better way to increase the savings of investors.  You will also know about the exact proportion of all company expenses, including cash position.

Whether your business activities are sustainable for financial tensions, qualify and learn about the potential investment. If you want a business success and become a savvy investor, you know the company’s way of managing administrative expenses.

Check out America's Best Bookkeepers About Complete Controller® – America’s Bookkeeping Experts Complete Controller is the Nation’s Leader in virtual bookkeeping, providing service to businesses and households alike. Utilizing Complete Controller’s technology, clients gain access to a cloud-hosted desktop where their entire team and tax accountant may access the QuickBooks™️ file, critical financial documents, and back-office tools in an efficient and secure environment. Complete Controller’s team of certified US-based accounting professionals provide bookkeeping, record storage, performance reporting, and controller services including training, cash-flow management, budgeting and forecasting, process and controls advisement, and bill-pay. With flat-rate service plans, Complete Controller is the most cost-effective expert accounting solution for business, family-office, trusts, and households of any size or complexity. Check out America's Best Bookkeepers